
Rocket Companies (RKT) Could Be 34% Undervalued After Mortgage Rates Moved Above 7%
Rocket Companies (RKT) drew fresh attention after 30 year mortgage rates moved back above 7% following the Federal Reserve’s September hike. This development spotlighted how pricier home loans can affect its origination focused business model.
Rocket Companies’ share price has come under pressure, with the stock down 15.1% over the past 30 days and 41.2% year to date, even as the business reports a 65.2% total shareholder return over three years. This suggests recent mortgage rate headlines are feeding into weaker near term momentum, while the longer record still reflects periods of stronger sentiment around the story.
Spot 32 high quality undervalued stocks that, like Rocket Companies, are feeling rate pressure yet could be setting up for the next leg of the housing and financial cycle.Rocket Companies has been hit hard in the short term, yet still carries a strong three year shareholder return. Does it make more sense to lean into the current weakness or wait for a cleaner valuation setup?
Most Popular Narrative: 34% Undervalued
Against a last close of $11.69, the most followed narrative pegs Rocket Companies’ fair value at $17.70. This frames the recent share price weakness very differently and places more emphasis on how the business mix is changing behind the scenes.
The move to a revenue mix where more than 70% comes from servicing, purchase, home equity, personal loans, Redfin and Rocket Money subscriptions shifts Rocket Companies further away from pure rate driven refinance exposure and can support a steadier base for revenue and earnings.
The build out of AI tools that cut prospecting time, raise conversion and support roughly US$300b of fixed origination capacity with fewer production staff gives Rocket Companies room to add volume without matching growth in expenses, which can support net margins.
See why 34 investors see Rocket Companies as 34% undervalued.
Result: Fair Value of $17.70 (UNDERVALUED)
Still, if mortgage rates stay elevated and the enlarged servicing book fails to generate meaningful refinancing or home equity activity, that bullish Rocket Companies narrative begins to weaken.
Find out about the key risks to this Rocket Companies narrative.
Another View on Rocket Companies’ Valuation
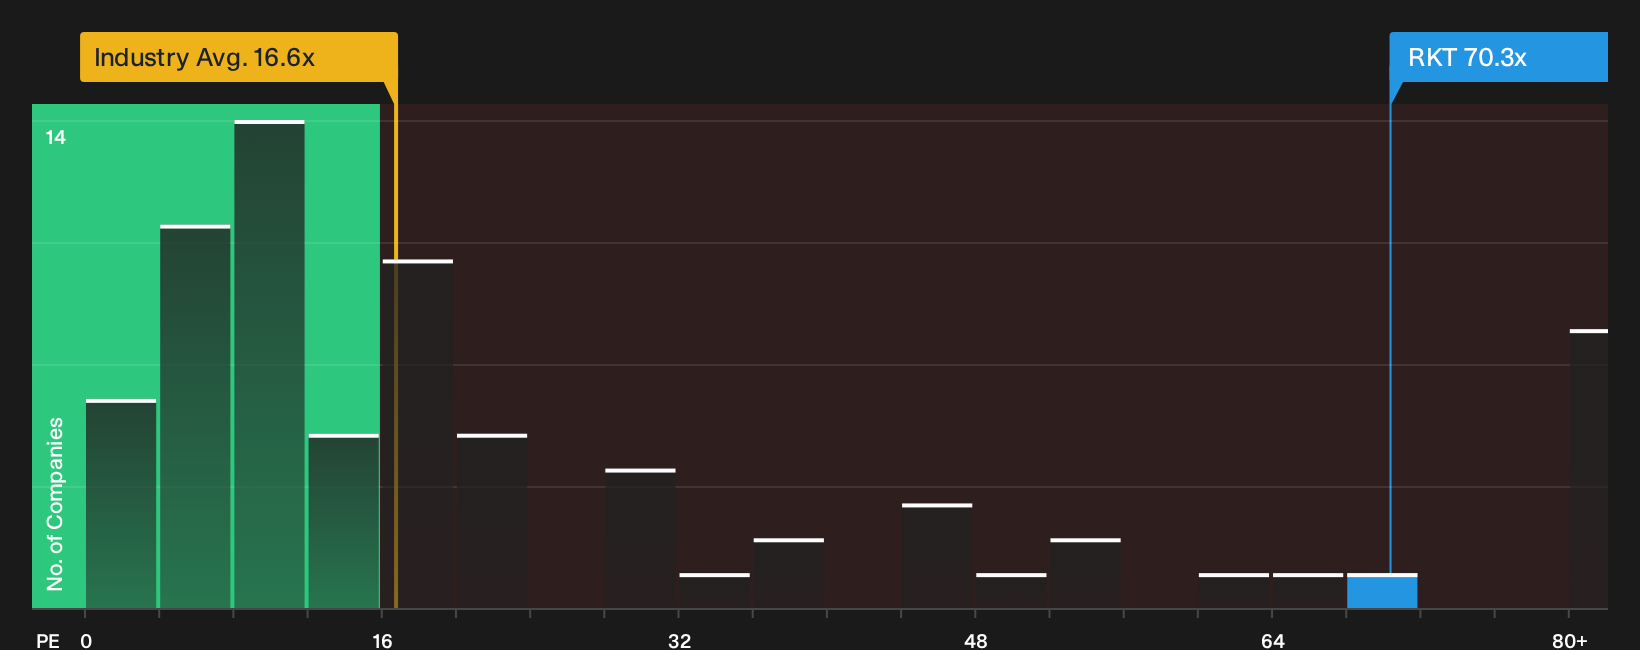
While the narrative fair value for Rocket Companies lands at $17.70 and points to an undervalued stock, the current 70.3x P/E tells a different story. That multiple is far above the US Diversified Financial industry on 16.9x and a fair ratio of 31.1x, which leans toward valuation risk rather than clear upside. Which signal do you treat as more important right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across Rocket Companies’ valuation, business mix and rate sensitivity invite a closer look. Move quickly, review the full picture and weigh both the upside and downside in the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Rocket Companies?
Rocket Companies provides one angle on housing and credit. Do not stop there. Use the Simply Wall St Screener to widen your opportunity set before the next move.
- Hunt for potential mispriced opportunities by scanning a curated list of companies that screen as undervalued through the 32 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses that feature resilient payouts inside the 6 dividend fortresses.
- Dial back portfolio risk by filtering for resilient companies with stronger balance sheets using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com