
Is Parsons (PSN) Undervalued Following Its $85 Million Space Command Contract?
Parsons (PSN) just picked up a fresh U.S. defense infrastructure assignment, a US$85 million, 75 month Owner’s Advisor role for U.S. Space Command’s new headquarters at Redstone Arsenal in Alabama.
For context, Parsons shares now trade at US$41.55. Over the past month the share price return declined 15.2%, and the year-to-date share price return fell 33.2%, while the 1-year total shareholder return dropped 49.9%. This points to fading momentum despite this new contract win.
Scan beyond Parsons and see how other defense and infrastructure contractors with similar contract profiles line up in our hand picked 39 power grid technology and infrastructure stocks.
Bulls point to Parsons’ new Space Command role and its current discount to analyst targets. Bears focus on a sharp share price slide. With the numbers now on the table, which side does the valuation lean toward?
Most Popular Narrative: 29% Undervalued
Parsons is being framed as undervalued when its fair value of $58.55 is compared with the recent $41.55 close, and that gap is drawing attention to what drives the long term story rather than the recent share price slide.
Robust funding environment, demonstrated by a record funded backlog (up 14% YoY), strong free cash flow performance, and high win rates on large contracts, combine with secular infrastructure and security demand to underpin both near
and long-term earnings growth and margin stability, despite investor caution or perceived near-term volatility.
See why 13 investors see Parsons as 29% undervalued.
Result: Fair Value of $58.55 (UNDERVALUED)
Still, heavy reliance on U.S. federal funding and recent cuts to 2026 revenue and EBITDA guidance could weaken confidence in the Parsons narrative if these pressures persist.
Find out about the key risks to this Parsons narrative.
Another View: Parsons Through The Earnings Multiple Lens
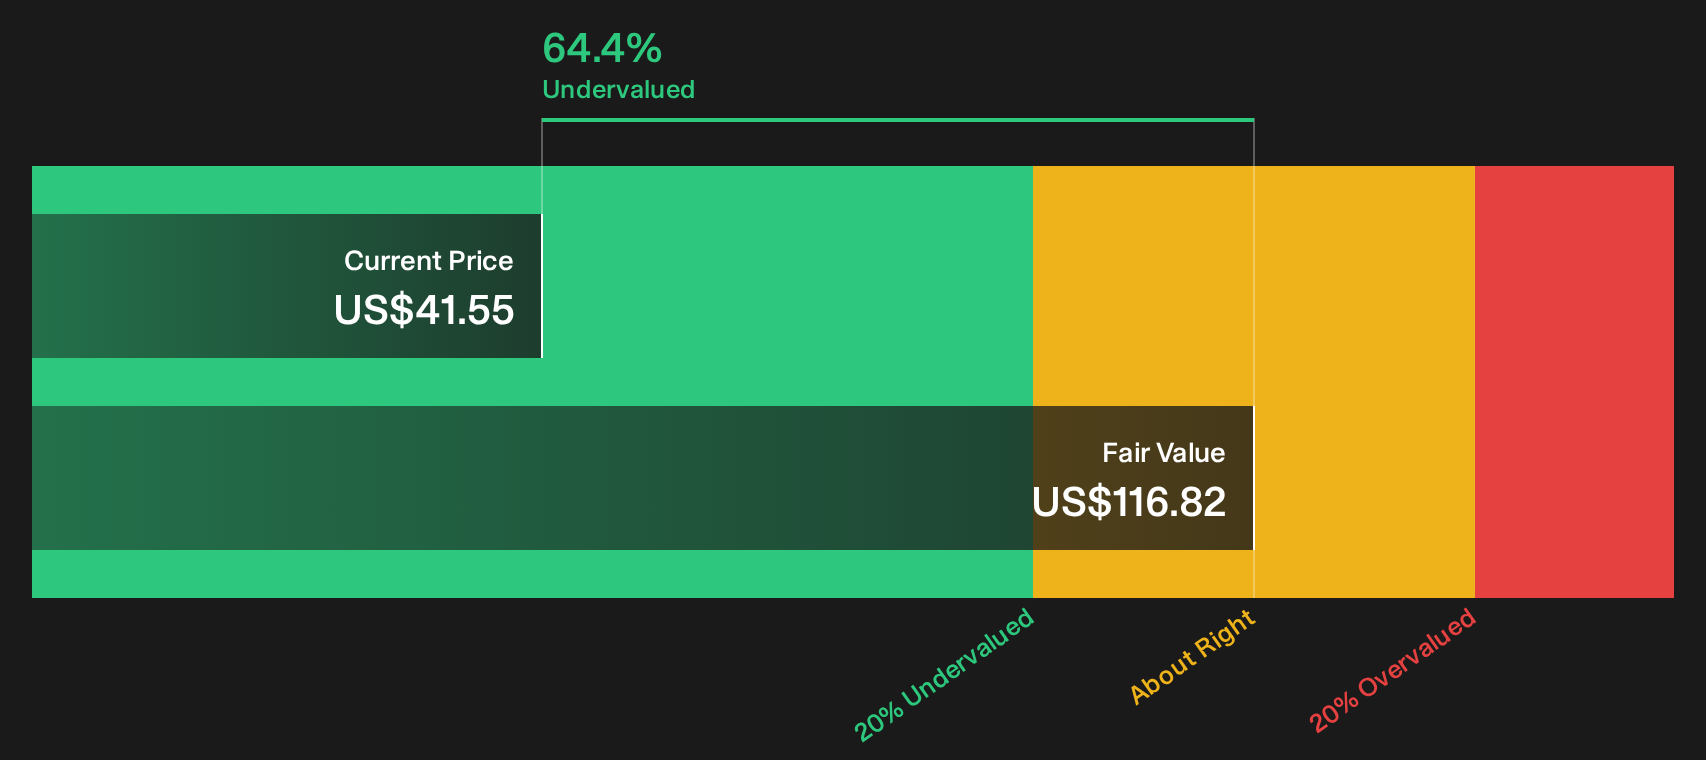
The SWS DCF model points to Parsons trading well below an estimated future cash flow value of $116.82, yet the earnings multiple tells a different story. The stock changes hands at a P/E of 28.2x, which is higher than the US Professional Services industry at 21x and above the peer group at 16.1x. That premium also sits under the 34.7x fair ratio, which is the level the P/E could move toward if the market reprices Parsons. For investors weighing valuation risk versus upside, which signal matters more right now: the discount to DCF or the rich earnings multiple?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Parsons are clear, with contract wins on one side and valuation questions on the other. Treat this as a prompt to review the data, stress test the risks, weigh the upside, and then rely on your own judgment by checking the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Parsons?
If Parsons has sharpened your thinking on valuation and risk, do not stop here. Use the screener to surface fresh ideas before the market does.
- Target financial resilience by sorting for companies with stronger balance sheets and fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Spot potential value opportunities early by filtering for businesses trading below assessed worth with the 32 high quality undervalued stocks.
- Zero in on under-the-radar prospects that still show quality fundamentals through the 17 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com