
How Higher Production Targets At First Majestic Silver (TSX:AG) Have Changed Its Investment Story
- First Majestic Silver raised its 2026 silver production target to 14.5–15.5 million ounces, outlined roughly $350 million of exploration-focused capital spending, and detailed plans to restart Jerritt Canyon in the second half of 2027 while tying its dividend to 2% of revenue.
- The miner plans to self-perform mining at Jerritt Canyon, rely on about $1.2–$1.3 billion of liquidity for projects and potential acquisitions, and continue using its Las Vegas mint to capture 15%–20% premiums on some silver sales.
- This article examines how First Majestic Silver's higher 2026 production target may reshape its investment narrative and long-term risk-reward profile.
Scan beyond First Majestic Silver and compare it with 10 top silver producer stocks, which could also be primed for big moves as sentiment shifts around production plans and metals pricing.
First Majestic Silver Investment Narrative Recap
To own First Majestic Silver, you need to buy into a story of higher silver output backed by heavy exploration and development spending. The raised 2026 production goal and the planned Jerritt Canyon restart keep that volume-first approach front and center. The key near term swing factor remains whether projects hit timelines and grades closely enough for that spending to support future throughput.
The biggest near term risk still sits on the cost and execution side. Nearly $350 million earmarked for exploration and drilling, plus new equipment for Jerritt Canyon, creates real pressure if silver prices soften or volumes underperform. The updated guidance does not fundamentally change that risk; it instead sharpens the focus on delivery.
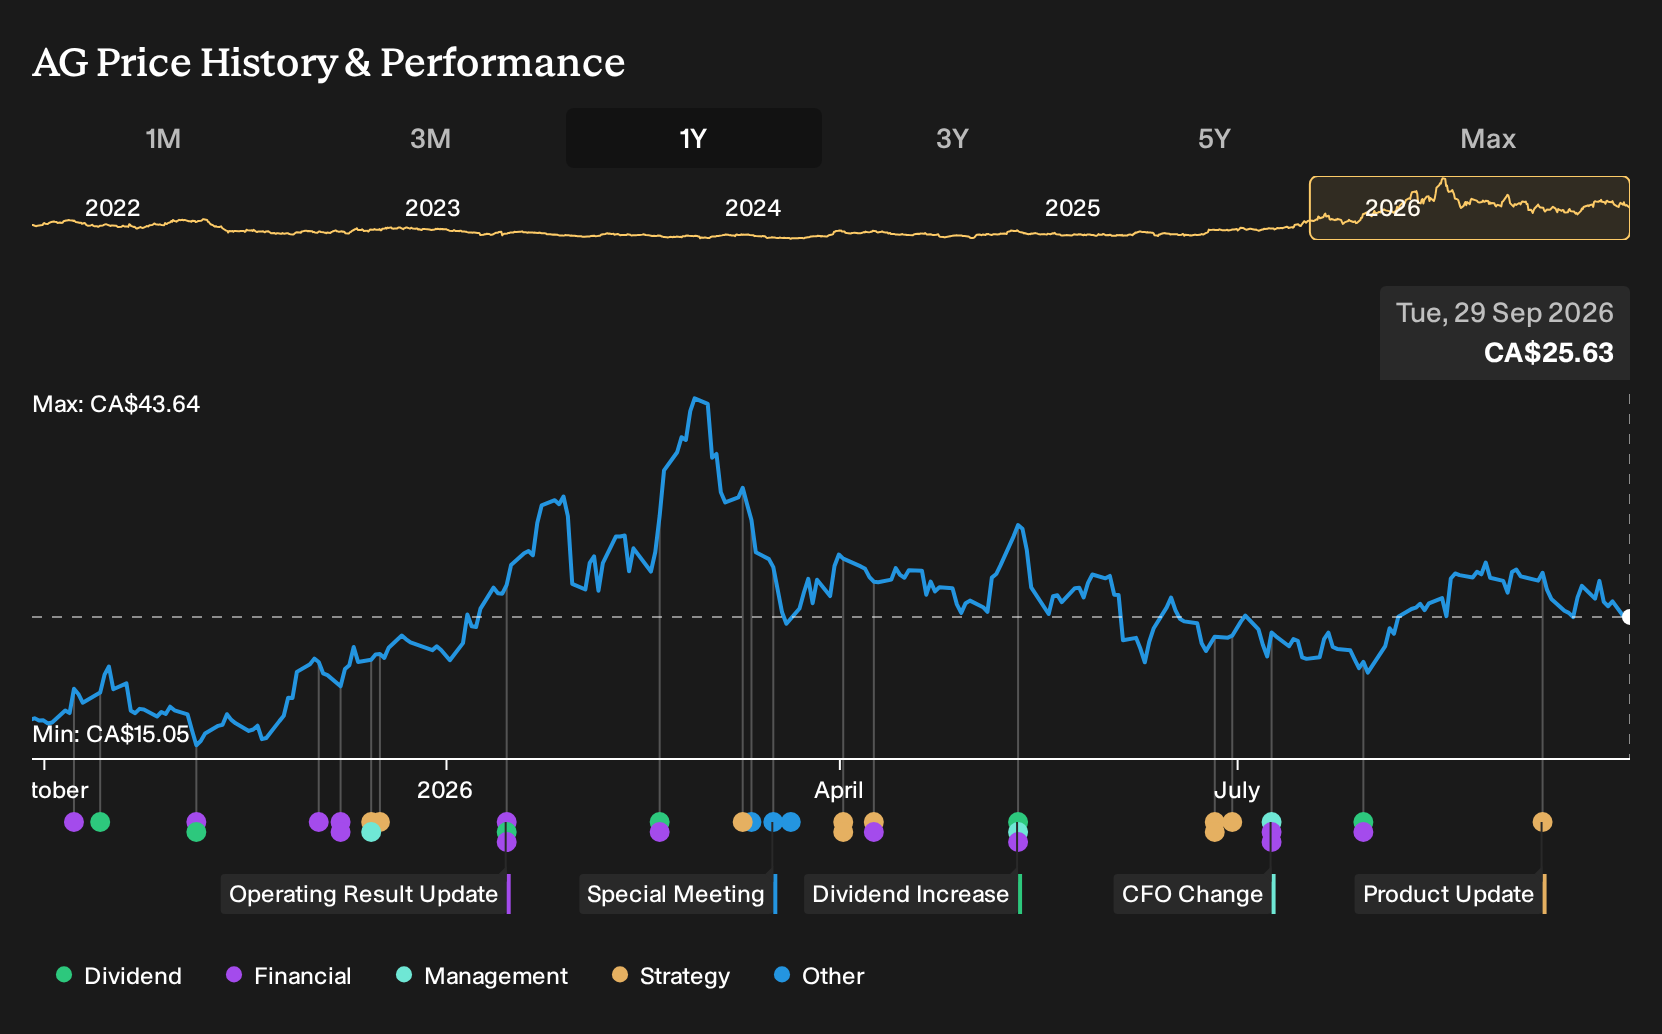
The company’s decision to tie its dividend to 2% of revenue is the announcement that most clearly interacts with this operating story. Payouts now move with sales, so higher production can translate into higher distributions while still preserving balance sheet capacity for exploration and mill upgrades.
For investors, that link between revenue and dividends turns volume growth into a more visible catalyst while also exposing payouts to swings in metals prices and production reliability. That trade off sits alongside options data that points to expectations of significant share price moves, which keeps execution on the 2026 production plan in the spotlight.
First Majestic Silver's current analyst narrative points to about $2.1b in revenue and $620.4 million in earnings by 2029, based on an assumed 8.7% yearly revenue growth rate. That road map implies earnings would need to rise by roughly $272.8 million from about $347.6 million today to hit the consensus forecast for 2029.
Uncover why First Majestic Silver's fair value indicates a 36% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view fixates on dilution risk rather than production growth. The most cautious analysts expected revenue of about $2.0b and earnings near $580.1 million by 2029, paired with a CA$30.0 target, and worried that more share issuance could blunt any upside. Those estimates all predate First Majestic Silver’s new production and capex plans, so you may want to compare them with your own expectations and decide how this fresh guidance could shift the story.
Explore 5 other First Majestic Silver fair value estimates, including one that suggests it could be worth just CA$30.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your First Majestic Silver research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Majestic Silver. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Majestic Silver's overall financial health at a glance.
Looking for more investment ideas beyond First Majestic Silver?
Once you have formed a view on First Majestic Silver, it often helps to compare it with a broader watchlist. The Simply Wall St Screener lets you filter for features that matter most to you, whether that is balance sheet strength, income potential, or under the radar growth stories.
- If capital preservation ranks high on your list, start with a group of 7 resilient stocks with low risk scores that score well on resilience and risk profile.
- If you want income to play a bigger role, focus on a curated set of 1 dividend fortresses that combine higher yields with underlying business strength.
- If you prefer to hunt for quieter opportunities, scan through a collection of 9 high quality undiscovered gems where fundamentals may not yet be fully reflected in market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com