
Strathcona Resources Holders Are Up 48% And The Market Never Agreed
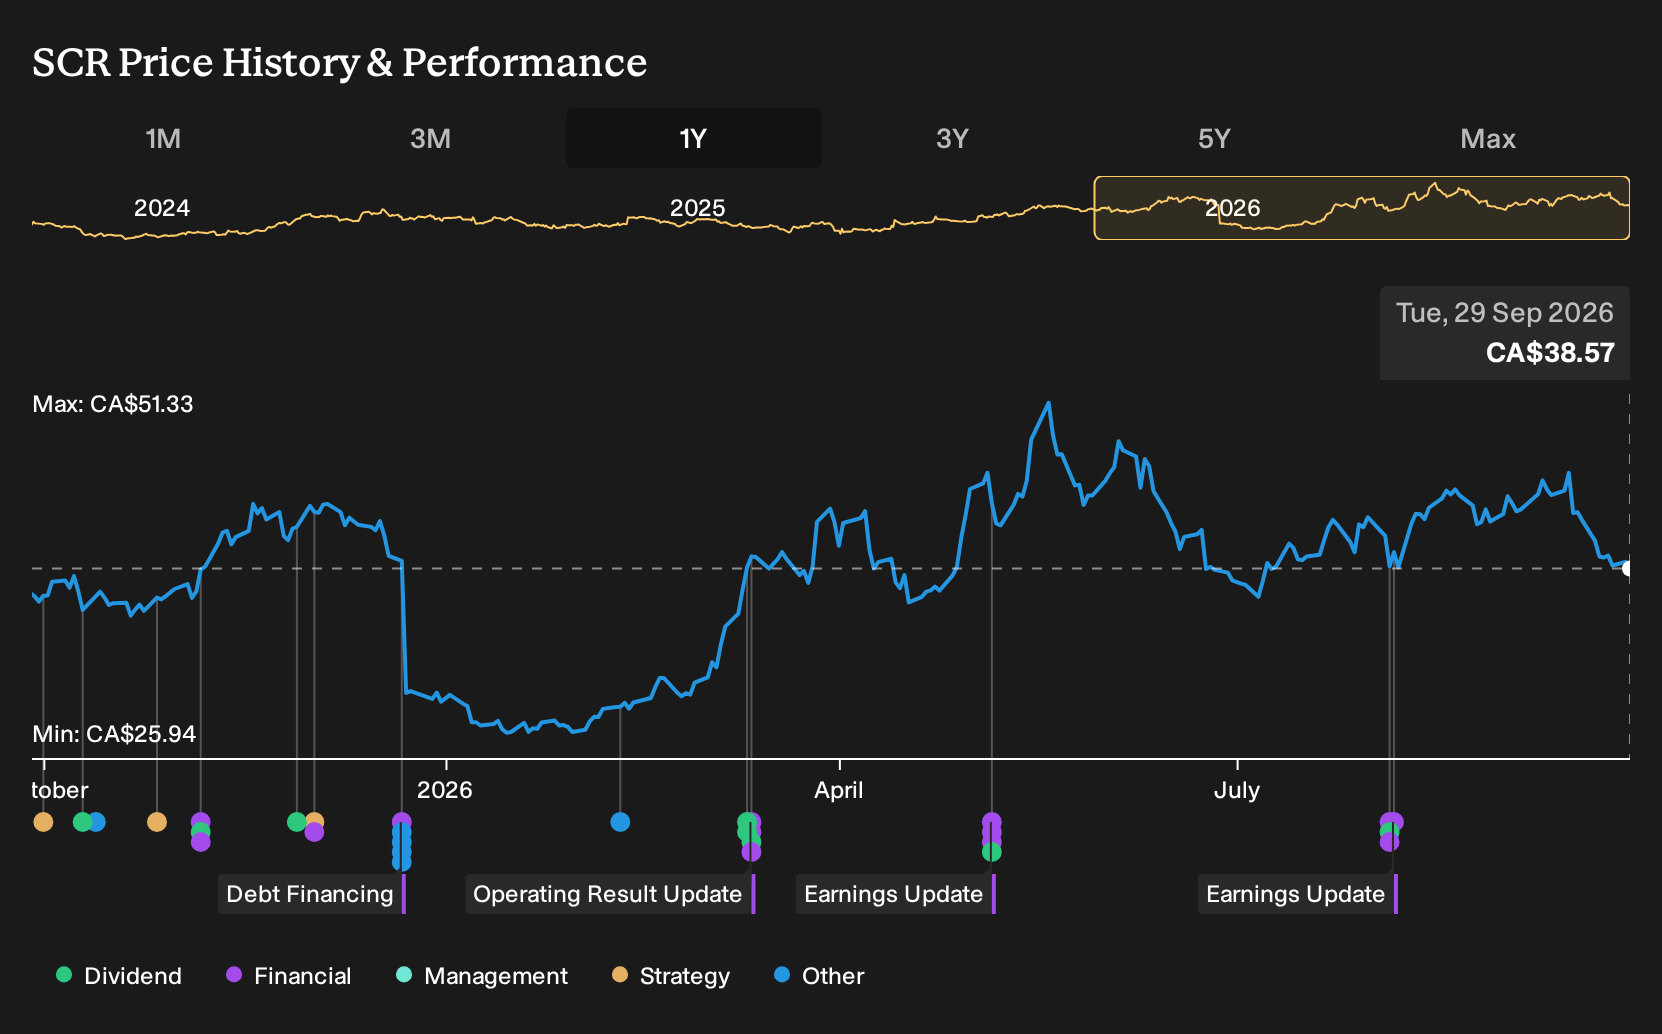
Investors who held Strathcona Resources over the past year are up 47.8%, including dividends. If you had been weighing a purchase on 29 September 2025, you were staring at two sharply different narratives built around the MEG Energy deal, heavy oil exposure, and carbon policy risk. Recent milestones like first steam at Meota Central now frame that choice in a new light. Which parts of the original record really mattered for that call?
If the move has made Strathcona Resources harder to judge, start where the gap is still open and scan 6 high quality undervalued stocks.
The Argument You Would Have Weighed On Strathcona Resources
The shares cost CA$36.43 at the start of the period, and anyone looking at Strathcona Resources then had to choose between two sharply different but credible stories.
The bullish view put Fair Value at CA$41, a price those assumptions implied for the stock. This view was built on MEG merger scale potentially delivering industry leading costs, while still accepting analyst expectations for revenue to decline 0.8% a year and margins to shrink from 14.4% to 2.4% by 2028.
The bearish narrative saw Fair Value at CA$34 and focused on concentration in heavy oil and oil sands, with decarbonization pressure and an assumed 14.2% annual revenue decline cutting into earnings resilience.
What The Results Changed For Strathcona Resources
First steam at Meota Central, achieved ahead of schedule with construction completed safely, directly spoke to the bullish Strathcona Resources case that leaned on MEG scale and heavy oil execution. Q2 2026 results added weight, with revenue at CA$1,345m and net income excluding extra items at CA$333m, while net margin rose to 24.8%. The evidence cut both ways but leaned optimistic.
The real hinge here was whether bigger thermal projects would turn into higher and cleaner profitability. For a different stock in a similar position, test that same claim against post project margins and the share of earnings coming from one commodity or asset type.
What Strathcona Resources' Price Already Assumes
Strathcona Resources now trades at CA$38.57, with this narrative arguing that fair value sits above that mark. The gap rests on a mix of heavy oil exposure, rail logistics and carbon capture spend that, together, are claimed to support resilience.
Anyone paying today is effectively judging whether sizable organic production growth can be delivered without carbon and acquisition risks eroding that thesis.
"Strong organic growth, operational efficiencies, and carbon capture investments position Strathcona for enhanced resilience, ESG appeal, and improved margins, even amid acquisition uncertainty."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Where Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 38% below our estimate - accelerates higher grade ore feed across several mines to raise volumes and lower costs.
- Company 2 - 30% below our estimate - pushes plant throughput targets above initial expansion plans while pursuing new high grade discoveries.
- Company 3 - 33% below our estimate - ramps advanced networking and AI hardware programs for large cloud customers seeking higher bandwidth.
Three companies from the same screener. Open the full list of 7 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com