
How Six New Hotel Openings Will Impact Choice Hotels International Stock
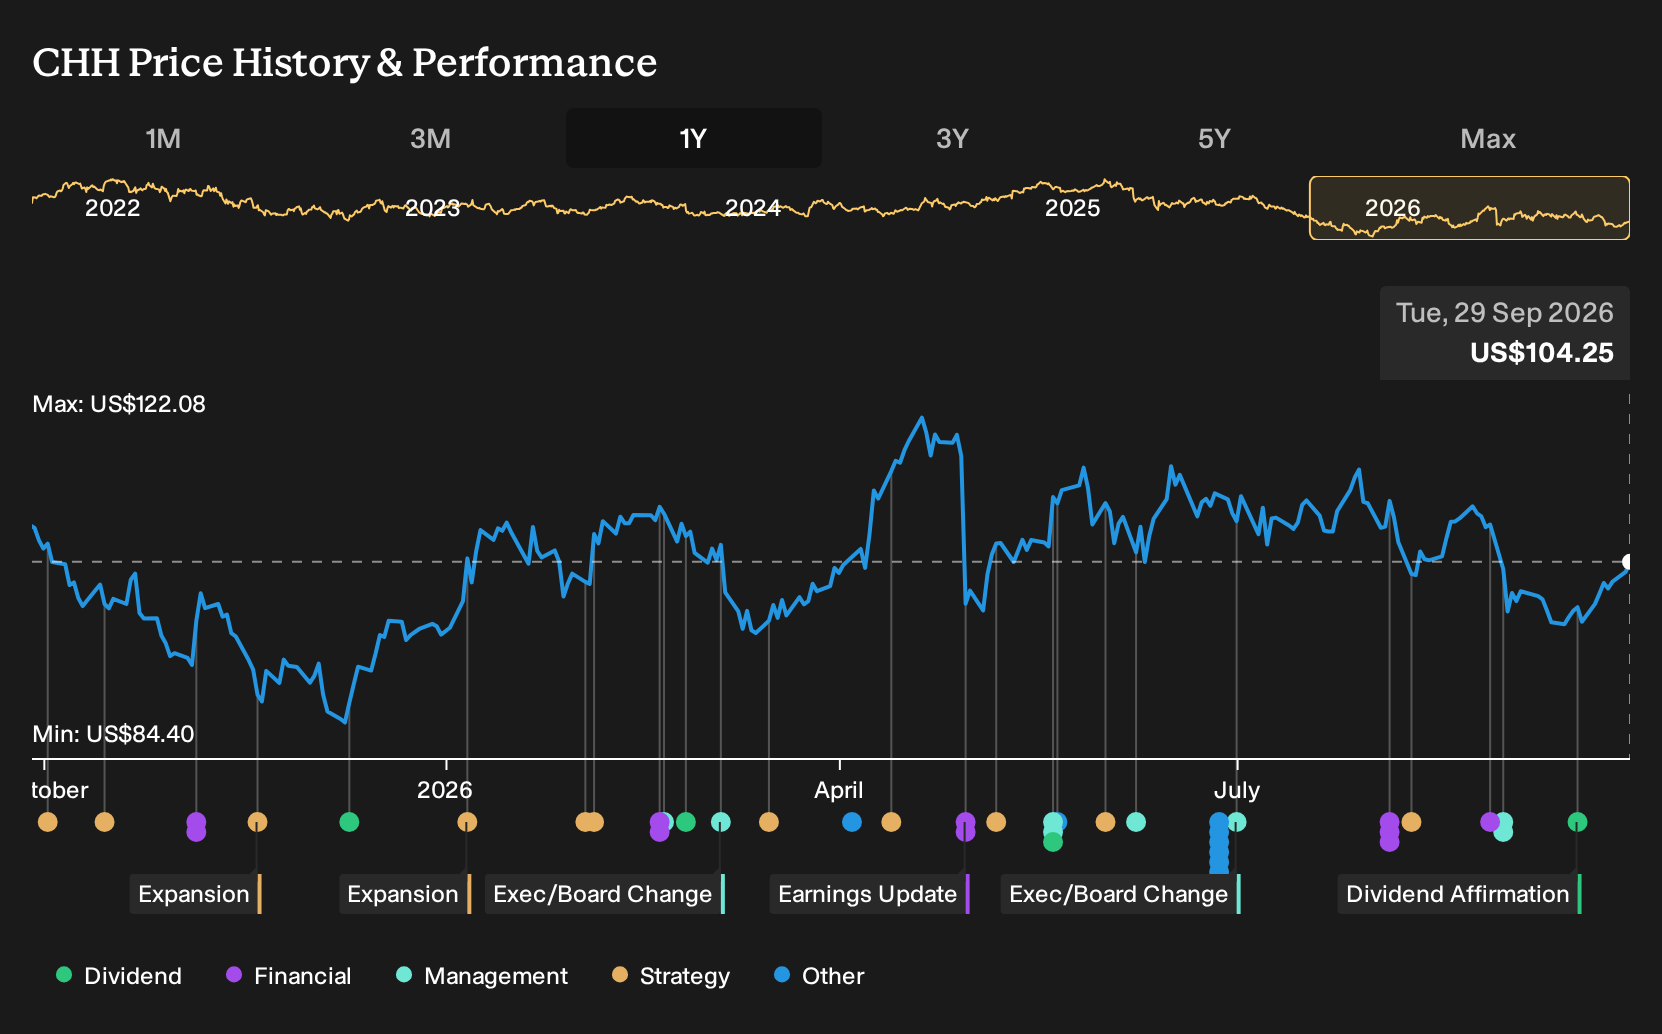
- Choice Hotels International has recently opened six upscale properties across its Cambria Hotels and Ascend Collection brands, adding new rooms and amenities in Colorado, Florida, Wisconsin, and Vermont, and expanding its presence in leisure, medical, and event driven travel corridors.
- The Sarasota twin Ascend properties and the large meeting focused Fairway Inn and Suites highlight a push toward higher fee potential stays that blend resort style leisure, wellness, and group demand within Choice Hotels International's franchise model.
- We will now look at how Choice Hotels International's upscale expansion, including the twin Sarasota Ascend hotels, interacts with the existing investment narrative.
Scan how Choice Hotels International's upscale push compares with peers by reviewing a hand picked set of resilient lodging and travel operators in our 32 resilient stocks with low risk scores.
Choice Hotels International Investment Narrative Recap
To own Choice Hotels International, you need to believe its asset light franchise model can keep converting room growth and brand mix upgrades into durable fee streams, even when travel demand is uneven. The latest upscale openings look incremental for now. They support the push toward higher royalty potential but do not obviously change near term earnings drivers.
The short term swing factor still looks like RevPAR pressure in softer government and inbound international segments, especially after prior guidance cuts. Upscale expansion helps diversify but does not remove that risk. Execution missteps on pruning weaker hotels, plus balance sheet sensitivity where debt is not well covered by operating cash flow, remain central watchpoints.
The fresh dividend affirmation of US$0.2875 per share ties directly into this story. Management is signaling confidence in ongoing cash generation despite softer recent RevPAR trends and the capital commitments that come with expanding Cambria and Ascend. For income focused holders, that decision matters more than any single hotel opening.
For growth oriented investors, the payout sits alongside the upscale footprint build out as a test of discipline. Upscale additions can support higher fee intensity if guest demand holds, but they also raise the bar on execution while leverage stays elevated. The regular dividend limits flexibility if credit losses on franchisee loans or weaker travel demand start to affect margins or free cash flow.
Choice Hotels International's current analyst narrative points to revenues of US$1.8b and earnings of US$393.9m by 2029, based on a forecast revenue growth rate of 21.6% a year and an earnings increase of about US$49.8m from US$344.1m today.
Uncover why Choice Hotels International's fair value points to an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts Choice Hotels International’s upscale push at the center of a much more optimistic story. The most bullish analysts were already modeling about US$1.9b of revenue and US$392.0m of earnings by 2029. You can see how this new batch of higher fee potential hotels might nudge those expectations, or challenge them, by comparing different forecast paths.
Explore another Choice Hotels International fair value estimate, including one that suggests potential upside of as much as 139% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Choice Hotels International research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Choice Hotels International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Choice Hotels International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Choice Hotels International?
If the Choice Hotels International story has sharpened your thinking, use that momentum to scan a wider field of opportunities using the Simply Wall St Screener. You can filter for balance sheet strength, income potential, or value focused setups in a few clicks and build a watchlist that genuinely fits your own risk tolerance.
- If resilience matters most to you, start with a curated 32 resilient stocks with low risk scores that aims to keep downside risk in check.
- If you are hunting for companies that appear mispriced, filter for value led opportunities across our 32 high quality undervalued stocks and see which ones deserve a closer look.
- If reliable income is a priority, focus on yield heavy candidates by scanning the 6 dividend fortresses that combine higher payouts with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com