
Is Target Hospitality (TH) Still Undervalued On Its AI Infrastructure Growth Story?
Target Hospitality (TH) has drawn renewed attention after its recent share performance, with the stock up over the past month but down over the past 3 months, prompting closer scrutiny of its fundamentals.
For context, Target Hospitality’s share price has delivered a very strong year to date return of 138.02%. The 1 year total shareholder return of 127.36% and 5 year total shareholder return of 379.60% point to a powerful longer term rerating, even as the recent 7 day share price return fell 9.01%. This suggests momentum has cooled in the short term and investors are reassessing how much growth and risk they are willing to price in at around $19.28 per share.
Compare Target Hospitality’s sharp rerating with a curated shortlist of other companies showing strong fundamentals and fresh momentum in our 17 high quality undiscovered gems.
Target Hospitality has already delivered triple digit returns over the past year. However, the recent pullback and current price near $19.28 raise a different debate: Is meaningful upside still ahead, or was most of it already captured?
Most Popular Narrative: 20% Undervalued
On the most followed view of Target Hospitality, a fair value of $24 sits well above the recent $19.28 close, which puts a bright spotlight on whether the contract driven growth story holds up under closer inspection.
Expansion into rapidly growing, high-demand sectors such as data centers and AI infrastructure, supported by over $1.2 trillion in domestic capital commitments and multi-year build cycles, positions Target Hospitality for long-term recurring revenues with higher margin, asset-owning contracts, which may underpin sustained revenue and EBITDA growth.
See why 2 investors see Target Hospitality as 20% undervalued.
Result: Fair Value of $24 (UNDERVALUED)
Still, the bullish Target Hospitality narrative runs into real friction if hyperscaler and AI infrastructure demand cools, or if government related contracts slow or get reprioritized.
Find out about the key risks to this Target Hospitality narrative.
Another View On Target Hospitality’s Valuation
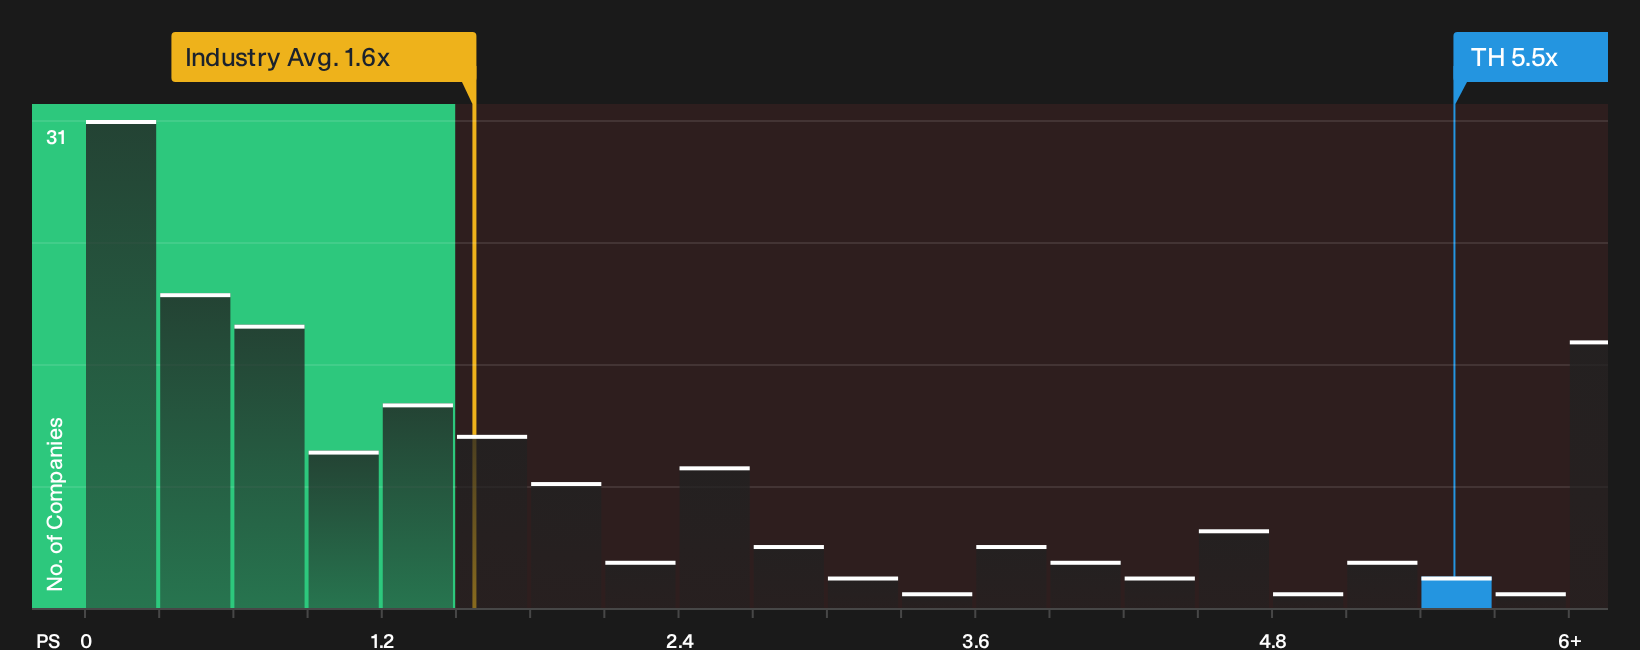
On a simple sales multiple, Target Hospitality looks rich. The P/S ratio sits at 5.5x compared with 1.6x for the wider US Hospitality group and 1.3x for close peers, while the fair ratio is estimated at 4x. That gap points to real valuation risk if sentiment cools or growth assumptions soften.
Numbers can still justify a premium, but only if you think the story ahead is strong enough to keep that higher multiple in place. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Target Hospitality is split enough that it pays to move quickly, check the underlying metrics yourself, and pressure test every assumption. To see what investors are optimistic about in the data, start with the 3 key rewards.
Looking for more Target Hospitality style ideas?
If you are serious about sharpening your watchlist beyond Target Hospitality, do not stop here. The right screen could surface your next big winner.
- Target resilient compounding by scanning a 32 resilient stocks with low risk scores that filters for businesses with steadier risk profiles and fewer balance sheet red flags.
- Hunt for mispriced quality through a 32 high quality undervalued stocks that focuses on financially strong companies trading below their estimated worth.
- Build a sturdier income stream by shortlisting reliable payers using a 6 dividend fortresses that highlights higher yielding opportunities with supportable payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com