
3 Dividend Stocks With Yields Over 5%
Bond yields have surged to their highest levels in decades, which means income investors now see plenty of competition from cash and government paper. Yet some of the most resilient dividend payers still offer yields above 5% and a record of keeping payouts coming through thick and thin. This article walks through three such stocks and explains why they may deserve a place on a long term income watchlist.
The stocks covered below are only a small sample. The full screen surfaces 157 more Dividend Aristocrats that carry 5%+ yields and long payout histories that are not included here but may warrant a closer look.
If you want to identify which of these income plays best fits your portfolio goals, head straight to the Dividend Aristocrats screener to filter and analyze the full set of opportunities.
CNOOC (SEHK:883)
CNOOC is a Hong Kong based oil and gas producer whose appeal for income investors starts with steady offshore fields that can support sizeable cash payouts. Most of its CN¥378.3b revenue in 2025 came from exploration and production, with CN¥54.2b from trading, and the stock carries a market value around HK$1.17t.
CNOOC gives this Dividend Aristocrats screen some heavy lifting power, because a large offshore production base in the Bohai Sea and South China Sea helps underpin the kind of recurring cash flows needed for high, regular dividends.
"CNOOC's record pace in bringing large new projects online, particularly in high-potential regions like Brazil and the South China Sea, imply reserves and production may see compounding annual growth at rates the market has not yet priced in, providing significant long-term upside to revenue and cash flow."
What happens if one unseen pressure on those cash flows shifts direction is what could really move margins and future payout capacity.
If that pressure flips, the full implications sit inside the full narrative for CNOOC, where the interplay between new projects, costs and dividend capacity really comes into focus.

DHT Holdings (DHT)
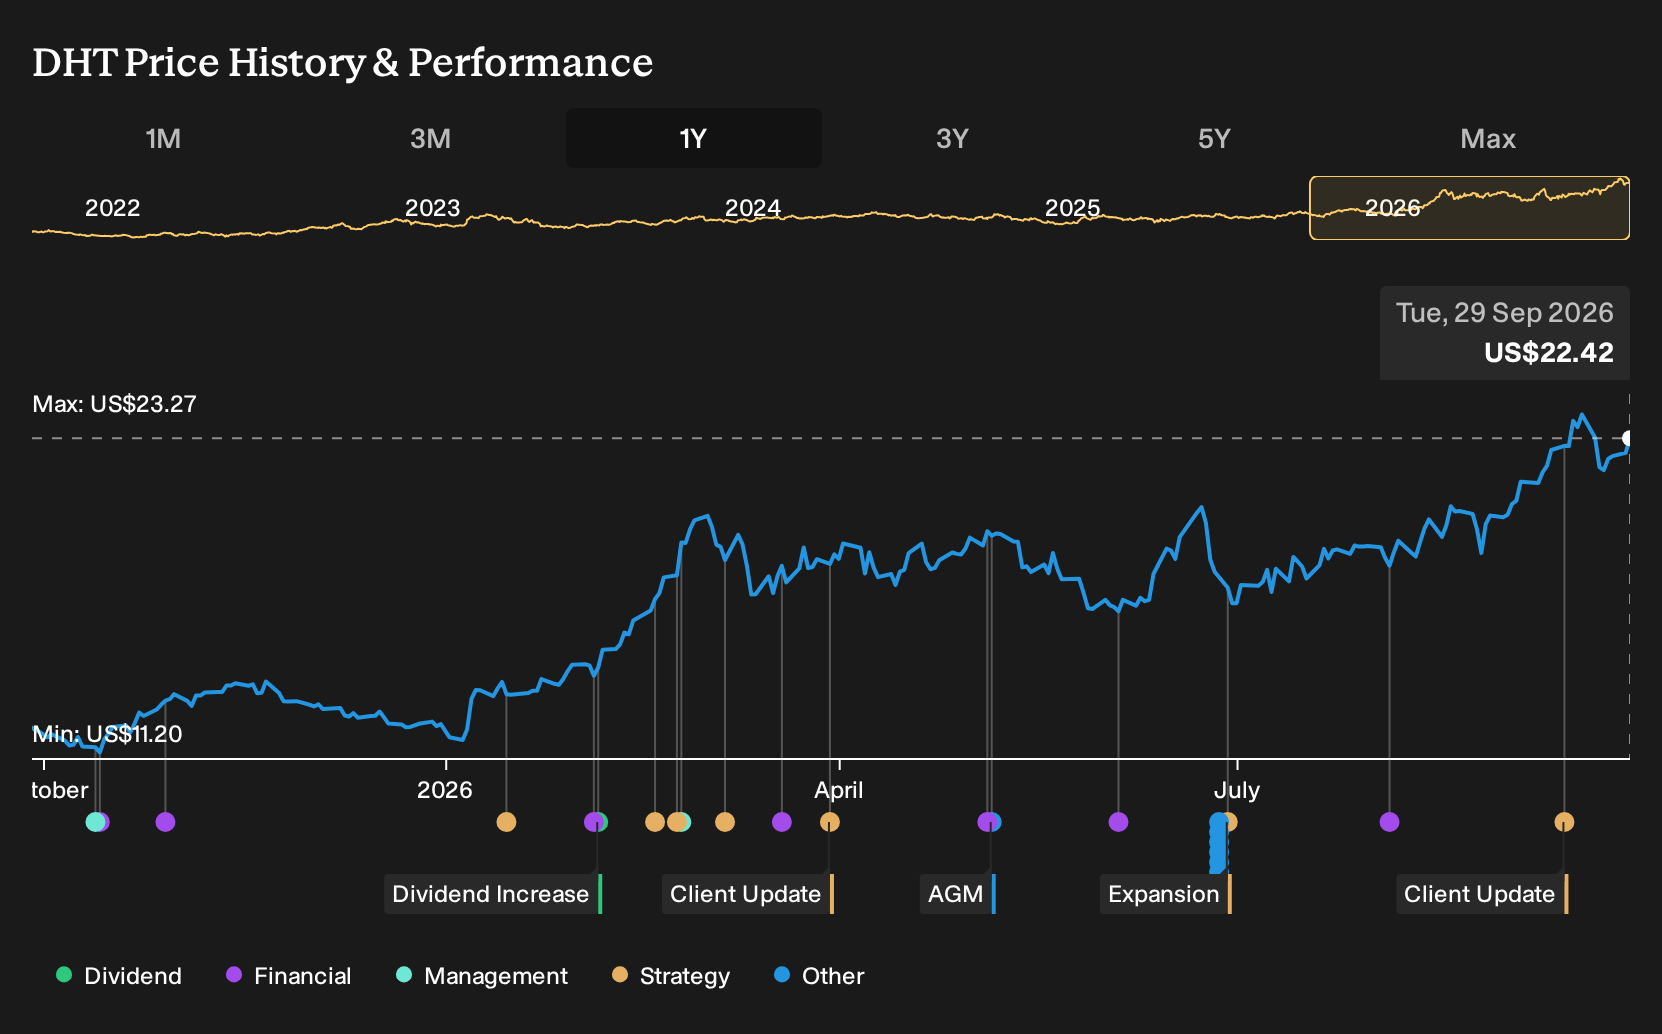
DHT Holdings runs a fleet of very large crude carriers that ship oil worldwide, tying its appeal for income investors to charter-driven cash flows that can underpin high dividend yields.
DHT Holdings operates 22 crude oil tankers that generated about US$799 million from its fleet in the latest year, and with a market value around US$3.5b it is a mid cap shipping player firmly linked to the high yield Dividend Aristocrats theme.
"The escalation of US-Israel strikes on Iran, including the assasination of Iran's Supreme Leader, Khamenei, has triggered Iranian retaliation which include effective disruptions or closures in the Strait of Hormuz that serves as a vital chokepoint for global oil trade."
What happens if one unresolved shift in freight economics lingers longer than traders currently expect is what really matters for future payouts.
If that shift in freight economics persists, the full narrative for DHT Holdings shows how DHT Holdings’ payout story could decouple from spot-rate swings and explains why income potential might still be building.
Intesa Sanpaolo (BIT:ISP)
Intesa Sanpaolo is a Turin based banking group that leans on its Italian retail and SME franchise for the kind of recurring net interest income that can help support high dividends. The Territorial Bank unit brings in about €10.9b of revenue, ahead of IMI Corporate & Investment Banking on €5.0b and International Banks on €3.2b, within a wider mix that includes private banking, asset management and insurance. Overall, the group generates about €20.2b from Italy and carries a market value of roughly €117.3b.
For income focused investors, Intesa Sanpaolo offers a different type of Dividend Aristocrat, built on a large deposit base and everyday banking relationships that can underpin regular payouts across economic cycles rather than one off windfalls.
"Continued investment in digital transformation, including cloud migration, AI, and technology platforms, should lead to further operational cost reductions and improved customer reach, supporting higher net margins and long-term bottom-line growth."
What happens if one unseen pressure on credit quality and capital requirements shifts direction is what could really shape future dividend headroom.
If that pressure builds or eases faster than expected, the full narrative for Intesa Sanpaolo explains how Intesa Sanpaolo's dividend story could be quietly accelerating beneath the surface.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities can move from quiet accumulation to full breakout fast. Identify momentum while it still slips under the radar. Avoid reacting late by preparing in advance.
- Spot potential breakouts early by scanning a curated mix of fast moving miners and producers through the 36 elite gold producer stocks before momentum is fully reflected in prices.
- Follow new infrastructure themes by tracking hand picked grid, hardware and software players using the 39 power grid technology and infrastructure stocks while capital is still rotating into them.
- Explore compounding potential by reviewing a filtered group of automation leaders inside the 93 robotics and automation stocks before their metrics attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com