
Sigma Lithium (SGML) Counters License Concerns, Is It A Bargain?
Sigma Lithium (SGML) has moved back into focus after its leadership used UN Climate Week in New York to highlight its "Quintuple Zero" production model and publicly counter reports about suspended environmental licenses.
Recent trading tells a complicated story for Sigma Lithium. The share price closed at US$9.71 on the latest trading day and has risen 2.21% on a 1-day share price return, yet the 30-day share price return is down 20.80% and the year-to-date share price return is down 31.67%. At the same time, the 1-year total shareholder return of 51.48% contrasts with a 3-year total shareholder return that has declined 67.27%. This suggests earlier enthusiasm has cooled and recent news around licenses and sustainability is now being weighed against longer running questions about risk and execution.
Scan beyond Sigma Lithium and compare it with a hand picked 35 best rare earth metal stocks that are also tied to critical battery metals and sustainability headlines.
Bulls point to Sigma Lithium’s green credentials and analyst optimism, while bears focus on share price losses and continued net losses. Which story do the current valuation multiples and cash flows support?
Most Popular Narrative: 31% Undervalued
The most followed narrative on Sigma Lithium pegs fair value at $14.00 per share, versus the latest close at $9.71. That gap rests on some punchy assumptions about future scale, profitability and how much risk the market is willing to price in today.
While management presents decades long growth in lithium demand from battery storage and AI driven data centers, any future slowdown or delay in large scale storage build outs could leave the company with 580,000 to 830,000 tons of installed capacity that is underutilized, which would limit revenue growth and dilute returns on recent and upcoming CapEx.
See why 2 investors see Sigma Lithium as 31% undervalued.
That storyline leans on a discount rate of 9.21% and assumes Sigma Lithium can move from a current net loss of $27.6 million to earnings of $406.6 million by about 2029, while lifting profit margin from a loss making position to 42.9%. It also assumes revenue reaches $948.8 million and that the stock would then trade on a P/E of 5.2x, which is far below the current 20.8x P/E level cited for the wider US Metals and Mining sector in the narrative.
Analysts behind this view cluster around a price target range of $14.00 to $20.00, with the $14.00 mark presented as the more cautious end of that spectrum. The fair value story effectively asks investors to decide whether such aggressive earnings and margin shifts, combined with a relatively low future P/E, are realistic for a miner that is still unprofitable and exposed to regulatory and cost risks highlighted during recent negotiations in Minas Gerais.
Result: Fair Value of $14.00 (UNDERVALUED)
Still, Sigma Lithium’s reliance on concentrated offtake prepayments and on regulatory negotiations in Minas Gerais means any contract setback or license disruption could quickly challenge that 31% undervalued story.
Find out about the key risks to this Sigma Lithium narrative.
Another View on Sigma Lithium’s Valuation
The discounted cash flow work inside the Simply Wall St report points a very different way. On that model, Sigma Lithium’s share price of $9.71 sits above an estimated future cash flow value of about $5, which screens as overvalued and puts more weight on execution risk than on analyst targets.
The SWS DCF model forces you to ask a blunt question. Are the ambitious earnings and margin forecasts realistic enough to justify paying nearly double that cash flow estimate, or are analysts anchoring on a best case script that leaves little room for setbacks in Brazil or lithium demand?
Look into how the SWS DCF model arrives at its fair value.
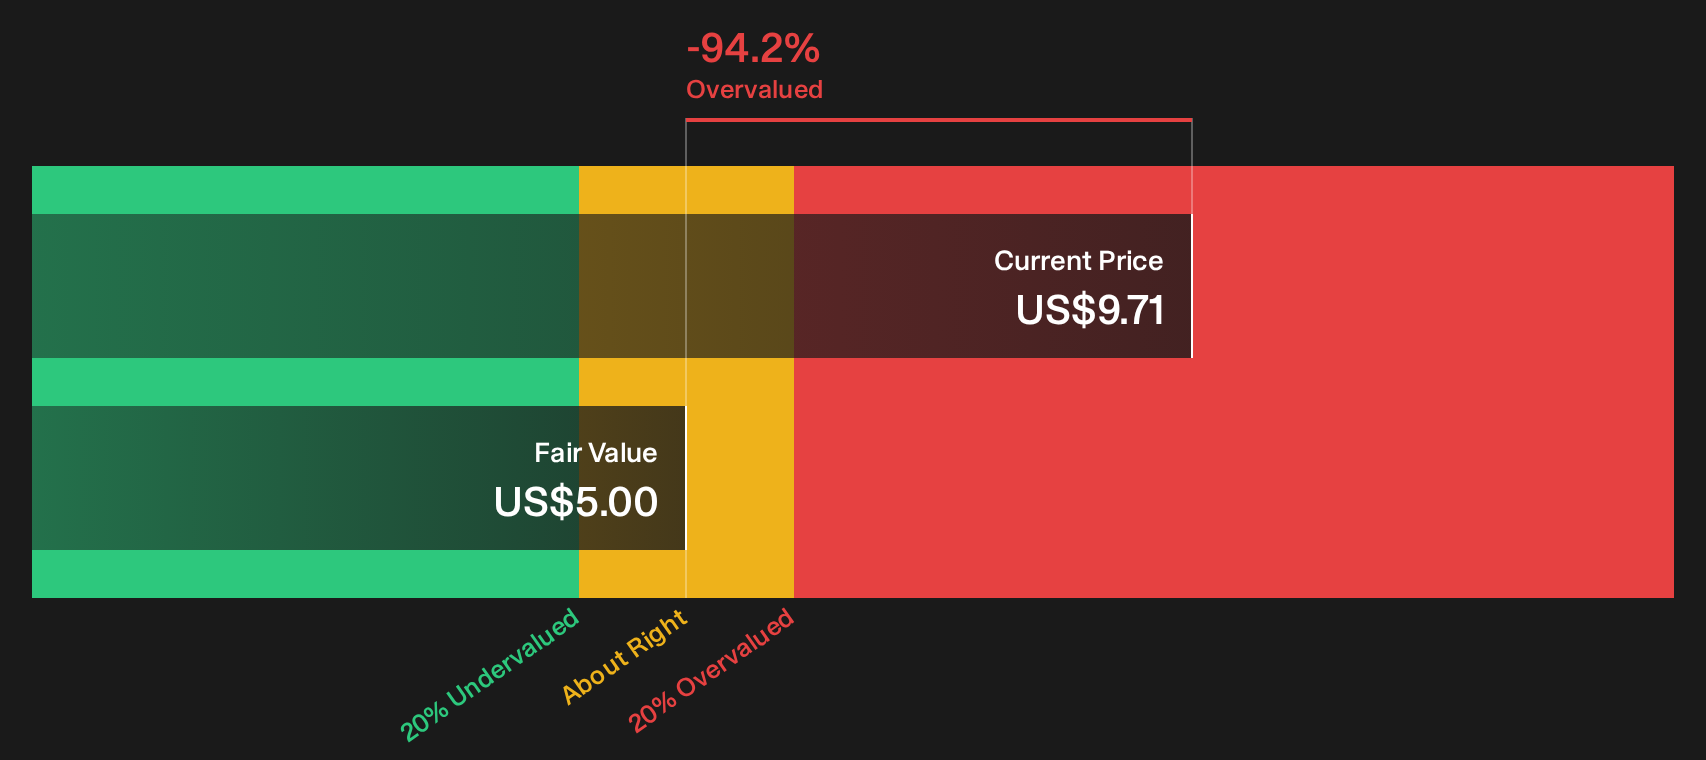
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sigma Lithium for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Sigma Lithium’s value and risk profile make this a moment to move fast and test the numbers for yourself. Start by weighing the 2 key rewards and 1 important warning sign using the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Sigma Lithium?
Do not stop your research with Sigma Lithium when the wider market is full of other opportunities that may fit your goals just as well.
- Target potential mispricing by reviewing a 32 high quality undervalued stocks that filters for quality fundamentals and solid cash generation.
- Strengthen your income stream by scanning a 6 dividend fortresses focused on companies that combine higher yields with robust payout histories.
- Protect your downside by checking a 32 resilient stocks with low risk scores that highlights businesses with more resilient financial profiles and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com