
Production Expansion Plan Might Change The Case For Investing In Alamos Gold Stock (TSX:AGI)
- Alamos Gold has outlined a plan to roughly double annual gold output to about 1 million ounces by 2030, anchored by the Island Gold expansion in Ontario and the Lynn Lake development in Manitoba, with management highlighting that key projects are already permitted and funded.
- The focus on organic production growth rather than acquisitions points to an execution heavy path, where timely delivery of Island Gold and Lynn Lake could materially reshape Alamos Gold's cost profile, mine life mix, and exposure to regional operating risks.
- This article explores how Alamos Gold's investment narrative may evolve as management targets 1 million ounces through the Island Gold expansion roadmap.
Scan beyond Alamos Gold and size up other producers on a similar trajectory with the hand picked 36 elite gold producer stocks that could reshape your precious metals exposure.
Alamos Gold Investment Narrative Recap
To own Alamos Gold, you need to be comfortable with a production story that leans heavily on getting Island Gold and Lynn Lake built and ramped as planned. The recent goal to reach about 1 million ounces by 2030 reinforces that this is an execution story. The near term swing factor is how smoothly the Island Gold expansion and Magino integration progress.
The main risk right now sits on the cost and timing side. Alamos Gold has lifted its full year all in sustaining cost guidance by 12%, with a chunk tied to royalties and share based pay. If inflation, environmental disruptions, or project hiccups linger, margins and free cash flow could feel pressure despite the growth path.
The most relevant update is management flagging that the Island Gold expansion and Lynn Lake development are already permitted and funded as part of the 1 million ounce roadmap. That matters for you because it frames growth as an internal build out rather than a future acquisition story with unknown terms.
Fully funded projects reduce financing uncertainty, but they do not remove construction and ramp up risk. Your focus probably shifts to execution checkpoints at Island Gold, how quickly the Magino mill can absorb higher grade ore, and whether AISC trends stabilise as these assets move from capital heavy builds to more mature producers within Alamos Gold.
Alamos Gold is currently framed around analyst expectations for about $3.8b in revenue and $1.9b in earnings by 2029. These expectations are built on assumed yearly revenue growth of 19.8% and an earnings increase of roughly $700m from about $1.2b today.
Uncover why Alamos Gold's fair value indicates a 40% potential upside to its current price that could close sooner than many expect.
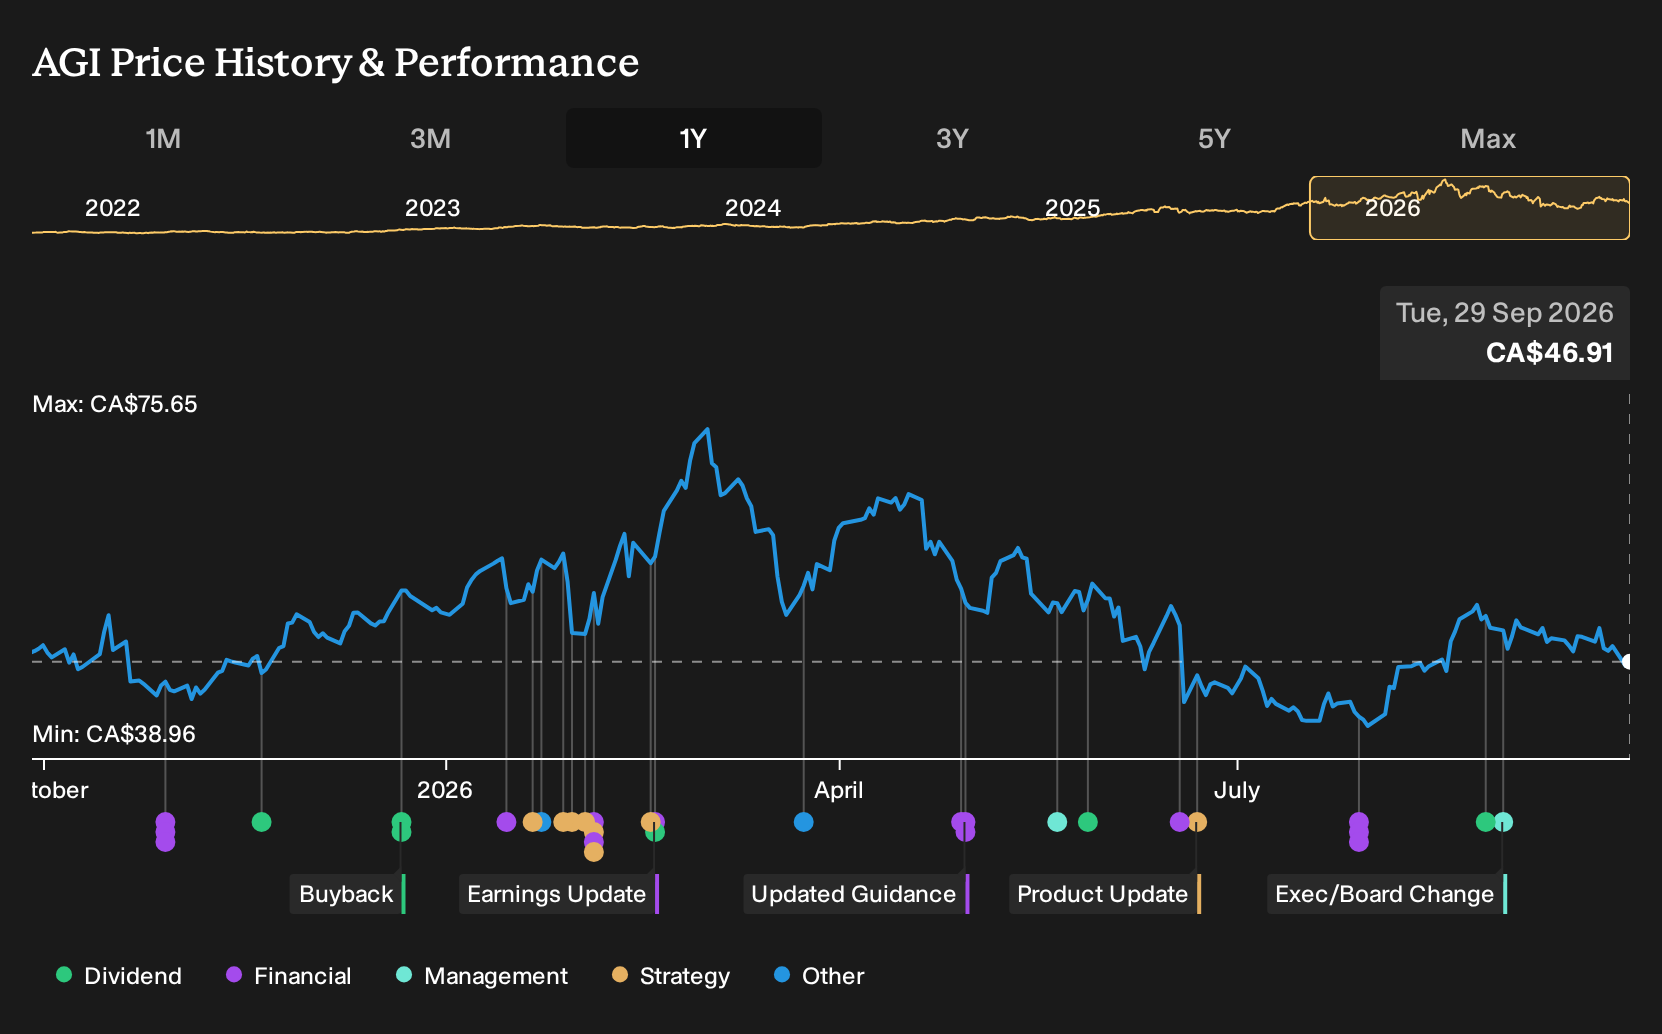
Exploring Other Perspectives
One alternate view on Alamos Gold leans hard into cost pressure risk. The most cautious analysts were pencilling in revenue of about $3.4b and earnings of $1.6b by 2029, rather than $3.8b and $1.9b. That is a much more conservative script. Use it as a reminder that expectations differ widely and may shift after this news.
Explore 4 other Alamos Gold fair value estimates, including one that suggests it could be worth just CA$65.84!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alamos Gold research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alamos Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alamos Gold's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alamos Gold?
If Alamos Gold has sharpened your interest in precious metals and quality balance sheets, the Simply Wall St screener can help you cast a wider net across the market without losing that focus on fundamentals.
- For investors who want resilience first and upside second, consider starting with a basket of 7 resilient stocks with low risk scores that may better match a cautious temperament.
- If strong finances matter more to you than headline growth stories, filter the market using a list of solid balance sheet and fundamentals (7 results) to keep the focus on durable business quality.
- When you want to widen your watchlist beyond well known tickers, scan through a 9 high quality undiscovered gems that could offer differentiated exposure alongside Alamos Gold.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com