
Will Phase 1 ADHD Data Change Alkermes Stock Narrative
- Alkermes reported past phase 1 proof of concept data for ALKS 7290 in ADHD, showing the orexin 2 receptor agonist was generally well tolerated in healthy volunteers and adults with ADHD, with clinically meaningful symptom improvements on AISRS and CGI S scales over 14 days and no serious treatment emergent adverse events.
- The results provide the first clinical evidence for an orexin agonist approach in ADHD, which could broaden Alkermes' neuroscience pipeline focus beyond current commercial products and inform dose selection and design choices for the ongoing phase 2 program.
- Next, we examine how Alkermes' broader investment narrative is affected by early ALKS 7290 efficacy signals and tolerability data.
Alkermes Investment Narrative Recap
To own Alkermes, you need to believe its core neuroscience portfolio can keep doing the heavy lifting while the orexin pipeline, including ALKS 7290, gradually turns into a meaningful second act. The topline phase 1 ADHD data helps from a narrative angle but does not change the near term focus on execution in Vivitrol, Aristada and Lybalvi, or the effort to reduce reliance on one off gross to net benefits.
The most important short term catalyst remains clearer visibility on orexin agonist progress in later stage trials and how R&D spend flows through to margins. The biggest risk is that rising development costs for orexin programs do not translate into registrational success or commercial products, which would leave Alkermes more exposed to product concentration and normalizing profitability.
The ALKS 7290 ADHD readout sits alongside a quieter but relevant development: the appointment of Anne C. Whitaker to the Alkermes board. Her background in commercial and operational roles across multiple biopharma companies points to a board that is adding experience in launching and scaling therapies, which matters if the orexin portfolio advances.
For you as a shareholder, this board change ties directly into the execution question around upcoming catalysts. Strong orexin data still needs disciplined investment decisions, payer ready positioning and cost control in a business where profit margins are currently 4% and affected by one off items. Oversight from directors with hands on commercial track records may help management balance pipeline ambition with the very real risks around R&D intensity and funding.
Alkermes' analyst narrative points to revenues of US$2.3b and earnings of US$374.7 million by 2029, based on an assumed 10.6% yearly revenue growth rate and a move in earnings from US$66.1 million today to that 2029 consensus, which is an increase of about US$308.6 million.
Uncover why Alkermes' fair value indicates a 37% potential upside to its current price that could narrow quickly.
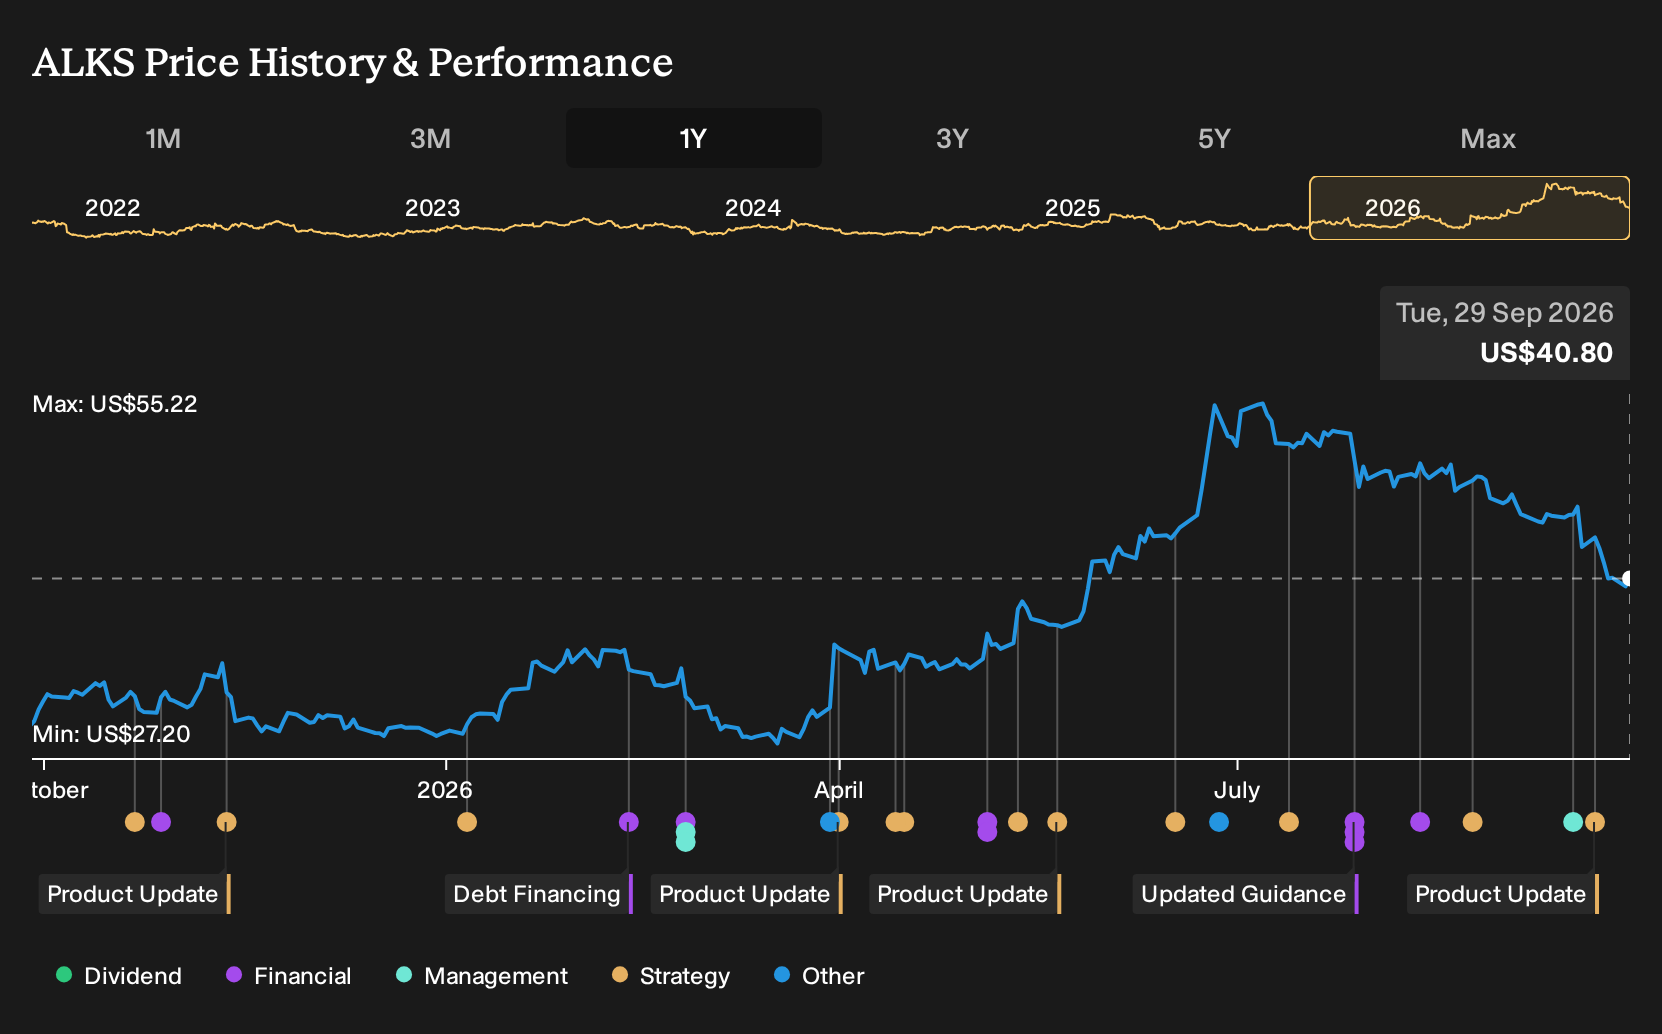
Exploring Other Perspectives
The most optimistic view on Alkermes leans hard into orexin as a long term growth engine. That camp was already modeling revenue of about US$2.9b and earnings near US$1.0b by 2029, far above consensus. The fresh ALKS 7290 data could reinforce that story or cause you to reassess it. Analyst opinions clearly span a wide range, so explore several viewpoints before deciding where you sit.
Explore 4 other Alkermes fair value estimates, including one that suggests potential upside of as much as 124% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Alkermes research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Alkermes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alkermes' overall financial health at a glance.
Looking For More Investment Ideas Beyond Alkermes?
Once you have a view on Alkermes, it can help to widen the lens and compare it with other opportunities that share similar financial traits or offer a different balance of risk and return.
- If you want companies that keep balance sheet risk in check, start with a 32 resilient stocks with low risk scores that already score well on resilience.
- For investors hunting for quality at a reasonable price, a curated 32 high quality undervalued stocks can surface stocks where fundamentals and current pricing look out of sync.
- If your goal is to back under-followed stories with solid metrics, use a 17 high quality undiscovered gems built around businesses that are less crowded but still grounded in strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com