
Why Iovance Biotherapeutics Stock Is In Focus After Revenue Guidance Raise
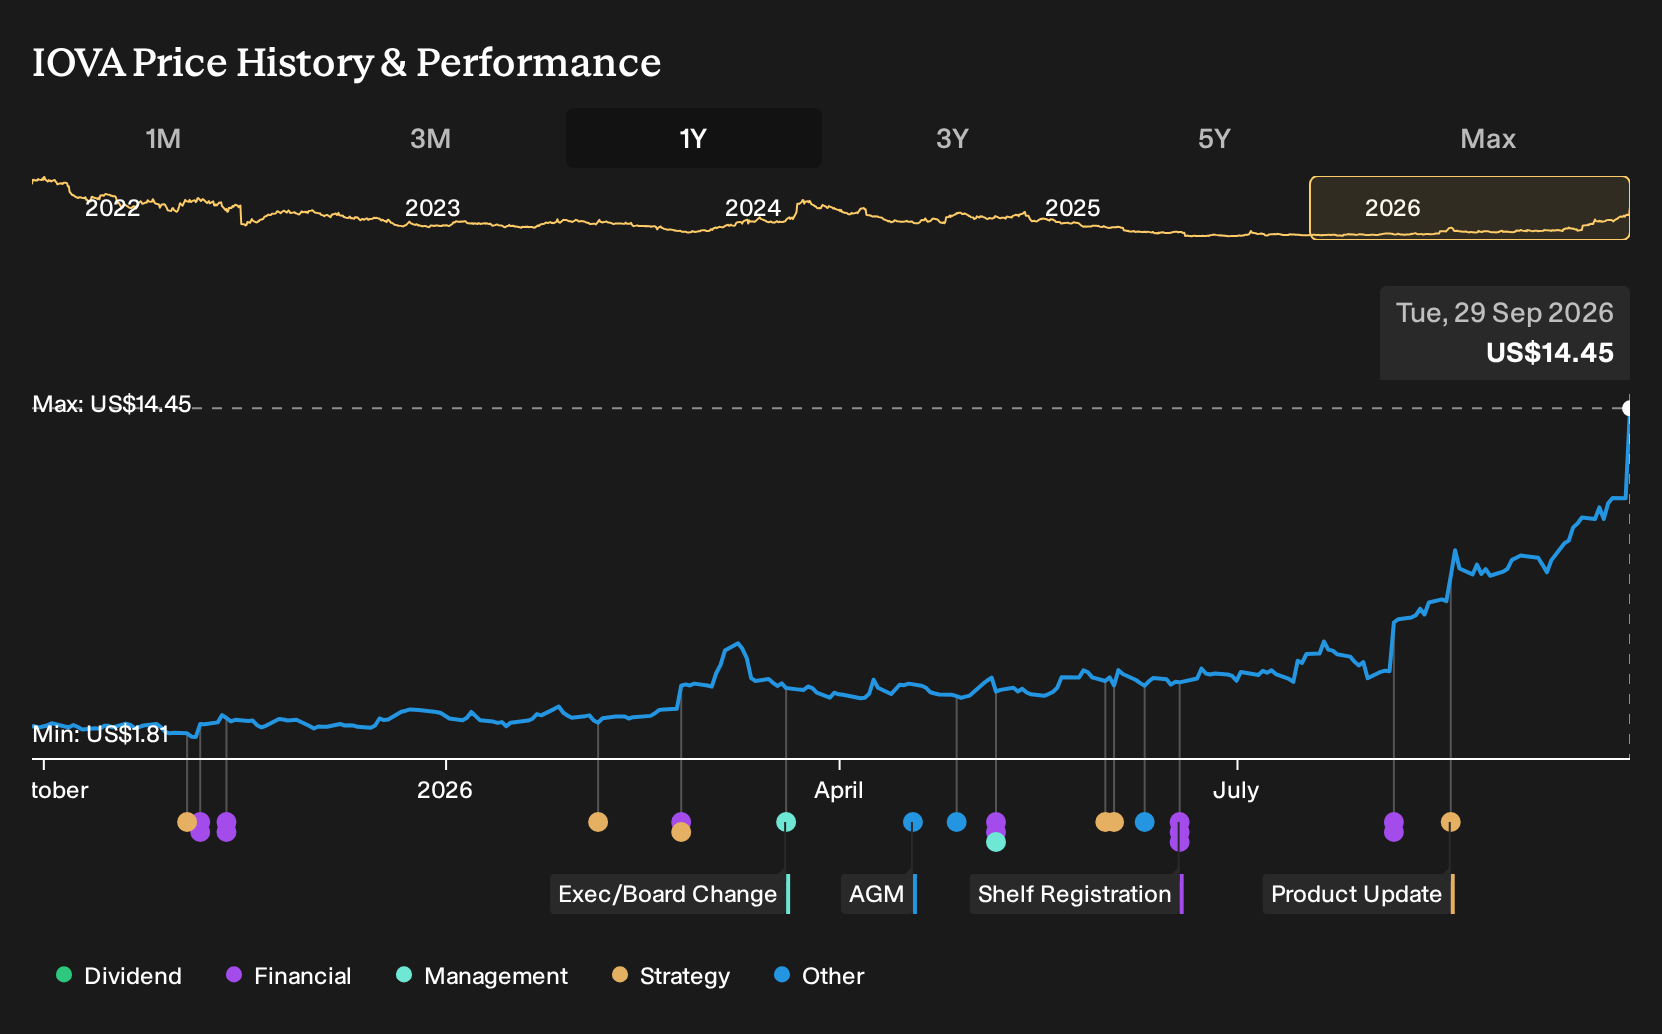
- Iovance Biotherapeutics recently lifted its full year 2026 revenue guidance to US$410 million to US$420 million, citing strong U.S. demand for its Amtagvi and Proleukin cancer therapies and support from record second quarter product revenue.
- The updated outlook highlights that expanding the Amtagvi treatment center network toward roughly 110 locations and improving operations are increasingly central to Iovance Biotherapeutics' commercial execution story.
- We will now look at how Iovance Biotherapeutics's higher 2026 revenue guidance, driven by Amtagvi demand, could reshape its investment narrative.
Scan beyond Iovance Biotherapeutics and compare this guidance-driven move with other high-potential biotech stories in our hand-picked list of 17 high quality undiscovered gems
Iovance Biotherapeutics Investment Narrative Recap
Iovance Biotherapeutics appeals to investors who believe TIL therapies can become a scaled, routine option in solid tumors and that the firm can turn that science into a durable commercial engine. The higher 2026 revenue guidance leans on Amtagvi and Proleukin momentum, so in the near term the key catalyst remains sustained U.S. demand and smooth manufacturing throughput.
The biggest risk remains the same. The business is heavily tied to Amtagvi, with international approvals delayed and margins still pressured by complex production. Any wobble in utilization, reimbursement, or capacity could weigh on progress toward profitability, regardless of the upgraded revenue outlook.
The raised 2026 revenue range to US$410 million to US$420 million is the clearest recent signal around Iovance Biotherapeutics. That outlook, supported by record second quarter product revenue and strong U.S. uptake for Amtagvi and Proleukin, feeds directly into the near term story of scaling the treatment center network and improving operational efficiency.
This guidance update also interacts with existing catalysts that focus on streamlining costs and expanding TIL indications. Execution risk around manufacturing complexity, regulatory delays outside the U.S., and pricing scrutiny does not go away because of higher guidance. The real test is whether Iovance can keep demand, capacity, and cost discipline aligned as it pursues broader adoption.
Iovance Biotherapeutics' current analyst narrative points to US$957.8 million of revenue and US$91.0 million of earnings by 2029, based on an assumed 43.4% yearly revenue growth rate and an earnings swing of roughly US$380 million from a loss of US$289.5 million today to that forecast profit level.
Uncover why Iovance Biotherapeutics' fair value indicates a 31% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
For Iovance Biotherapeutics, the biggest swing factor in the more cautious narrative is future drug pricing pressure. Before this guidance raise, the lowest analysts were working off revenue of about US$848.8 million and earnings of US$150.9 million by 2029. That is far more pessimistic than consensus, and the new outlook could prompt you to reassess which story is closer to your own view.
Explore 5 other Iovance Biotherapeutics fair value estimates, including one that suggests as much as 58% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Iovance Biotherapeutics research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Iovance Biotherapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Iovance Biotherapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Iovance Biotherapeutics?
If the shifting guidance and risk profile around Iovance Biotherapeutics has you thinking about portfolio balance, it can help to line it up against other opportunities that fit different roles in your holdings. The Simply Wall St Screener lets you filter by quality, valuation, income, and risk so you can build a more rounded watchlist instead of relying on a single story.
- For investors hunting for potential mispriced opportunities with strong underlying fundamentals, start by scanning a curated 32 high quality undervalued stocks that might warrant a place on your radar.
- If capital preservation and balance sheet strength sit higher on your priority list, filter for a list of solid balance sheet and fundamentals (25 results) that can offset the riskier parts of your portfolio.
- When you want exposure to earlier stage stories with room for discovery, consider casting a wider net across a 9 elite penny stocks with strong financials that meet your own risk and thesis criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com