
Eaton (ETN) Following COL Group Deal Is Its Valuation Back In Focus
Why Eaton stock is back in focus after the COL Group deal
Eaton (ETN) is back on investors’ radar after agreeing to acquire Italy based COL Group for an enterprise value of €810 million, in a move centered on utility grids and data centers.
The Eaton share price has climbed 7.57% over the past month and 32.37% year to date, while the 1 year total shareholder return is 17.05% and the 5 year total shareholder return is 209.52%. This points to strong longer term momentum, and the COL Group deal now feeds into a fresh narrative around grid and data center exposure.
Scan other grid and data center plays moving on similar themes with our curated list of 39 power grid technology and infrastructure stocks for ideas beyond Eaton.
Eaton’s recent share move could be read as a straightforward reaction to the COL Group deal, or as sentiment chasing anything tied to grids and data centers. The valuation section tests which story fits better.
Most Popular Narrative: 16% Undervalued
Eaton last closed at $433.27, while the most followed narrative on the stock points to a fair value of about $517. That gap frames the COL Group deal as one more piece in a larger grid to data center story rather than a one off headline.
Eaton Corporation (NYSE: ETN) is one of the rare institutions that has managed to turn the physical constraints of heavy industry and metallurgy to its advantage. Its monopolistic position, benefiting from high material constraints (GOES), years-long delivery times, and in-cabinet thermal densities of 120 kW, along the Voltage Cascades from a 400,000-volt grid to 1 volt on a chip, has provided the company with an unsurpassable economic moat. The acquisition of Boyd Thermal and the Dana Mobility Reverse Morris Trust have steered the company onto a secular growth path by fully optimizing its portfolio for megatrends.
See why 12 investors see Eaton as 16% undervalued.
Result: Fair Value of $517 (UNDERVALUED)
Still, Eaton’s story can be knocked off course if transformer bottlenecks ease faster than expected or if large AI data center build plans slow sharply.
Find out about the key risks to this Eaton narrative.
Another View on Eaton’s valuation
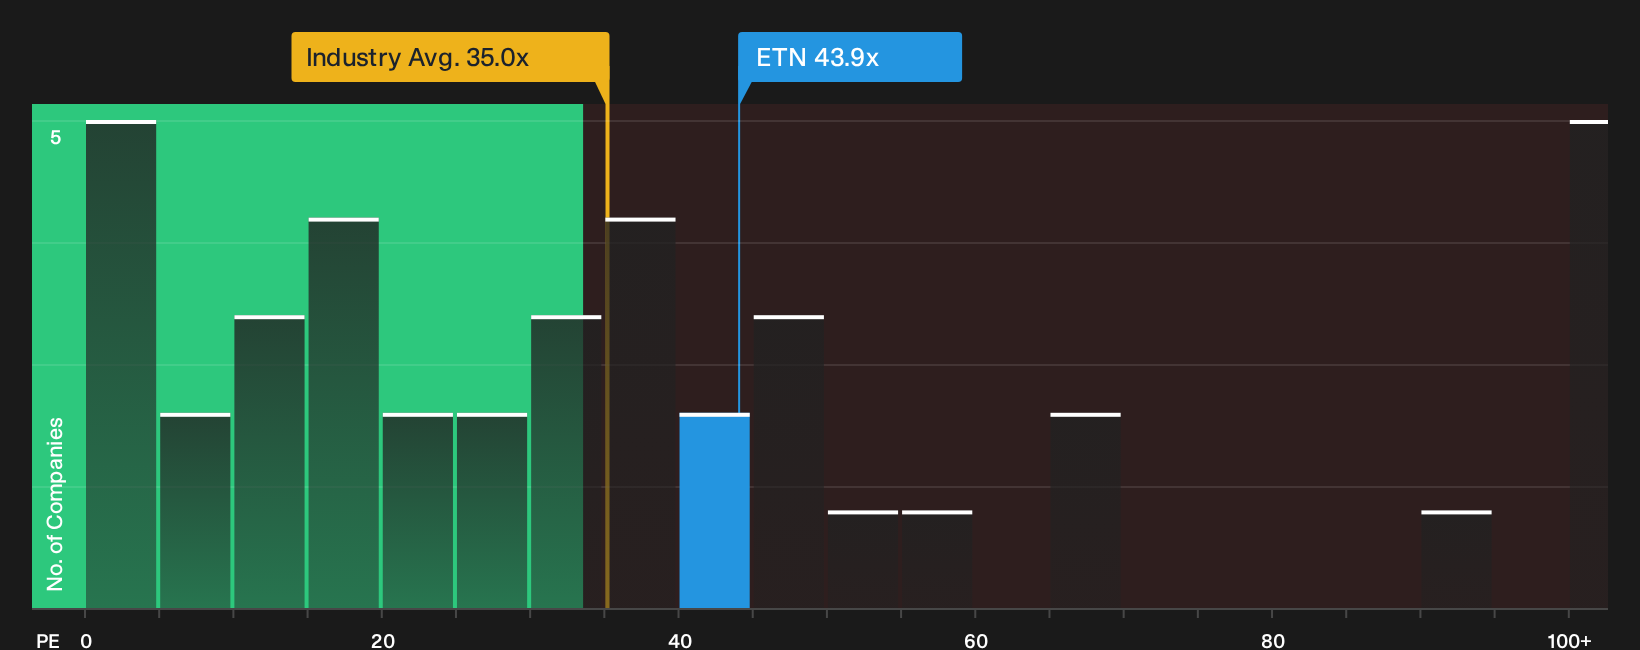
The story changes once you look at Eaton through the current P/E lens instead of that narrative fair value of $517. The stock trades on 43.9x earnings, which is higher than the US Electrical industry on 35x and slightly above the peer group at 41.4x.
At the same time, that 43.9x figure sits very close to the estimated fair ratio of 44.4x. In practice, that points to limited room for error and puts more weight on Eaton hitting the growth and margin expectations baked into today’s price. Which lens do you trust more right now: the grid story or the multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Eaton story feels finely balanced to you, that is the point. This is the moment to move fast and test the assumptions yourself. To see both sides of the current debate on the stock, start by weighing the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Eaton?
If Eaton has sharpened your thinking, do not stop here. Broader context from other opportunities can make your next move far more informed.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results) before capital shifts to the next theme.
- Spot potential mispricing early by reviewing the 32 high quality undervalued stocks that align with your risk and return expectations.
- Hunt for off the radar opportunities using the 17 high quality undiscovered gems before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com