
SHEIN (SEHK:625) Stock Price Drops 18% As Profit Roars Back
SHEIN Global Holdings just posted a blockbuster quarter while the stock limped into the print. Shares were down about 18% over the past week, yet Q2 delivered Basic EPS of US$0.93 and net income of US$2.40b on revenue of US$11.08b, a powerful reset after a small loss in Q1.
The tension is clear. Short term traders have been leaning away from the stock, but the latest earnings present a far stronger profitability profile for a business already trading on a P/E of 5.1x.
Is SHEIN Global Holdings trading at a genuine discount, or simply carrying a lot of balance sheet risk that explains the low P/E multiple? Compare the current share price to intrinsic value in the valuation analysis for SHEIN Global Holdings.
Q2 2026 Earnings Summary
- Revenue (Q2 2026 vs. Q2 2025): US$11.08b vs. US$10.99b (up about 1%)
- Net Income (Excl. Extra Items, Q2 2026 vs. Q2 2025): US$2.40b vs. US$691m (very large increase, more than 3x higher)
- Basic EPS (Q2 2026 vs. Q2 2025): US$0.93 vs. US$0.27 (up more than 3x per share)
- Trailing 12-Month Net Income (Excl. Extra Items, Q2 2026 TTM vs. Q2 2025 TTM): US$3.28b vs. US$2.79b (up about 18%)
Prefer clean visuals instead of scrolling through dense tables and footnotes? See the full financial picture for SHEIN Global Holdings, including a clear view of its valuation setup, in the company report for SHEIN Global Holdings.
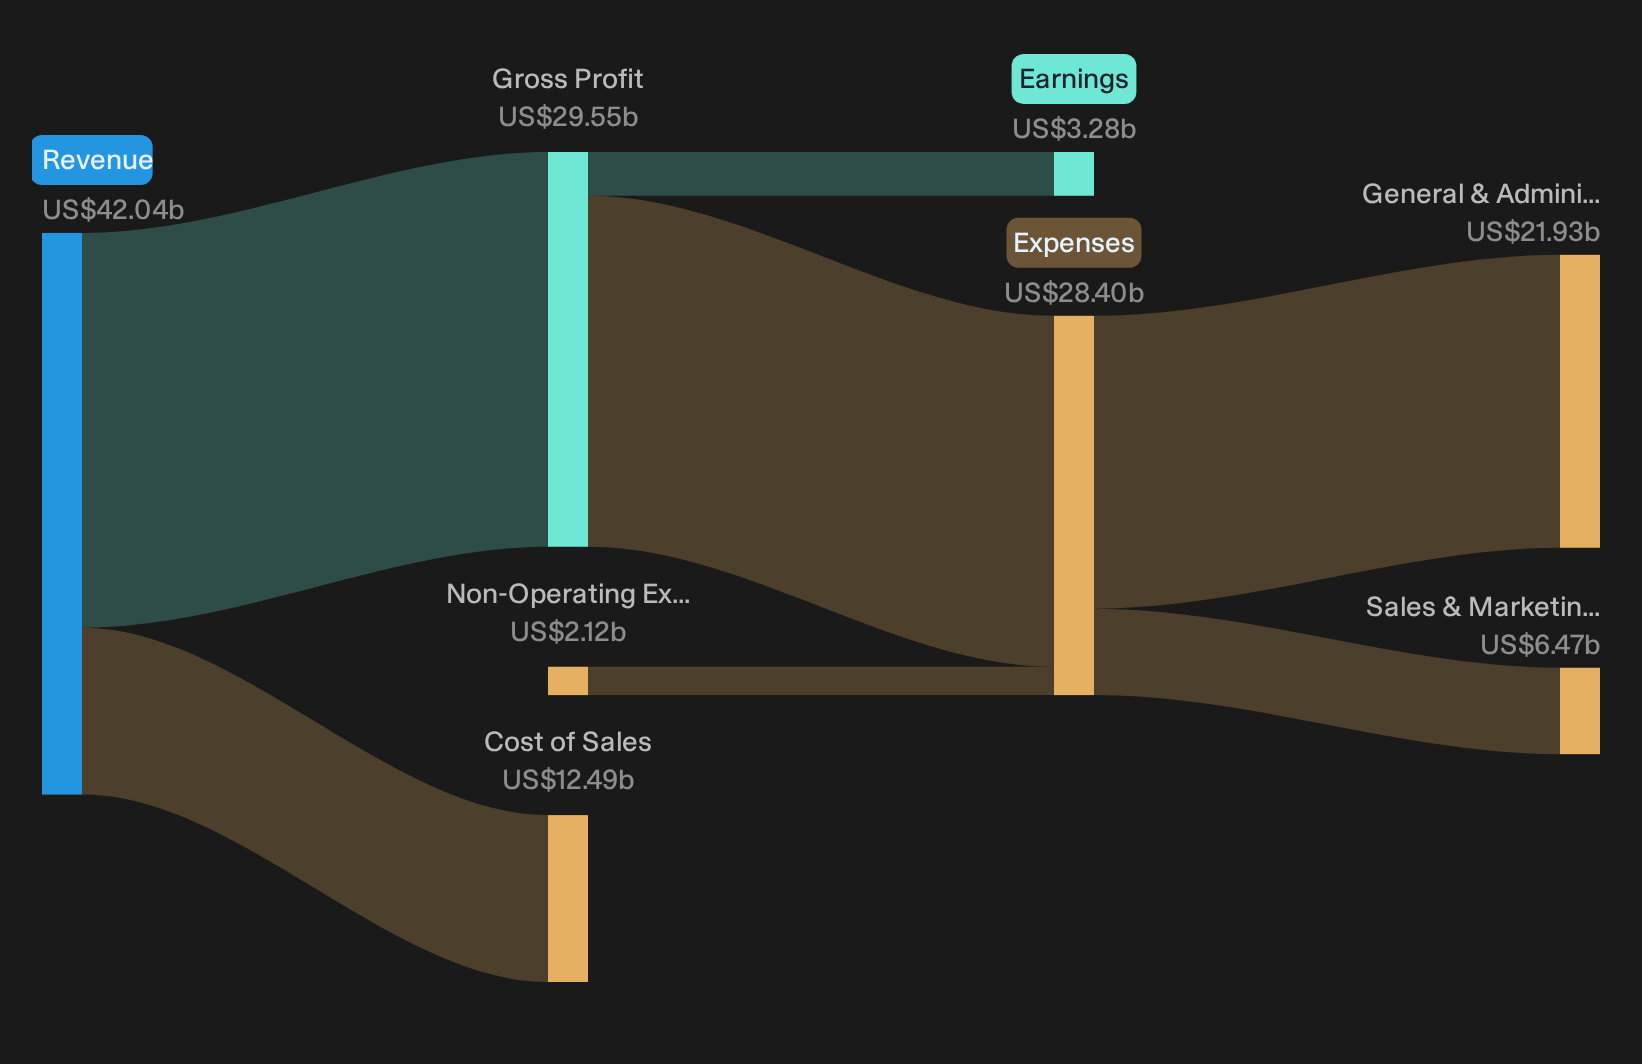
SHEIN earnings momentum backing brand-led optimism
SHEIN Global Holdings just posted revenue of US$11.08b with net income of US$2.40b and Basic EPS of US$0.93. Profitability looks much stronger than a year ago, while trailing 12-month net income sits at US$3.28b. That kind of earnings power supports the idea that a large, global fast fashion platform can turn heavy user engagement into cash flow, not just clicks. For investors leaning into the brand and marketplace story, the shift from a small loss in Q1 to this level of profit points to a business model that is currently holding up.
Bearish worries meet a more resilient profit profile
Short term, the share price fell about 18% over the past week, so skepticism around SHEIN Global Holdings is real. Yet the income line tells a different story, with Q2 net profit of US$2.40b and trailing 12-month earnings of US$3.28b. That direction challenges fears that scale would simply magnify cost pressures or ESG and regulatory headlines. Revenue sits at US$11.08b, so margins look healthy for a mass market retailer. Near term, the financial trend points to immediate risks around the core business model being less severe than recent trading suggests.
After a week in which SHEIN Global Holdings dropped 18% despite strong Q2 earnings, it is fair to ask whether liquidity constraints, negative shareholders’ equity, and weak debt coverage hint at deeper structural fragility. Review the full risk analysis for SHEIN Global Holdings which shows 4 important warning signsStay Ahead Of Your Next Move
If the sharp split between SHEIN Global Holdings’ strong Q2 profitability and the recent 18% share price drop has your attention, register for free with Simply Wall St and add it to a Watchlist to watch the price against fair value and spot a potential entry that fits your plan. Once you own it or any other position, keep a clear view of what matters using the Portfolio Command Center so that key alerts and fundamental changes rise above day to day noise. Round that out by tapping into thousands of viewpoints through the Community and see how other investors are interpreting the same data. That combination helps you surface hidden catalysts and risks early so you can stay ahead of the market instead of reacting to it after the fact.
Seeking Alternatives Beyond SHEIN Global Holdings?
Fresh ideas move first. While attention clusters around SHEIN Global Holdings, other themes can be setting up for breakout momentum under the radar for now. Scan new angles and act now.
- Chase durable cash flow stories and focus on companies with strong balance sheets using the curated list of solid balance sheet and fundamentals stocks (205 results) before the market fully prices in their resilience.
- Track income opportunities that might hold up even when sentiment swings and review curated yield ideas through the 161 dividend fortresses while payout momentum still flies under the broader radar.
- Hunt for early-stage potential where smaller players already generate profits and use the focused 37 profitable AI stocks that aren't just burning cash before stronger earnings traction attracts more attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com