
Applied Materials (AMAT) Stock May Be In Line Following AI Memory News
Applied Materials has ridden a powerful semiconductor and AI spending wave, and its stock now changes hands at levels that put a lot of faith in future profit streams. With that kind of backdrop, the obvious question is whether the current share price can be explained by the earnings that underpin it.
- Over the past 5 years the stock has returned 316.7%, which puts a lot of long term gains on the line if today’s valuation is not well supported by profit generation.
- New work with KIOXIA at Applied Materials' EPIC Center, focused on next generation memory and packaging for AI chips, may support expectations for stronger earnings power if those technologies translate into commercially successful tools.
- There is a second opinion on Applied Materials worth weighing. See what analysts think Applied Materials's shares could be worth.
The issue now is whether that share price, after such a strong multi year run, is justified by Applied Materials' earnings when viewed against the Fair Ratio benchmark.
You can stress test the same Fair Ratio question beyond Applied Materials by scanning a wider field of AI infrastructure plays through the 88 AI infrastructure stocks.
Where Does Applied Materials Sit on Earnings?
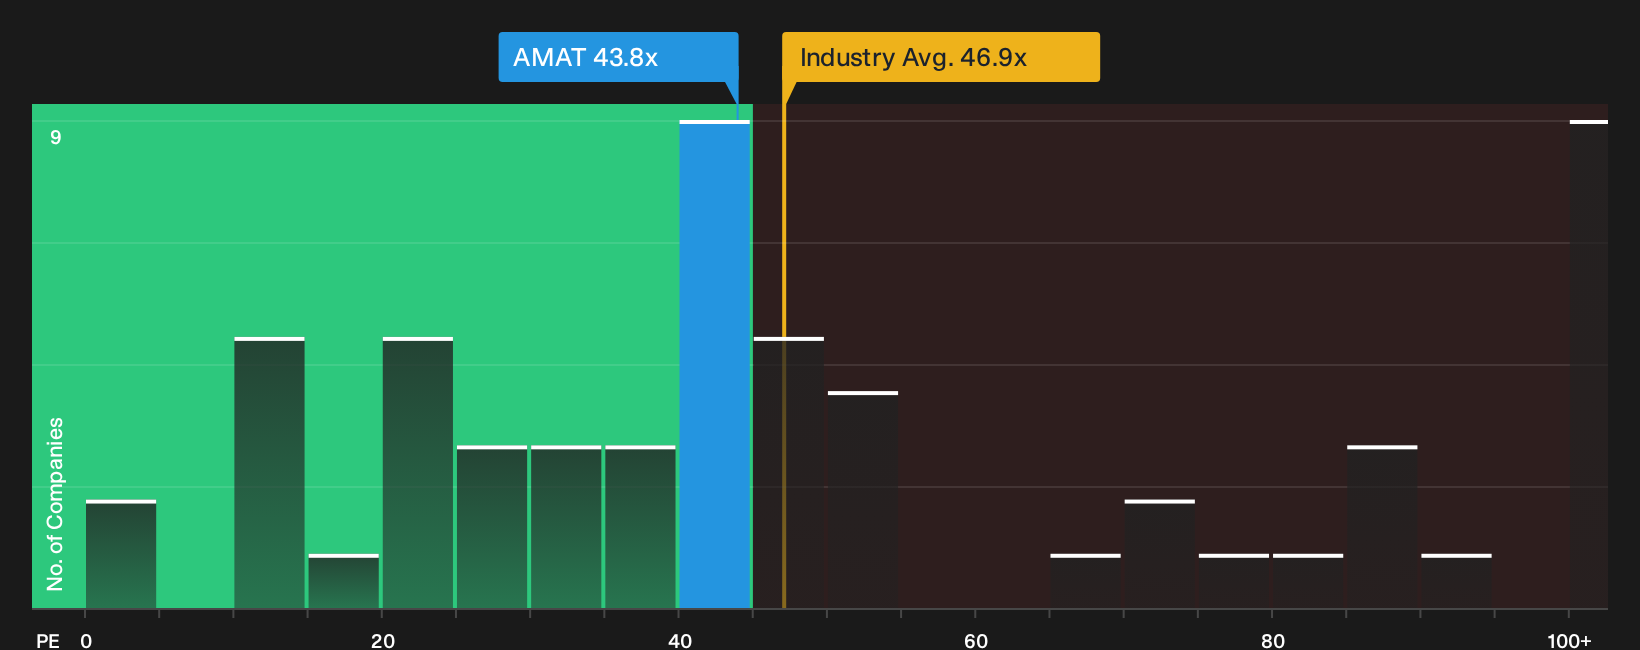
The P/E ratio suits Applied Materials because earnings remain a central anchor for how investors frame AI and semiconductor equipment plays. Applied Materials trades on a P/E of 43.8x, very close to both the Semiconductor industry average of 46.9x and the peer group at 45.9x. That keeps the stock in the same valuation ballpark as similar chip equipment producers rather than marking it as a clear outlier.
On a tailored Fair Ratio lens that blends growth expectations, margins, scale and risk, the current 43.8x multiple sits very close to where that framework would expect it to land. Because the new KIOXIA EPIC Center collaboration adds another AI focused earnings story into the mix, investors appear willing to pay a P/E that prices Applied Materials broadly in line with comparable chip equipment stocks rather than at a steep discount or premium. Explore the numbers behind Applied Materials's P/E valuation.
The Applied Materials Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Applied Materials pick up where the valuation puzzle leaves off. Narratives outline which combinations of future growth, profitability and earnings paths would need to materialise for Applied Materials' current P/E to look either restrained or stretched compared to where the stock trades today. Each narrative then links a specific fair value to a clear story around potential catalysts and key risks, so you can track which version of events is gradually unfolding on the Community page.
Applied Materials attracts both optimists and skeptics, with community fair value views pulling in opposite directions.
Bull case: 18% undervalued
"Advanced packaging remains Applied's area of highest market share, bolstered by strong customer collaboration and a growing pipeline of new hybrid bonding and integration technologies…"
Discover why this Narrative puts Applied Materials at 18% undervalued.
Bear case: 18% overvalued
"Trade restrictions and slowed DRAM and ICAPS sales may significantly limit revenue growth, especially from the China market…"
Explore why this Narrative puts Applied Materials at 18% overvalued.
The Applied Materials story has one more question that could matter
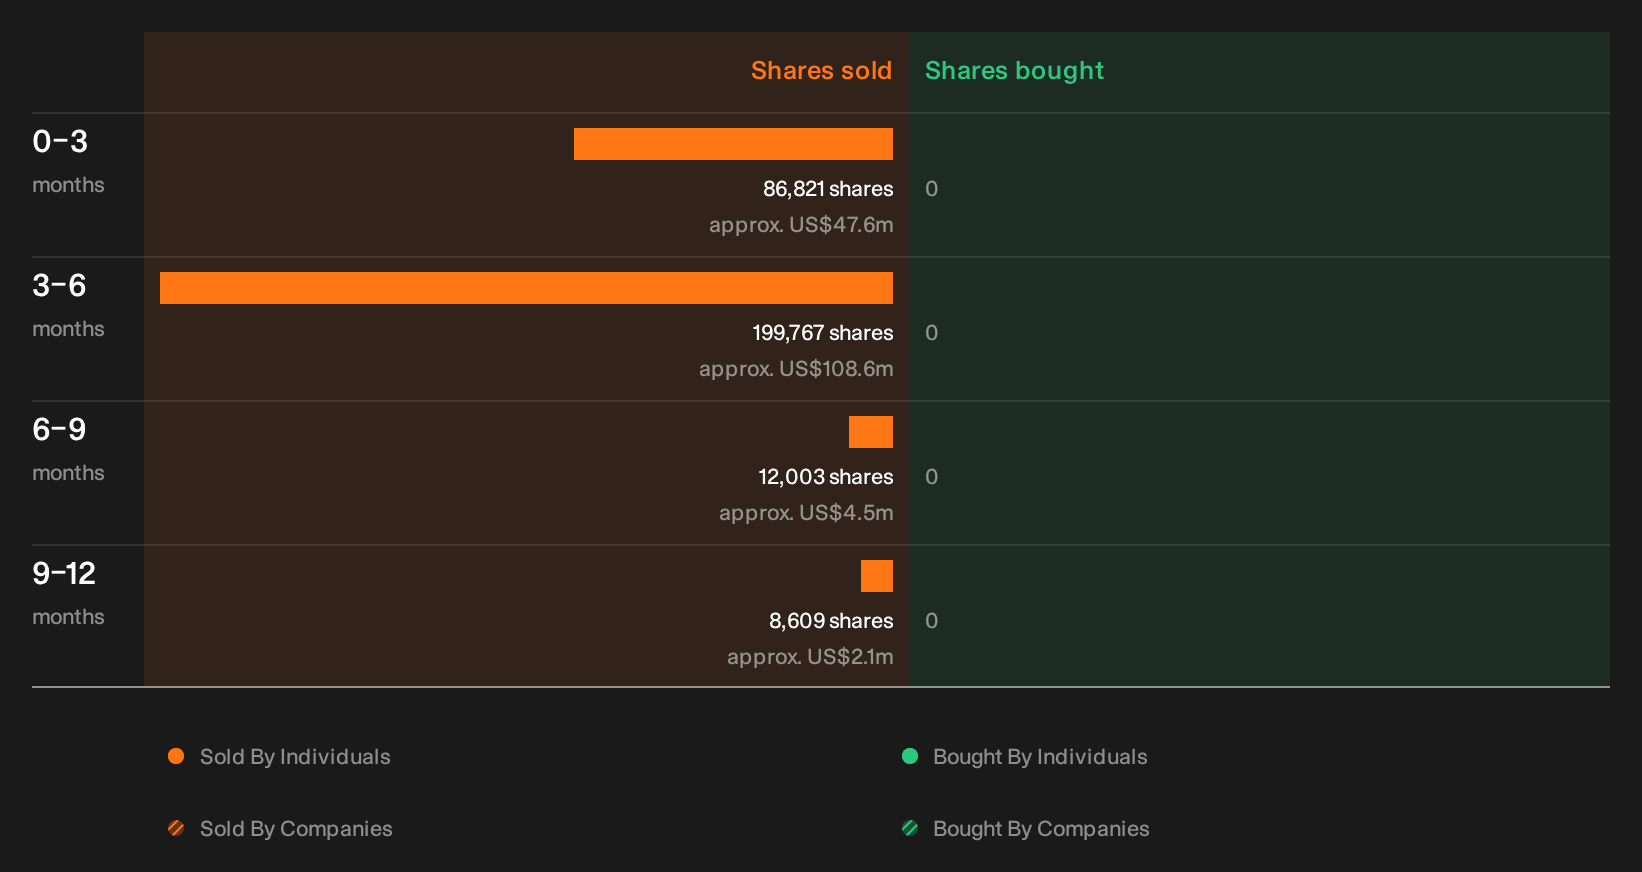
Valuation only tells part of the picture for Applied Materials, because recent actions by senior insiders can add an extra clue about confidence levels and timing, and those specific trades are sitting there for you to review. See the recent insider selling flagged for Applied Materials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com