
General Mills (GIS) Stock Looks Reasonable Even With Caution On Sales
General Mills shares have been under sustained pressure in recent years, which puts fresh focus on whether the current US$33.82 price still lines up with what the business delivers in sales. With sentiment shaped by both weaker recent returns and ongoing business adjustments, the key issue is how the market is now valuing each dollar of General Mills revenue.
- Over the past 3 years the stock has fallen 38.3%, which puts real weight on the question of what investors are currently willing to pay for the company’s sales base.
- Recent updates on cost savings, product refreshes and marketing efforts speak directly to future revenue quality and margins, which can influence how much value the market assigns to each unit of sales.
- There is a second opinion on General Mills worth weighing. See what analysts think General Mills's shares could be worth.
For investors, the debate is whether General Mills' current share price is justified by its sales when measured against the Fair Ratio benchmark.
If you are reassessing General Mills on its sales multiple, it can help to compare it with a wider set of value ideas screened on 32 high quality undervalued stocks
Is General Mills Still Cheap on Sales?
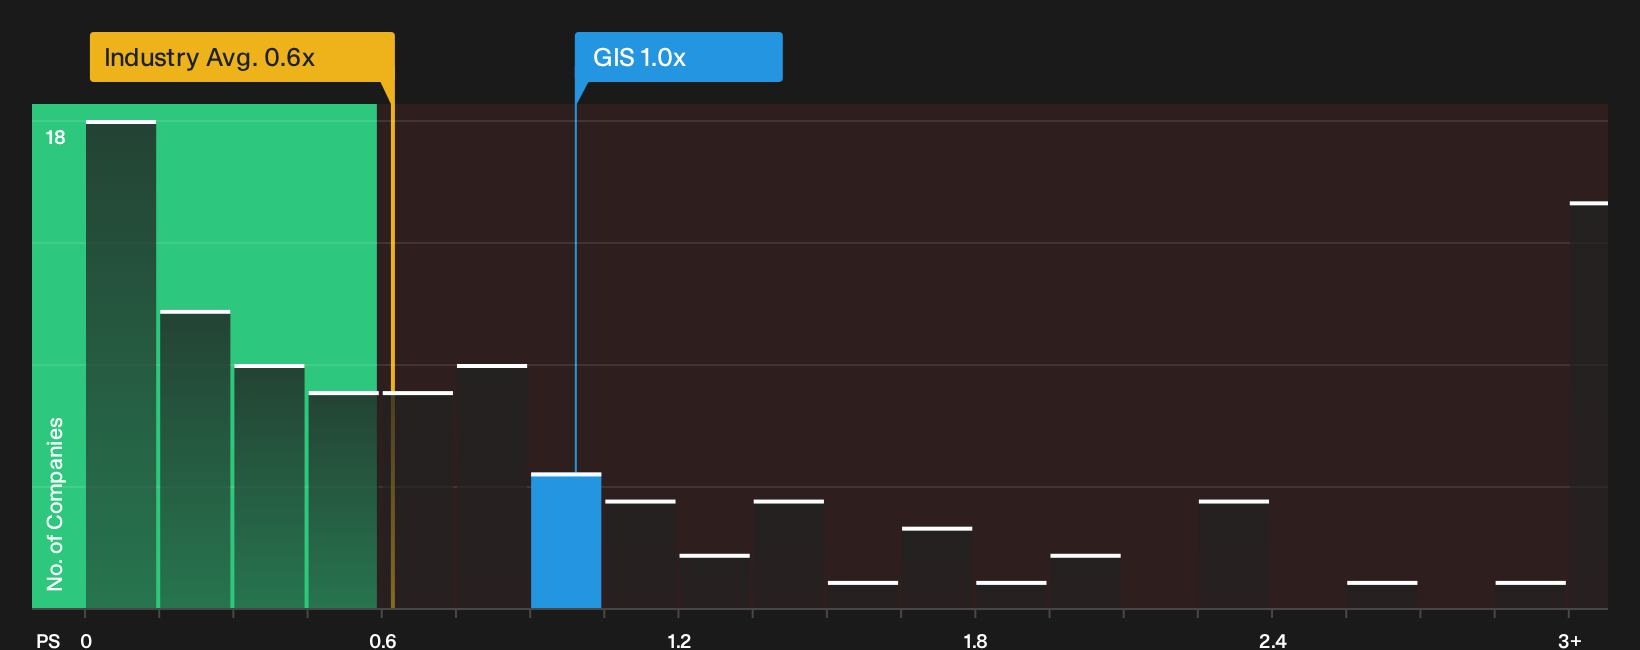
P/S is a useful lens for General Mills because packaged food producers tend to have steadier revenue lines than more cyclical sectors. On this measure, the stock trades at about 1.0x sales, which is above the broader Food industry average near 0.6x but a little below the peer group at roughly 1.2x. That puts the company in an interesting middle ground where the wider sector screens cheaper on sales, but closer peers are priced a bit richer.
The Fair Ratio model, which adjusts the sales multiple for General Mills' margin profile, size and risk, points to a higher P/S than the current 1.0x. On this framework, the shares screen undervalued. Because management recently reaffirmed its full year outlook despite pressure in the Pet segment and ongoing cost inflation, the current discount on P/S suggests investors are still pricing in caution around how reliably future sales will translate into profit. Explore the numbers behind General Mills's P/S valuation.
The General Mills Narrative: What Would Justify Today's Price?
Narratives for General Mills on Simply Wall St pick up where the valuation puzzle leaves off. They spell out which paths for revenue, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than today. Where a single multiple or model gives one output, Narratives lay out the future that figure quietly relies on so you can watch how real world developments line up against it over time on the Community page.
General Mills investors are split between those who see cost savings turning into value and those who see spending and category pressure as a drag.
Bull case: 10% undervalued
"General Mills plans to deliver US$750 million of cost savings in fiscal 2027 as part of a US$3 billion program through fiscal 2030…"
Discover why this Narrative puts General Mills at 10% undervalued.
Bear case: 9% overvalued
"The heavy emphasis on remarkability investments, including a double digit increase in media spend and higher SG&A, risks locking General Mills into structurally higher overhead…"
Explore why this Narrative puts General Mills at 9% overvalued.
The price is only one chapter in the General Mills story
Valuation tells you what the market pays today, but the real question is how professionals expect General Mills to look a few years from now and how that lines up with your own view. Explore where analysts expect General Mills to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com