
European Penny Stocks To Watch In September 2026
As European markets navigate a landscape of improving growth signals and inflation concerns, the pan-European STOXX Europe 600 Index has edged up, reflecting cautious optimism. Amid these broader market dynamics, penny stocks—typically smaller or newer companies—continue to capture investor interest with their potential for growth at accessible price points. While the term "penny stocks" may seem outdated, these investments can still offer valuable opportunities when backed by strong financials and solid fundamentals.
Let's take a closer look at a couple of our picks from the screened companies.
Cemat (CPSE:CEMAT)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Cemat A/S develops, operates, and sells properties in Poland with a market cap of DKK219.87 million.
Operations: The company's revenue is derived from Development, which contributes DKK141.53 million, and Property Management & Holding, which accounts for DKK39.74 million.
Market Cap: DKK219.87M
Cemat A/S, operating in the real estate sector in Poland, presents a mixed picture as a penny stock. The company is debt-free and boasts stable weekly volatility at 4%, with an experienced management team averaging 7.8 years of tenure. Recent earnings growth of 98.9% outpaced the industry average, yet this was partly due to a significant one-off gain of DKK28.7 million. Despite raised revenue guidance for 2026 between DKK86 million and DKK88 million, profit margins have declined from last year's 65.3% to 27.8%. Cemat trades significantly below its estimated fair value, offering potential upside for investors mindful of its volatility and profit margin fluctuations.
- Click here and access our complete financial health analysis report to understand the dynamics of Cemat.
- Learn about Cemat's historical performance here.

Glaston Oyj Abp (HLSE:GLA1V)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Glaston Oyj Abp manufactures and sells glass processing machines across various global regions, with a market cap of €42.68 million.
Operations: The company's revenue is divided into two main segments: Architecture, which generated €146.16 million, and Mobility, Display & Solar, contributing €42.48 million.
Market Cap: €42.68M
Glaston Oyj Abp, a manufacturer of glass processing machines, offers a mixed investment case. The company has recently turned profitable, reporting €7.5 million in net income for Q2 2026 compared to a loss last year. While its debt levels have decreased over five years and interest coverage is robust at 21.8 times EBIT, operating cash flow remains negative, indicating potential liquidity concerns. Despite trading at over half below estimated fair value and having stable weekly volatility of 3%, management's inexperience could pose challenges amid forecasted earnings declines of 10.3% annually over the next three years.
- Unlock comprehensive insights into our analysis of Glaston Oyj Abp stock in this financial health report.
- Gain insights into Glaston Oyj Abp's future direction by reviewing our growth report.
IDH Development (WSE:IDH)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: IDH Development S.A. operates in the infrastructure and building construction sector in Poland with a market capitalization of PLN57.80 million.
Operations: The company's revenue is derived entirely from its operations in Poland, amounting to PLN13.56 million.
Market Cap: PLN57.8M
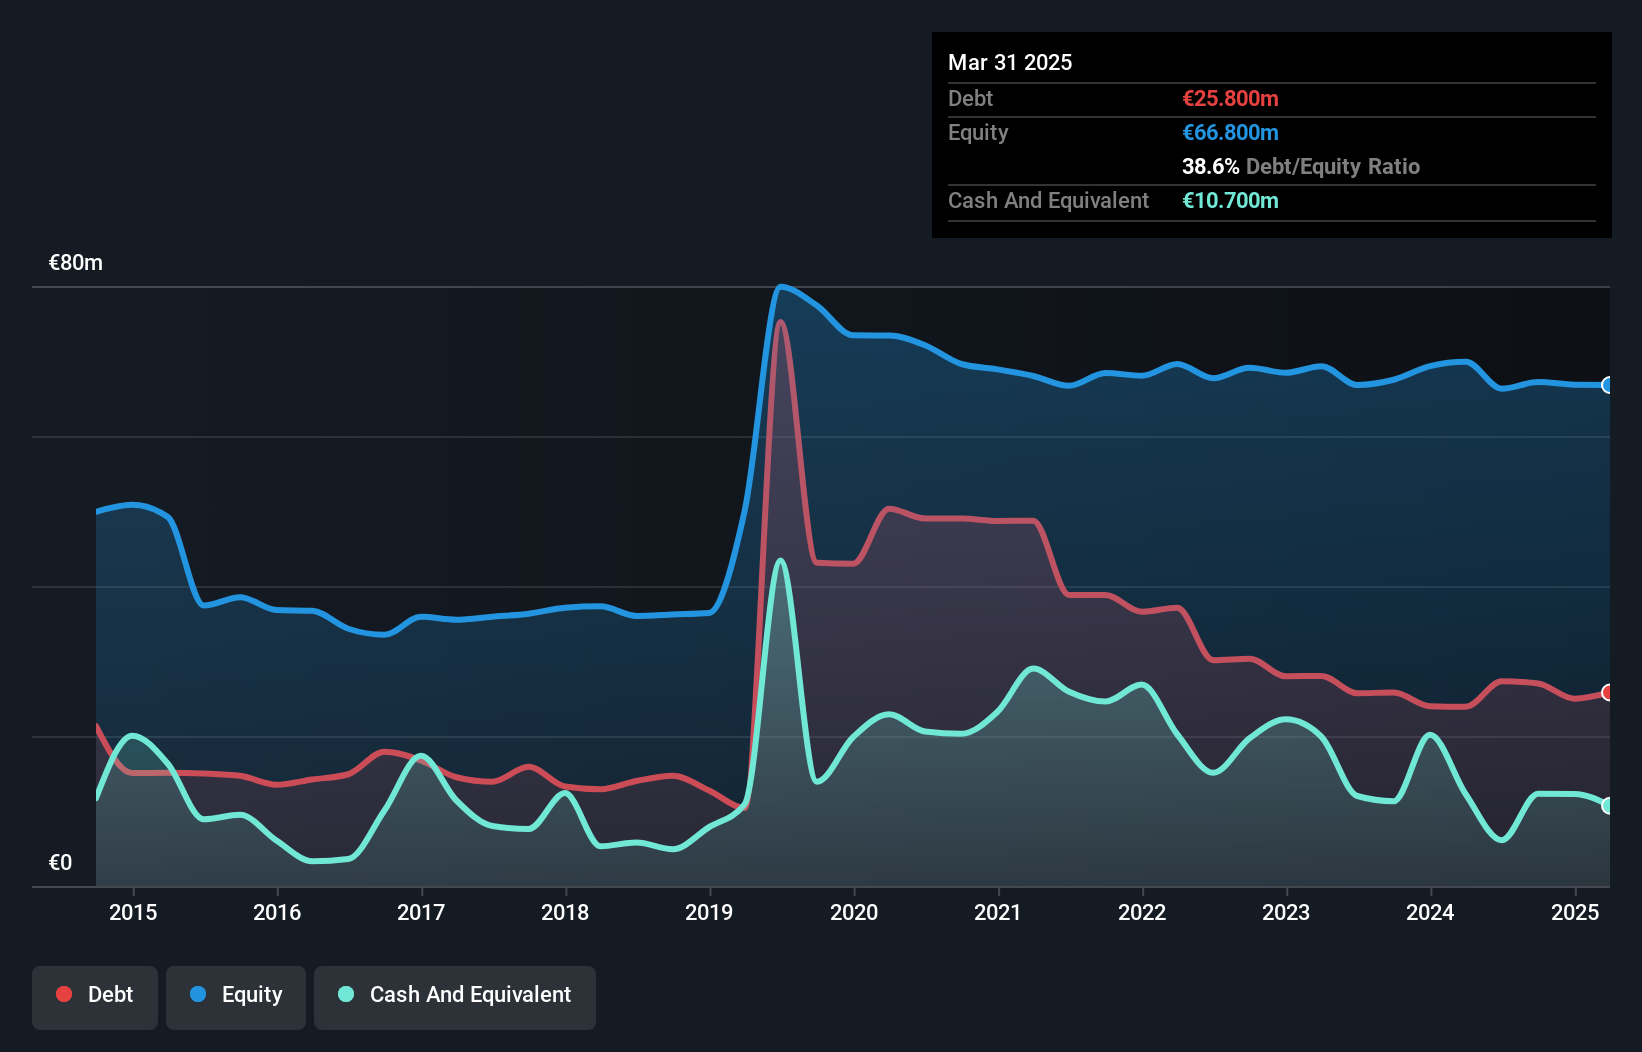
IDH Development S.A. presents a mixed picture as a penny stock in Europe's construction sector. The company has recently achieved profitability, with revenues for the first half of 2026 reaching PLN10.04 million, up from PLN1.21 million the previous year. Despite this growth, IDH's earnings were significantly impacted by a large one-off gain of PLN21.8 million, raising questions about the sustainability of its profit margins. Positively, IDH has reduced its debt significantly over five years and maintains more cash than total debt, with short-term assets exceeding both short and long-term liabilities comfortably. However, high weekly volatility persists at 15%.
- Get an in-depth perspective on IDH Development's performance by reading our balance sheet health report here.
- Understand IDH Development's track record by examining our performance history report.

Seize The Opportunity
- Investigate our full lineup of 311 European Penny Stocks right here.
- Searching for a Fresh Perspective? The end of cancer? These 35 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com