
Boy Band Partnership Might Change The Case For Investing In Gap (GAP)
- Gap Inc. has launched a multi-year Fashiontainment partnership with boy band Just Your Type, spanning a co-produced docuseries, national mall tour, co-designed capsule collection, and social content aimed at building deeper fan engagement.
- The deal embeds Gap directly into JYT’s fan ecosystem by tying product, content, and live events together to test a more entertainment-driven model for demand and loyalty.
- We will now examine how Gap's new Fashiontainment partnership with Just Your Type could influence the existing investment narrative.
Scan how Gap's entertainment pivot compares with retailers already using fandom to drive demand by zeroing in on our hand picked 17 high quality undiscovered gems.
Gap Investment Narrative Recap
To own Gap, you need to believe management can keep earnings resilient while reinvigorating its brands and cleaning up areas of weakness like Athleta and inventory management. The Fashiontainment launch with Just Your Type looks more like a test of a new engagement model than a needle mover for near term financials. The biggest near term swing factor is still basic execution in core categories and stores.
The largest immediate risk remains flat underlying demand combined with tariff exposure and prior inventory issues, which can pressure margins if promotions pick up. The JYT partnership only helps the short term story if it feeds into better traffic and healthier full price selling without adding complexity or cost that drags on profitability.
The Fashiontainment move ties directly into Gap's broader push on collaborations and media driven marketing, which analysts already flagged as a key driver of brand reinvigoration. Earnings grew 40.3% over the past year and net profit margins improved to 8.1% from 5.9%, helped by both operations and a large one off gain. Investors are watching for proof that engagement focused bets can support more durable profitability.
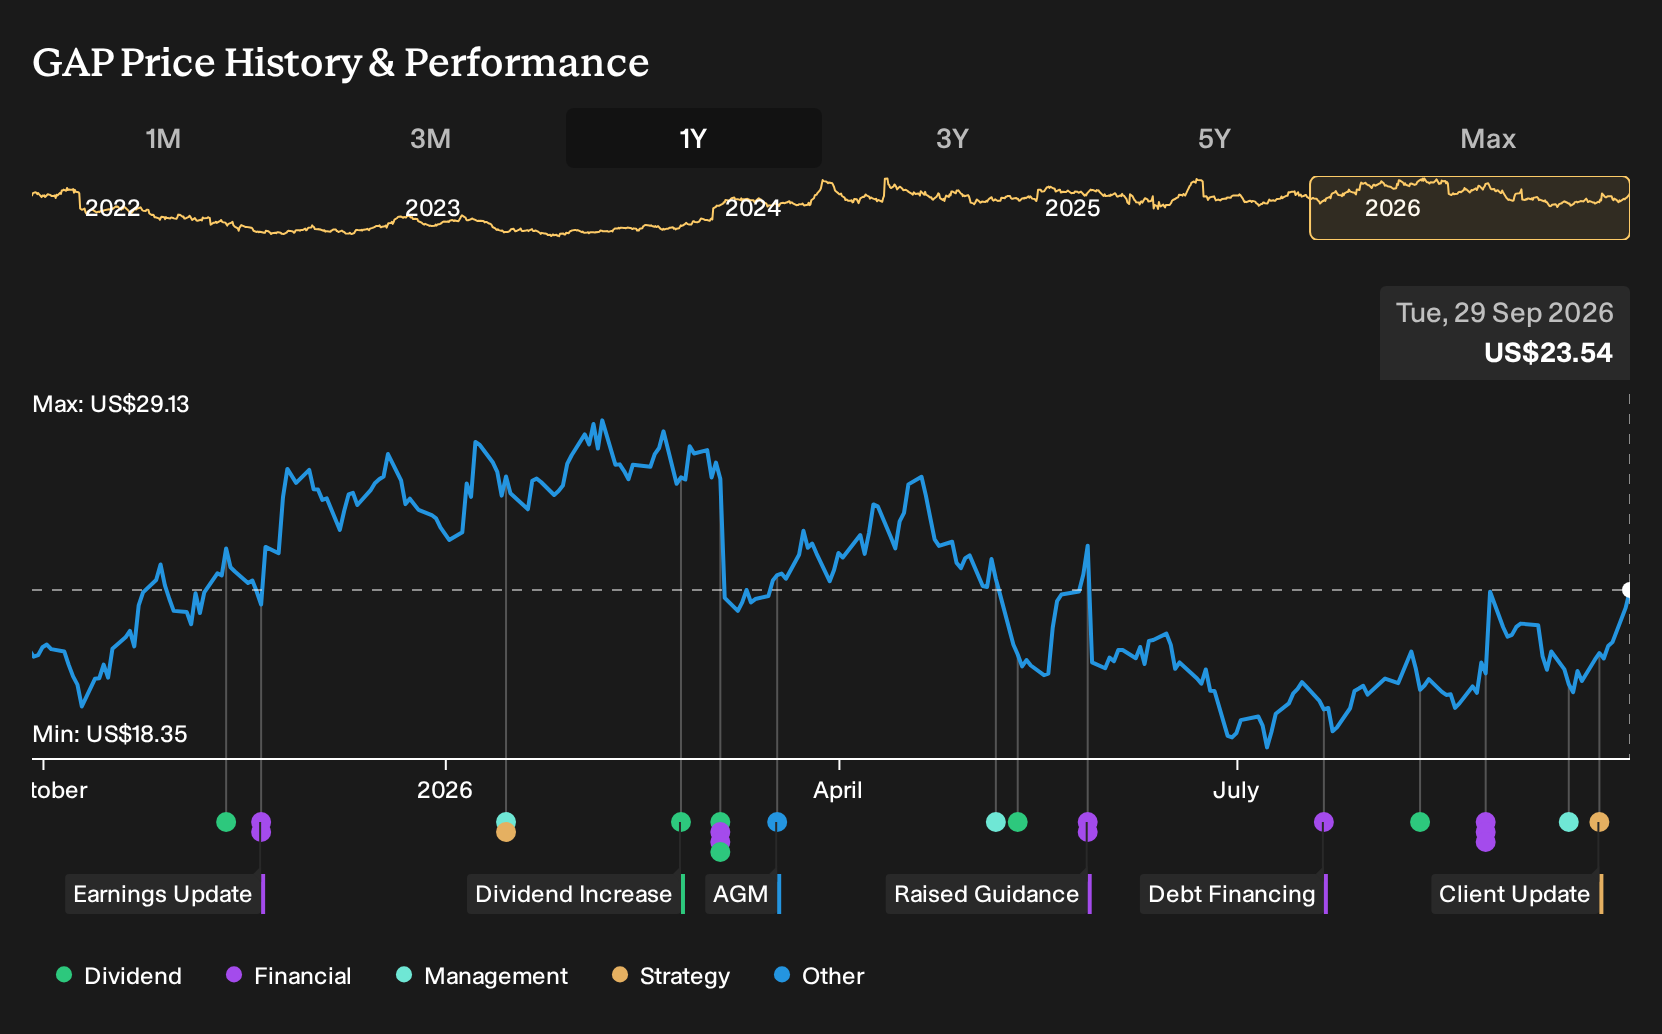
Gap trades on a P/E of 6.6x versus an industry average of 16.2x and is assessed as trading 32.2% below one estimate of fair value. For this kind of multiple to re rate, the market will likely want to see that initiatives like Fashiontainment and other collaborations connect to cleaner inventory, steadier comps and less promotional pressure, while avoiding further evidence of category misalignment like Athleta's reset.
Gap Fashiontainment In The Context Of Street Forecasts
Gap's narrative projects US$16.4b in revenue and US$1.0b in earnings by 2029, which rests on analysts assuming 2.1% yearly revenue growth and an earnings increase of about US$38m from current earnings of US$962.0m.
Uncover why Gap's fair value indicates an 11% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest Gap analysts fixate on margin pressure from heavy discounting. They were penciling in profit margins drifting to 5.4% and earnings near US$878.0m by 2029, even with revenue still modeled around US$16.4b. You can read that as a far more cautious story that fresh Fashiontainment news might eventually challenge.
Explore 5 other Gap fair value estimates, including one that indicates up to 11% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Gap research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Gap. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gap's overall financial health at a glance.
Looking For More Investment Ideas Beyond Gap?
If the Gap story has you thinking about what else might fit in a portfolio today, it can help to scan a broader set of companies that share traits you care about, whether that is value, balance sheet strength, or lower measured risk.
- For investors who want to focus on pricing that looks appealing relative to fundamentals, consider reviewing our hand picked 32 high quality undervalued stocks that line up with those priorities.
- If capital protection is front of mind and you prefer steadier profiles, you might start with a curated 32 resilient stocks with low risk scores that screen well on resilience metrics.
- When balance sheet strength and healthy financial foundations matter most, you can filter for companies through a list of solid balance sheet and fundamentals (25 results) to see which ones meet that bar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com