
Undiscovered Gems in Global Markets for September 2026
As global markets navigate the complexities of inflation concerns and fluctuating interest rates, small-cap stocks have shown mixed performance, with the Russell 2000 Index experiencing a pullback despite broader economic acceleration indicated by rising PMIs. In this environment, identifying undiscovered gems requires a keen eye for companies that exhibit strong fundamentals and resilience amidst macroeconomic challenges.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| C-Rad | NA | 13.57% | 13.83% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Aqualis | 33.30% | 22.28% | -18.13% | ★★★☆☆☆ |
Let's uncover some gems from our specialized screener.
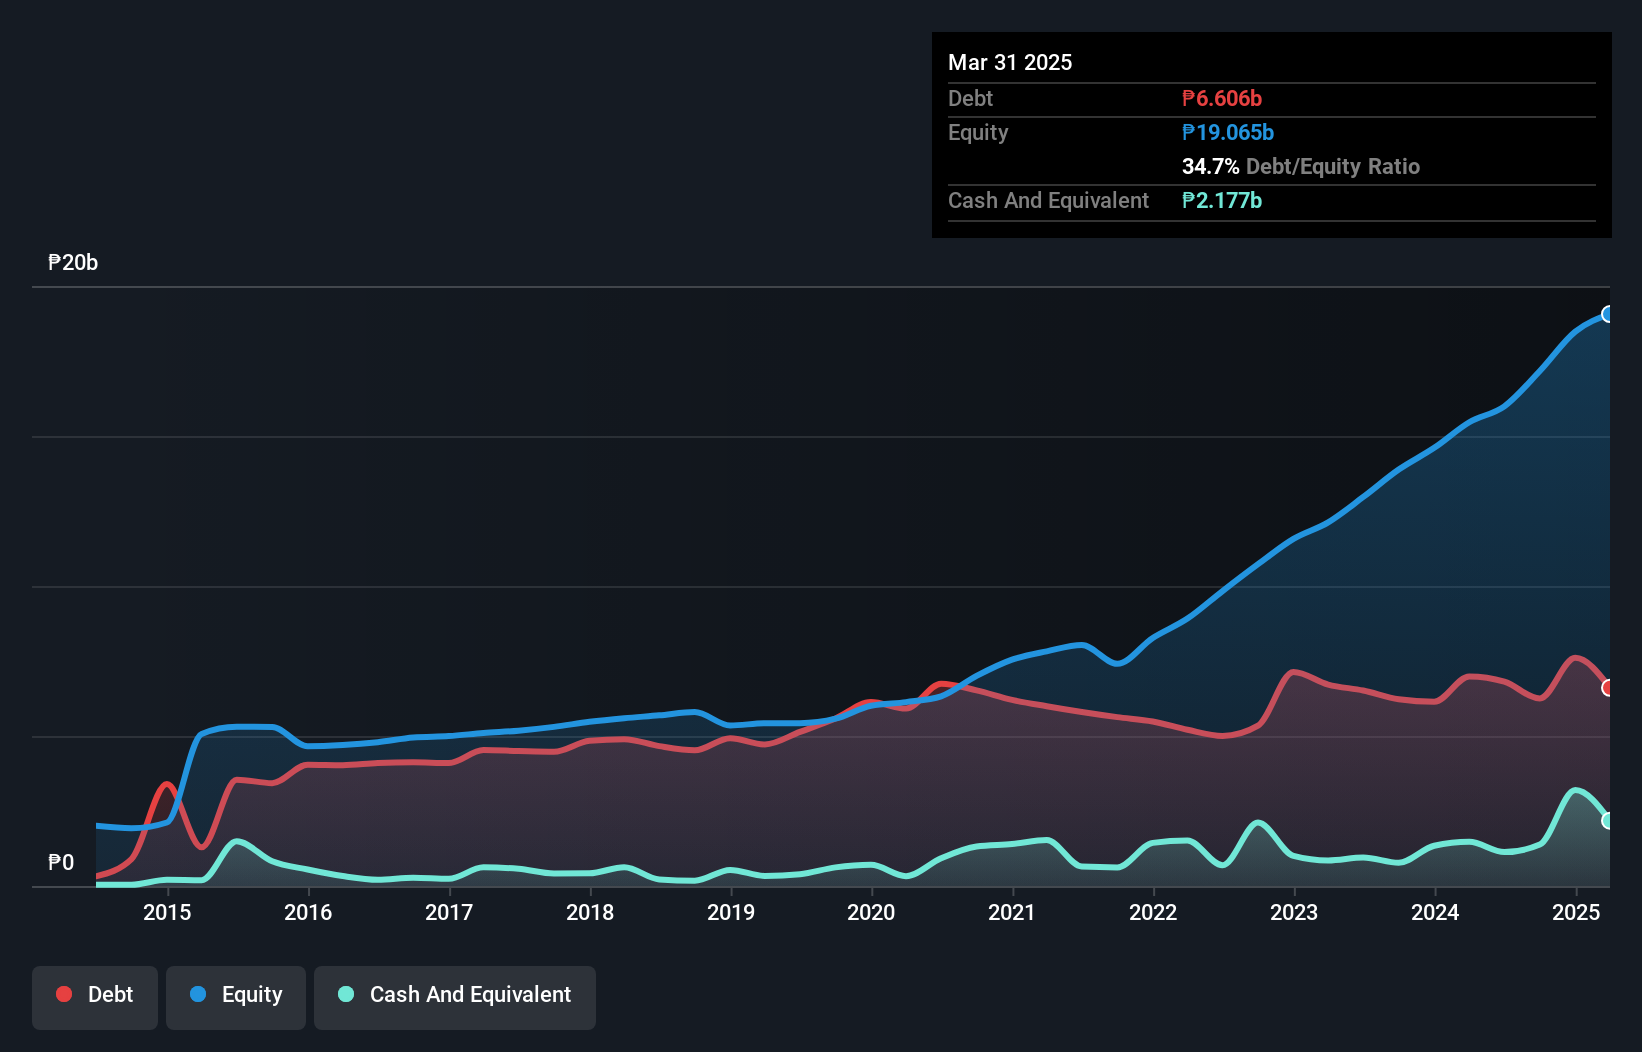
Apex Mining (PSE:APX)
Simply Wall St Value Rating: ★★★★★★
Overview: Apex Mining Co., Inc. operates in the Philippines, focusing on the mining and processing of metals and minerals, with a market capitalization of approximately ₱98.59 billion.
Operations: Apex Mining generates revenue primarily from the extraction and sale of metals and minerals. The company incurs costs related to mining, milling, and processing activities. It is important to note that fluctuations in commodity prices can significantly impact its financial performance. The company's net profit margin reflects its ability to manage these costs effectively in relation to its revenue streams.
Apex Mining, a dynamic player in the metals and mining sector, has seen its earnings grow 37% annually over the past five years. The company reported a net income of PHP 2.57 billion for Q2 2026, up from PHP 1.71 billion last year, with basic earnings per share rising to PHP 0.452 from PHP 0.302. Apex's debt management is commendable, reducing its debt to equity ratio from 72% to just 22%, while maintaining an EBIT coverage of interest payments at an impressive 24x. Despite recent volatility in share price, Apex trades at a significant discount compared to its estimated fair value by about 87%.
- Click here to discover the nuances of Apex Mining with our detailed analytical health report.
Gain insights into Apex Mining's historical performance by reviewing our past performance report.
Henan Lingrui Pharmaceutical (SHSE:600285)
Simply Wall St Value Rating: ★★★★★★
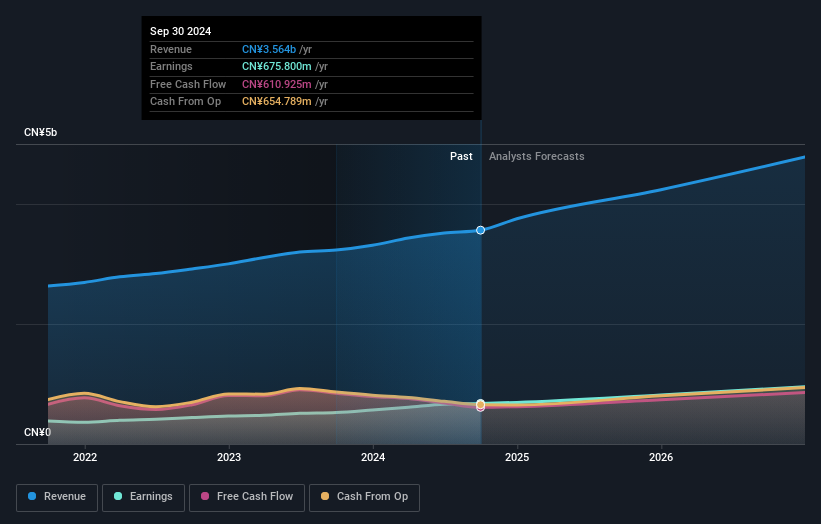
Overview: Henan Lingrui Pharmaceutical Co., Ltd. is involved in the research, development, production, and sale of drugs in China with a market capitalization of CN¥10.60 billion.
Operations: Henan Lingrui generates revenue primarily from the sale of pharmaceuticals in China. The company has a market capitalization of CN¥10.60 billion, reflecting its financial stature within the industry.
Henan Lingrui Pharmaceutical, a smaller player in the pharmaceutical industry, shows promise with its high-quality earnings and a debt-to-equity ratio that has decreased from 13.3% to 12.7% over five years. Despite recent negative earnings growth of -0.5%, it outpaces the industry average of -3%. The company's net income for the first half of 2026 was CNY 495 million, up from CNY 474 million last year, reflecting steady performance amidst challenges. Trading at an estimated 53% below fair value and maintaining more cash than total debt suggests potential for future gains as it navigates market dynamics confidently.
DoshishaLtd (TSE:7483)
Simply Wall St Value Rating: ★★★★★★
Overview: Doshisha Co., Ltd. is engaged in planning, developing, producing, and selling lifestyle-related products both in Japan and internationally, with a market capitalization of ¥108.65 billion.
Operations: Doshisha generates revenue primarily through its Development-oriented Business Model, which contributed ¥69.64 billion, and its Wholesale Type Business Model, which added ¥48.81 billion.
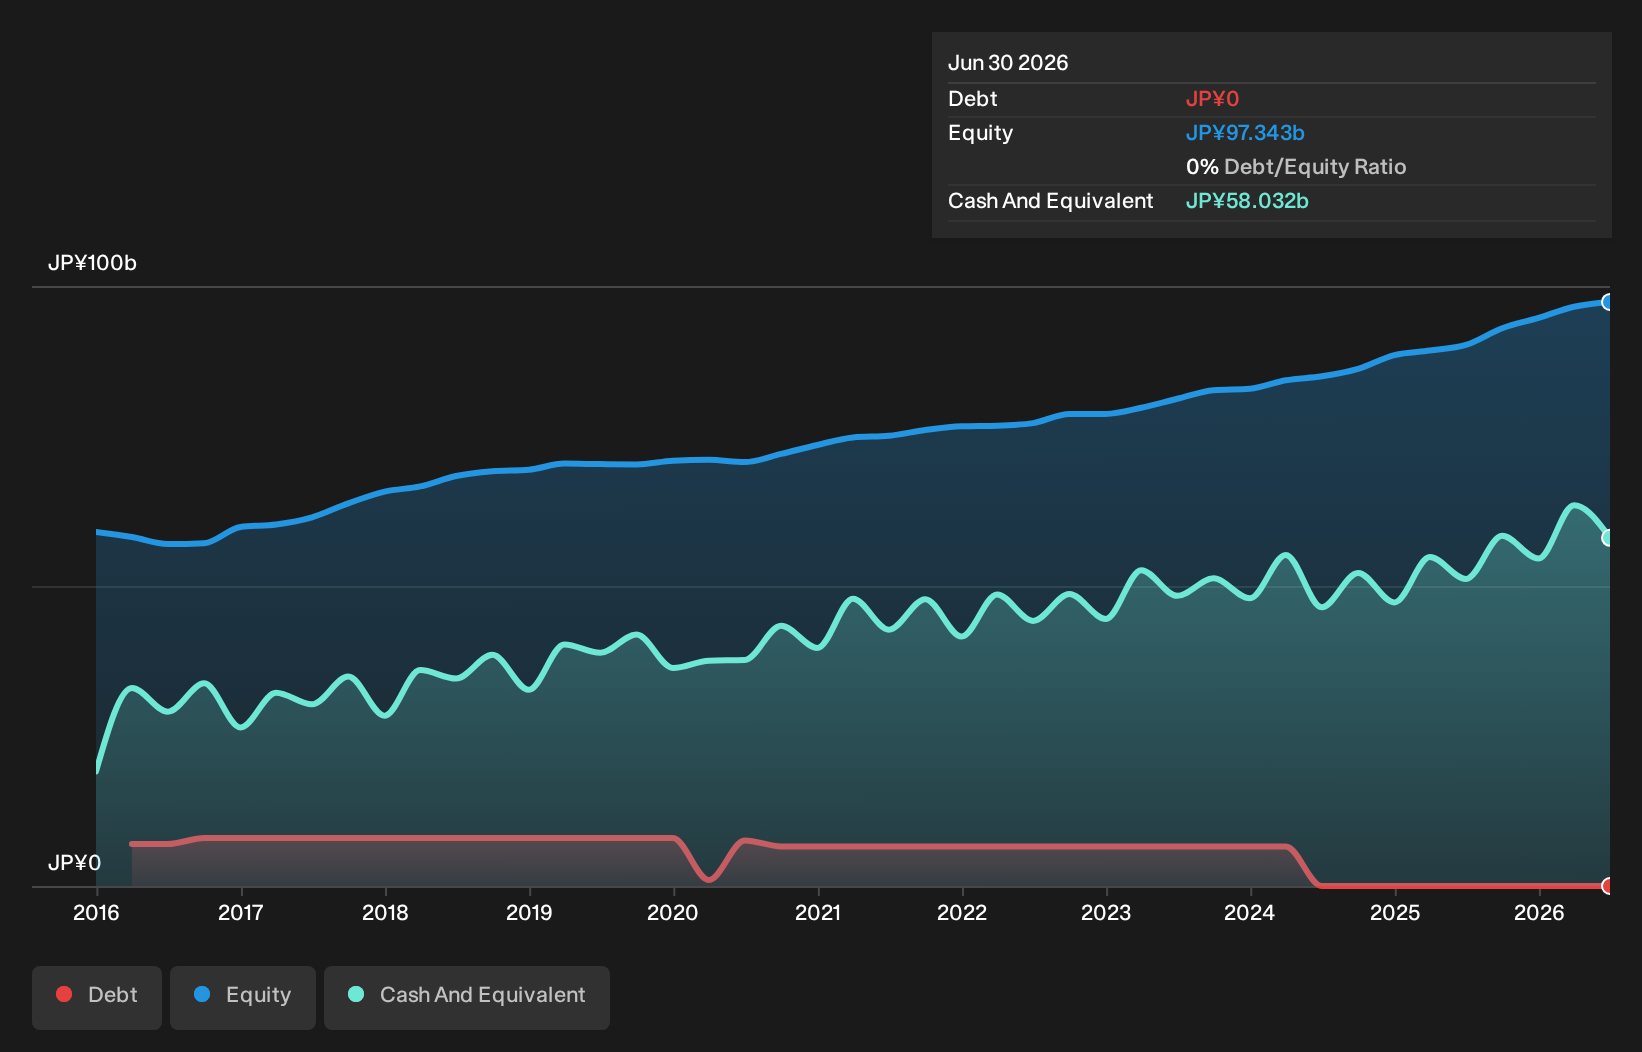
Doshisha Ltd. seems to be an intriguing prospect, trading at 67.2% below its estimated fair value, which suggests potential upside. The company is debt-free, a significant improvement from five years ago when its debt to equity ratio was 8.8%. Over the past year, earnings have grown by 22.7%, outpacing the Retail Distributors industry average of -3.4%. Recent board changes include Kiyoharu Iwamoto's appointment as Chief Logistics Officer and Takahiro Matsumoto's new role overseeing finance and trade operations, indicating a strategic focus on strengthening logistics and financial oversight for future growth prospects.
- Dive into the specifics of DoshishaLtd here with our thorough health report.
Evaluate DoshishaLtd's historical performance by accessing our past performance report.
Seize The Opportunity
- Click this link to deep-dive into the 166 companies within our Global Undiscovered Gems With Strong Fundamentals screener.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com