
CEO Resignation Probe Might Change The Case For Investing In Azenta Stock (AZTA)
- Rosen Law Firm has begun an investigation into potential securities claims on behalf of Azenta investors after former CEO John P. Marotta resigned in August 2026, focusing on whether prior business information may have been materially misleading.
- The probe puts a spotlight on Azenta's governance, disclosure quality, and leadership stability. These factors are central to how investors weigh its sample management and life sciences services opportunity against execution and legal risks.
- The next area of focus is how Azenta's broader investment narrative could be reshaped by this securities investigation tied to the CEO resignation.
Scan how other investors are positioning around governance and legal risk by reviewing our curated list of 32 resilient stocks with low risk scores that aim to keep surprises to a minimum.
Azenta Investment Narrative Recap
To own Azenta, you need to believe that sample management and multiomics services can turn current life sciences trends into steadier recurring business, despite the firm still reporting a loss of US$112.1 million on US$613.8 million of revenue. The short term swing factor remains whether customers follow through on delayed capital and services spending, which drives mix and gross profit quality.
The Rosen Law Firm investigation tied to the CEO exit mainly affects confidence in disclosures and leadership, not lab workflows or installed systems. Unless it disrupts customer relationships or slows execution on automation and outsourcing contracts, the near term operational risk still looks more about order timing, Gene Synthesis softness, and ongoing R&D and sales spend.
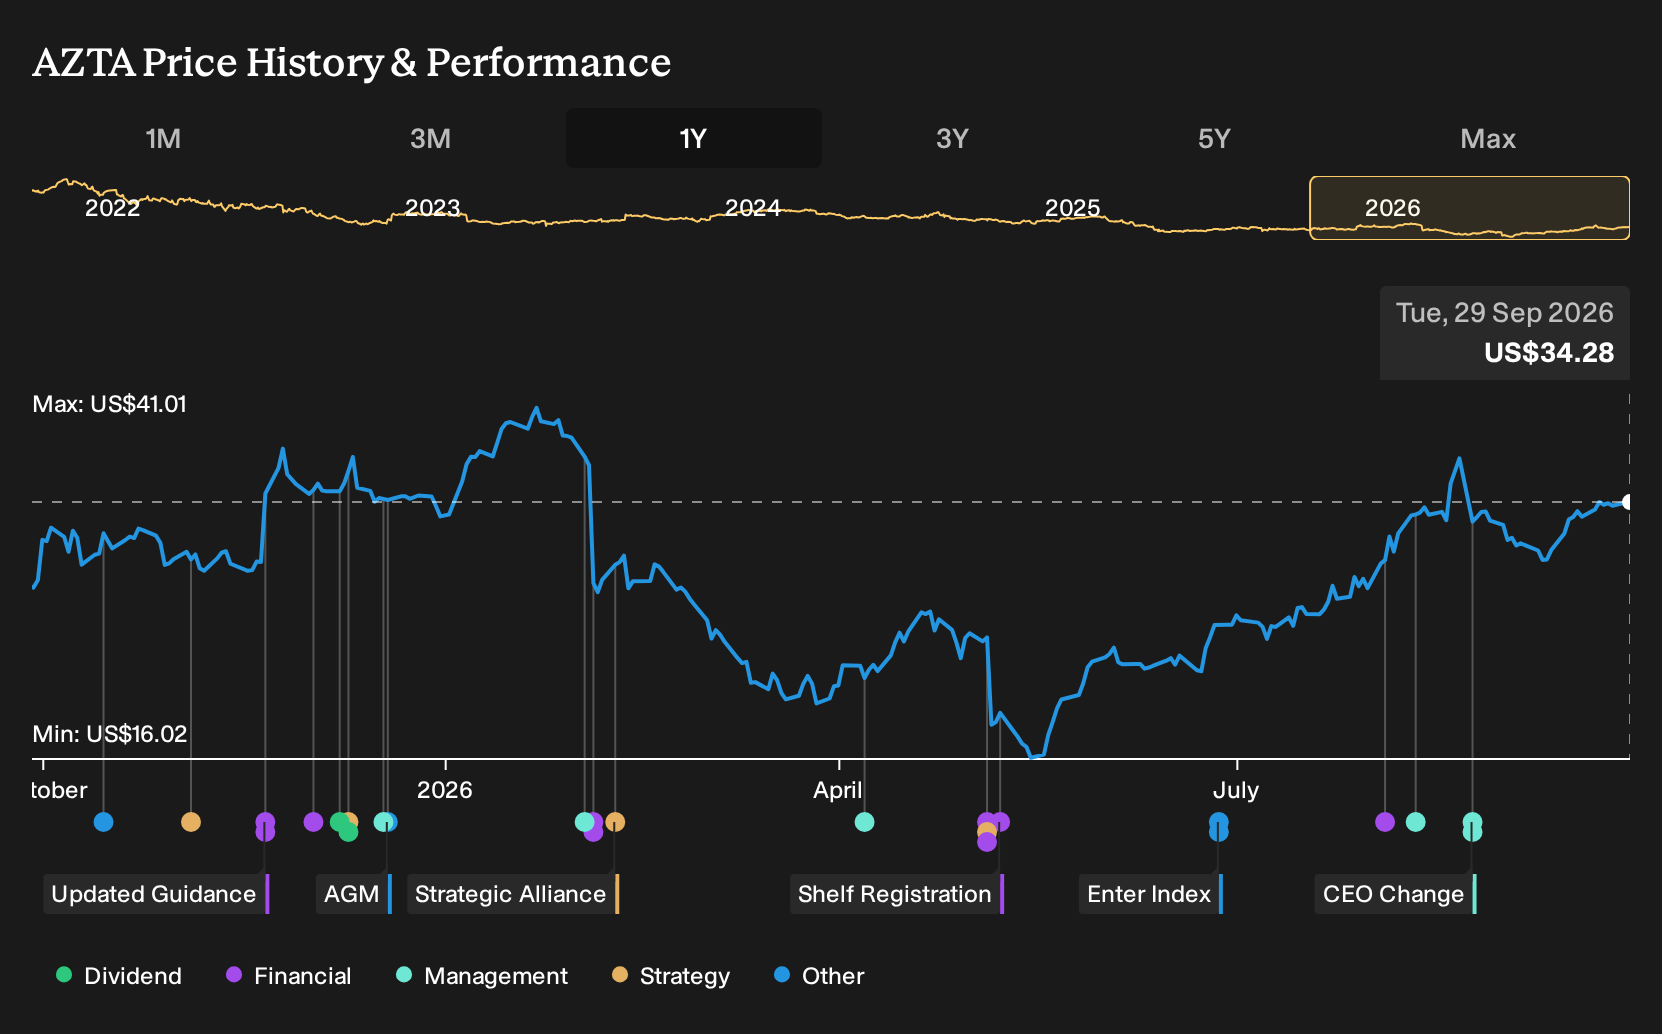
The most relevant announcement in this context is Azenta’s August 24, 2026 disclosure that CEO John P. Marotta resigned, followed by a 12% share price drop. That single event is now directly connected to the securities investigation, which puts board oversight, management depth, and communication quality under a microscope for anyone tracking the stock.
In practical terms, the resignation matters because Azenta is still investing heavily in R&D, sales coverage, automation, and biobanking capacity. Execution on those projects, while the management team has an average tenure of 1.6 years, is the real operational catalyst. Any distraction from leadership turnover or legal scrutiny could affect timing of margins, returns on that spend, and confidence in the multi year outsourcing story.
What The Azenta Forecasts Assume
Azenta's narrative projects US$692.7 million in revenue and US$29.5 million in earnings by 2029, based on analyst estimates. This implies yearly top line growth of 4.1% and an earnings swing of about US$141.6 million from the current loss of US$112.1 million to the forecast profit.
Uncover why Azenta's fair value highlights a 3% potential upside to its current price, which could narrow quickly if sentiment on Azenta turns more optimistic.
Exploring Other Perspectives
For Azenta, the contrasting catalyst is outsourcing. The most optimistic analysts were assuming revenue of about US$701.2 million and earnings of US$26.6 million by 2029, helped by heavier reliance on external lab partners. Those projections came before the CEO exit and legal probe, so you should expect opinions to evolve and to explore several viewpoints.
Explore another Azenta fair value estimate, including one that suggests it could be worth as much as $35.25.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and insights.
- A great starting point for your Azenta research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Azenta. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Azenta's overall financial health at a glance.
Looking For More Ideas Beyond Azenta?
Once you have a view on Azenta, it can help to compare that thesis with other opportunities that line up with your risk tolerance, income needs, or focus on balance sheet strength. The Simply Wall St Screener is built for exactly that kind of side by side work.
- If you want to skew toward companies with healthier finances, start with a list of solid balance sheet and fundamentals (25 results) that can help you focus on resilience and financial flexibility.
- For readers hunting for potential mispricing, filter for companies that look cheaper on fundamentals using our 32 high quality undervalued stocks and see how they stack up against your Azenta thesis.
- If steady income is part of your plan, narrow the field to higher yielding payers by reviewing our curated 6 dividend fortresses and compare those cash returns with Azenta's profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com