
Uranium Energy (UEC) Could Be 65% Undervalued After Mixed Quarterly Results
Uranium Energy (UEC) is back in focus after its latest earnings release, which paired stronger production metrics and lower unit costs with a wider quarterly loss and a sharp move in the share price.
That initial swing in Uranium Energy’s share price after the earnings headlines fits a broader pattern. The stock is down 25.1% on a 30-day share price return and 29.1% year to date, while the 1-year total shareholder return has fallen 30.4%. Yet investors who held through the last three and five years still see very large total shareholder gains of about 90% and just over 3x respectively. This points to long-term momentum that has cooled sharply in recent months as the market weighs stronger operations against a wider loss and shifting risk perceptions.
Scan how Uranium Energy stacks up against other nuclear plays by reviewing our curated list of 19 nuclear energy infrastructure stocks positioned around similar catalysts and infrastructure themes.
Bulls point to Uranium Energy’s rising production, lower costs and strong cash pile. Bears focus on the wider loss and sharp share price slide. Which story does the current valuation lean toward?
Most Popular Narrative: 65% Undervalued
The most followed fair value narrative pegs Uranium Energy at $26.56 a share, well above the last close of $9.29. This comparison frames the recent selloff against a much higher long term scenario for the business.
A multi hub in situ recovery platform across Powder River Basin, South Texas, Sweetwater and Roughrider, with several fully permitted satellite projects and new wells and header houses under construction, provides a pipeline for higher production volumes that can feed into revenue growth and operating leverage.
See why 12 investors see Uranium Energy as 65% undervalued.
Result: Fair Value of $26.56 (UNDERVALUED)
However, Uranium Energy’s unhedged uranium exposure and execution risk around its new refining and conversion venture could both weaken the bullish fair value story if progress disappoints.
Find out about the key risks to this Uranium Energy narrative.
Another View on Uranium Energy’s Valuation
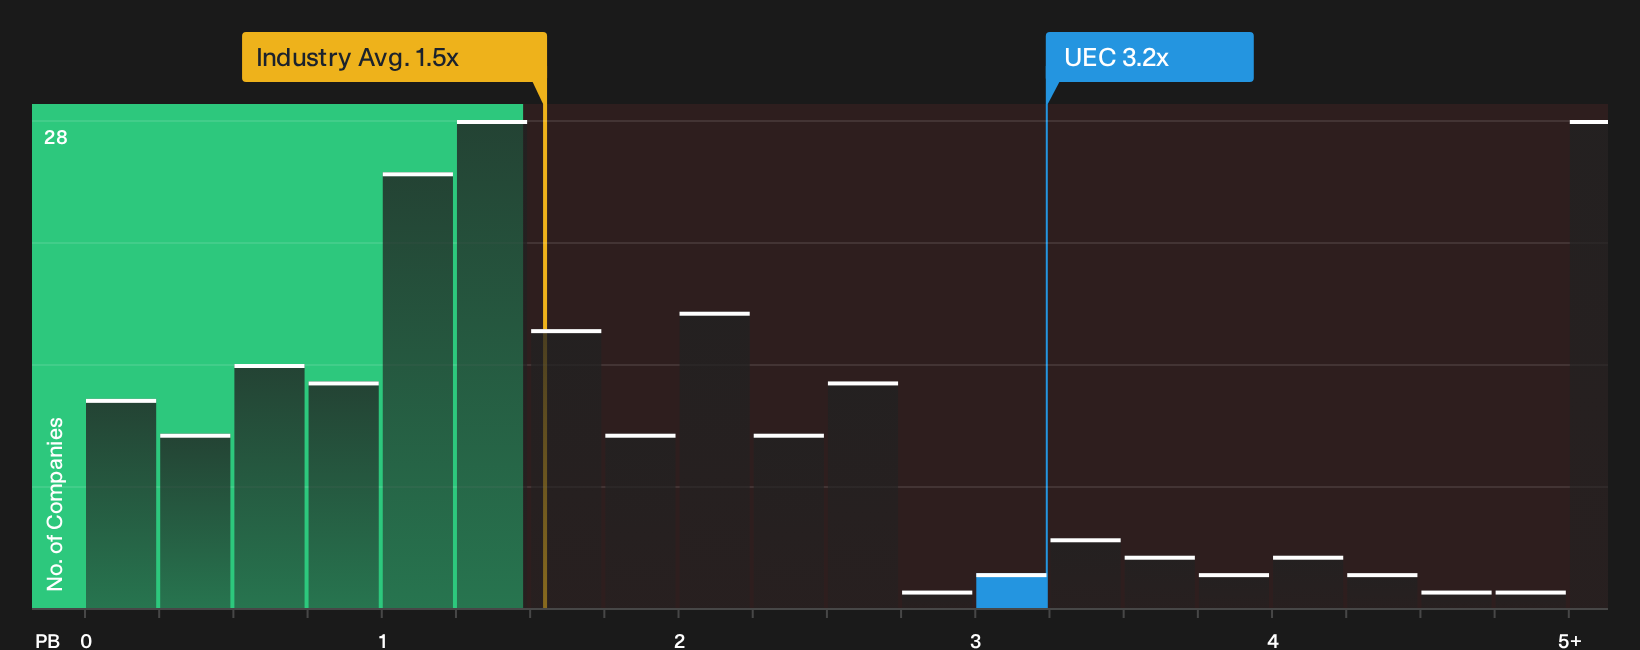
The first fair value story for Uranium Energy leans heavily on bullish analyst forecasts. A simpler cross check comes from its P/B ratio of 3.2x, which sits well above the US Oil and Gas peer average of 1.5x. That premium suggests investors are already paying up, so how comfortable are you with the gap?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Uranium Energy is clearly split, with both risk and reward on the table, so move quickly and stress test the numbers yourself. To help frame that view alongside market concerns and potential upside, review the 1 key reward and 1 important warning sign
Looking For More Uranium Energy Style Ideas?
If Uranium Energy has you rethinking your watchlist, do not stop at a single ticker. Broaden your opportunity set by scanning other focused stock ideas that match your own risk and return preferences.
- Target potential mispricings across the market by reviewing our curated set of 32 high quality undervalued stocks that combine quality fundamentals with discounted valuations.
- Prioritise resilience and capital strength by screening a list of solid balance sheet and fundamentals (25 results) so you can focus on businesses with sturdier financial footing.
- Get ahead of the crowd by scanning 17 high quality undiscovered gems that pair strong fundamentals with limited current market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com