
Learn Why The Bull Case For Enphase Energy Stock Could Change Following Utility Approval
- Enphase Energy reported that its IQ Meter Collar is now approved for behind the meter installation by 80 utilities serving more than 38 million customers across the United States and Canada, including all three major investor owned utilities in California and SMUD, with Hawaiian Electric pilots underway.
- This wide utility acceptance for a behind the meter interconnection device that simplifies whole home backup and reduces installation complexity speaks directly to Enphase Energy's push to make its integrated solar and storage systems easier for installers to deploy at scale.
- We will now look at how Enphase Energy's broad utility approval for the IQ Meter Collar could reshape the investment narrative.
Scan 39 power grid technology and infrastructure stocks that, like Enphase Energy, could benefit as utilities roll out more grid friendly hardware and accelerate whole home backup adoption across North America.
Enphase Energy Investment Narrative Recap
To own Enphase Energy, you need to believe that home solar plus storage keeps getting more integrated, easier to install, and more attractive to utilities as a grid resource. The IQ Meter Collar approvals point directly in that direction of travel. In the near term, the key swing factor remains demand recovery against a U.S. residential market that could contract if tax credits roll off.
The biggest near-term risk is still softer residential volumes and elevated channel inventory rather than this single product update. If installers work through stock slowly, Enphase could experience continued pricing and margin pressure, especially with tariffs already trimming gross margin. The collar win helps expand the toolkit. It does not erase those headwinds.
The IQ Meter Collar sits alongside the IQ Battery 10C and IQ Combiner 6C in Enphase Energy's fourth-generation system, so this regulatory green light connects directly to the broader product roadmap. Utility approval for a behind-the-meter device that avoids sub panels and extra hardware gives the whole package more operational appeal for electricians trying to get through more jobs per day.
That matters for the current catalyst, which is whether new hardware and software platforms can offset slower U.S. residential demand and tariff pressure. Faster installs and fewer truck rolls can help installers prioritize Enphase over rivals, which may support volume and help manage inventory overhang. Execution risk on the wider product slate remains, but this announcement points to improvement on the deployment side rather than deterioration.
Enphase Energy's narrative projects US$1.4b revenue and US$283.1 million earnings by 2029. This is based on an assumed 2.5% yearly revenue growth and an earnings increase of about US$149.1 million from US$134.0 million today.
Uncover why Enphase Energy's fair value indicates a 67% potential upside to its current price, which could narrow quickly.
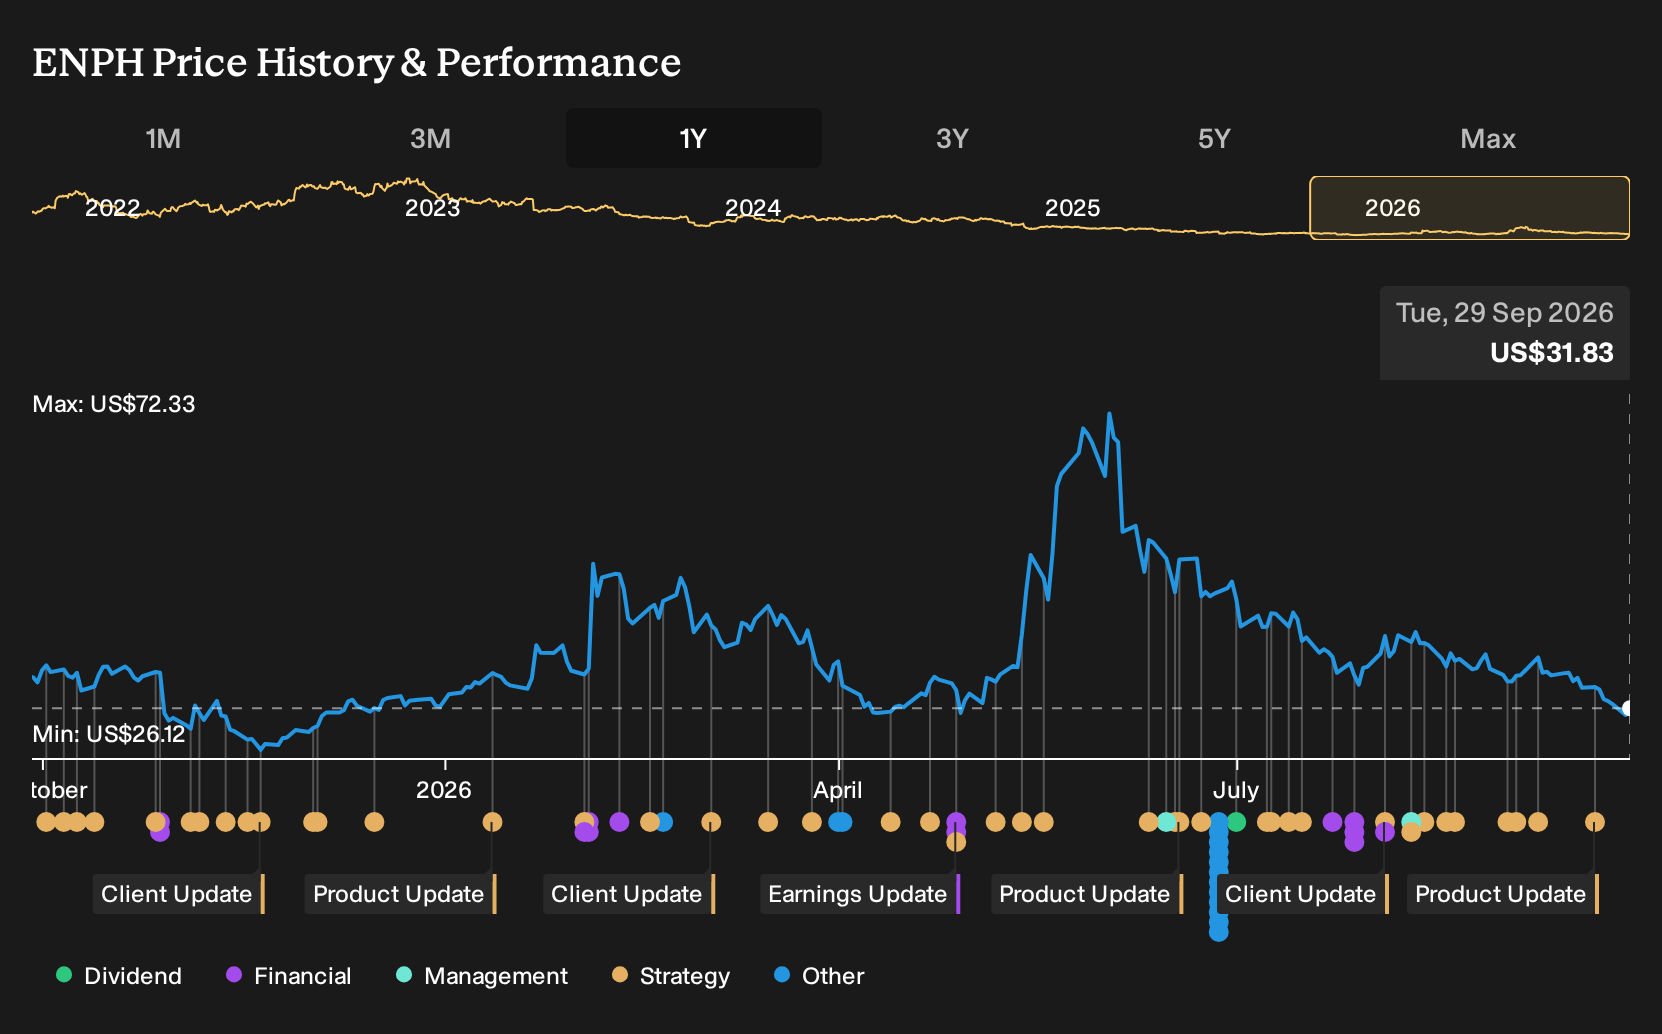
Exploring Other Perspectives
The lowest analysts on Enphase Energy lean hard into market saturation risk. They were modelling revenue drifting to about US$1.2b by 2029 with earnings near US$84.7 million, versus the consensus US$283.1 million. That is a very different story. This IQ Meter Collar news could encourage some of those views to shift, so explore both sides.
Explore 4 other Enphase Energy fair value estimates, including one that suggests it could be worth just $33.60.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Enphase Energy research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Enphase Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enphase Energy's overall financial health at a glance.
Looking for more investment ideas beyond Enphase Energy?
If the Enphase Energy story has sharpened your view on energy transition, use that same lens to scan other opportunities where fundamentals, balance sheets, and income potential line up with your own risk tolerance.
- For investors who want clear value with quality at the core, start by reviewing a 32 high quality undervalued stocks that fit strict cash flow and balance sheet checks.
- If capital preservation sits high on your priority list, narrow your search to a 32 resilient stocks with low risk scores so you can focus on resilience first and upside second.
- When you want to move earlier in the story without abandoning fundamentals, turn to a 17 high quality undiscovered gems that may not yet be widely followed but still pass key financial filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com