
Is WSFS Financial (WSFS) Fairly Valued After Its Lancaster Expansion?
WSFS Financial (WSFS) is expanding its regional footprint by opening a new office in Lancaster, Pennsylvania. The location brings wealth management, private banking, lending and small business support together under one roof for local clients.
Recent trading has cooled slightly, with the WSFS Financial share price down 3.1% over the past month and 3.4% over 90 days, even though the year to date share price return is 37.8% and the 3 year total shareholder return is 119.6%. Investors may see the Lancaster and prior Doylestown expansions as part of a longer regional growth story, which could be influencing how the market weighs that strong multi year total shareholder return against shorter term share price softness.
Scan for other regional banks taking similar growth swings as WSFS Financial by checking out our hand picked list of solid balance sheet and fundamentals (25 results) that are also leaning into expansion and balance sheet strength.
WSFS Financial has rallied hard over three years, yet the shares now trade below both analyst targets and one intrinsic value estimate. Is that gap a safety margin or a warning sign as the valuation work starts?
Most Popular Narrative: 14.7% Undervalued
WSFS Financial closed at $75.84, while the most followed narrative pegs fair value at $88.92 using a 7.24% discount rate. That gap frames a story built around fee income, regional expansion, and how much investors are willing to pay for those traits.
Strategic growth through targeted M&A and organic expansion, especially in wealth management and trust services, is increasing fee-based, less rate-sensitive income streams. This is described as leading to improved earnings stability and higher return on equity in both stable and volatile rate environments. Robust capital generation (supporting aggressive buybacks) and a disciplined approach to acquisitions are cited as reasons WSFS can capitalize on potential industry consolidation and scale advantages, which in turn is expected to boost earnings per share while maintaining a strong CET1 ratio and financial flexibility for future investment opportunities.
See why 0 investors see WSFS Financial as 15% undervalued.
Result: Fair Value of $88.92 (UNDERVALUED)
Still, the WSFS Financial story could look very different if Mid Atlantic conditions weaken, or if deal and integration execution drags on margins and growth.
Find out about the key risks to this WSFS Financial narrative.
Another View: WSFS Financial Through A P/E Lens
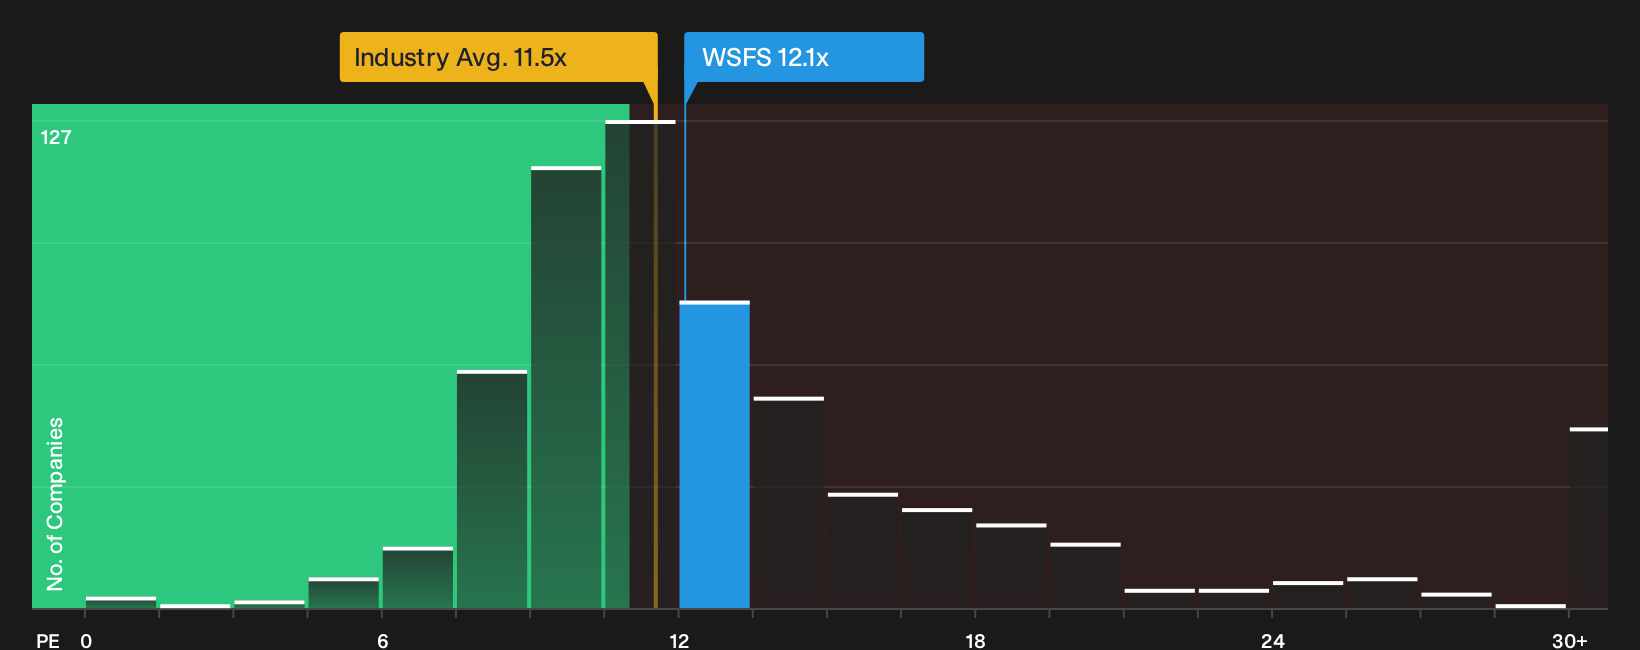
There is a twist when the focus shifts from intrinsic value to simple market ratios. WSFS Financial trades on a P/E of 12.1x. That is slightly above the US banks group at 11.6x, yet just over the 11x fair ratio implied by the regression model.
In practice, that means the stock carries a small premium to the wider sector, while only modestly above the level the fair ratio suggests the market could move toward over time. The question for you is whether the earnings quality and fee mix justify paying that extra turn on the multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around WSFS Financial can feel messy, so move quickly, pull up the numbers, and decide where you land on 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond WSFS Financial?
If WSFS Financial has caught your attention, do not stop there. Use the screeners below to line up your next watchlist candidates before the crowd moves.
- Target potential mispricing opportunities by scanning 32 high quality undervalued stocks that combine solid fundamentals with what some investors may view as attractive entry points.
- Build more resilient income streams by focusing on 6 dividend fortresses that aim to balance higher yields with balance sheet strength.
- Reduce portfolio stress by concentrating on 32 resilient stocks with low risk scores that score well on financial health and volatility checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com