
Dividend Strength Might Change The Case For Investing In Associated Banc Corp Stock
- Recent commentary on Associated Banc-Corp highlights its relatively high dividend yield versus peers, supported by consistent payouts and a payout ratio described as manageable for current earnings.
- The focus on dividend income positions Associated Banc-Corp as a candidate for investors prioritizing regular cash returns from a regional banking franchise.
- We will now examine how Associated Banc-Corp's investment narrative may be influenced by the focus on its dividend yield strength.
Scan beyond Associated Banc-Corp and compare its income profile with a hand picked group of 6 dividend fortresses built for investors who care about reliable cash returns.
Associated Banc-Corp Investment Narrative Recap
To own Associated Banc-Corp, you need to be comfortable with a regional lender that leans into commercial and CRE relationships while relying on steady deposit inflows and disciplined costs. The key near term positive driver is management’s push for higher yielding lending and ongoing digital and efficiency work. The latest focus on dividend strength does not materially change that operating story.
The biggest near term risk sits in credit and funding. A heavier tilt toward commercial and CRE loans leaves earnings more exposed if regional conditions weaken. At the same time, the business depends on continued deposit growth in a competitive market for funding, which could pressure margins if customer behavior shifts.
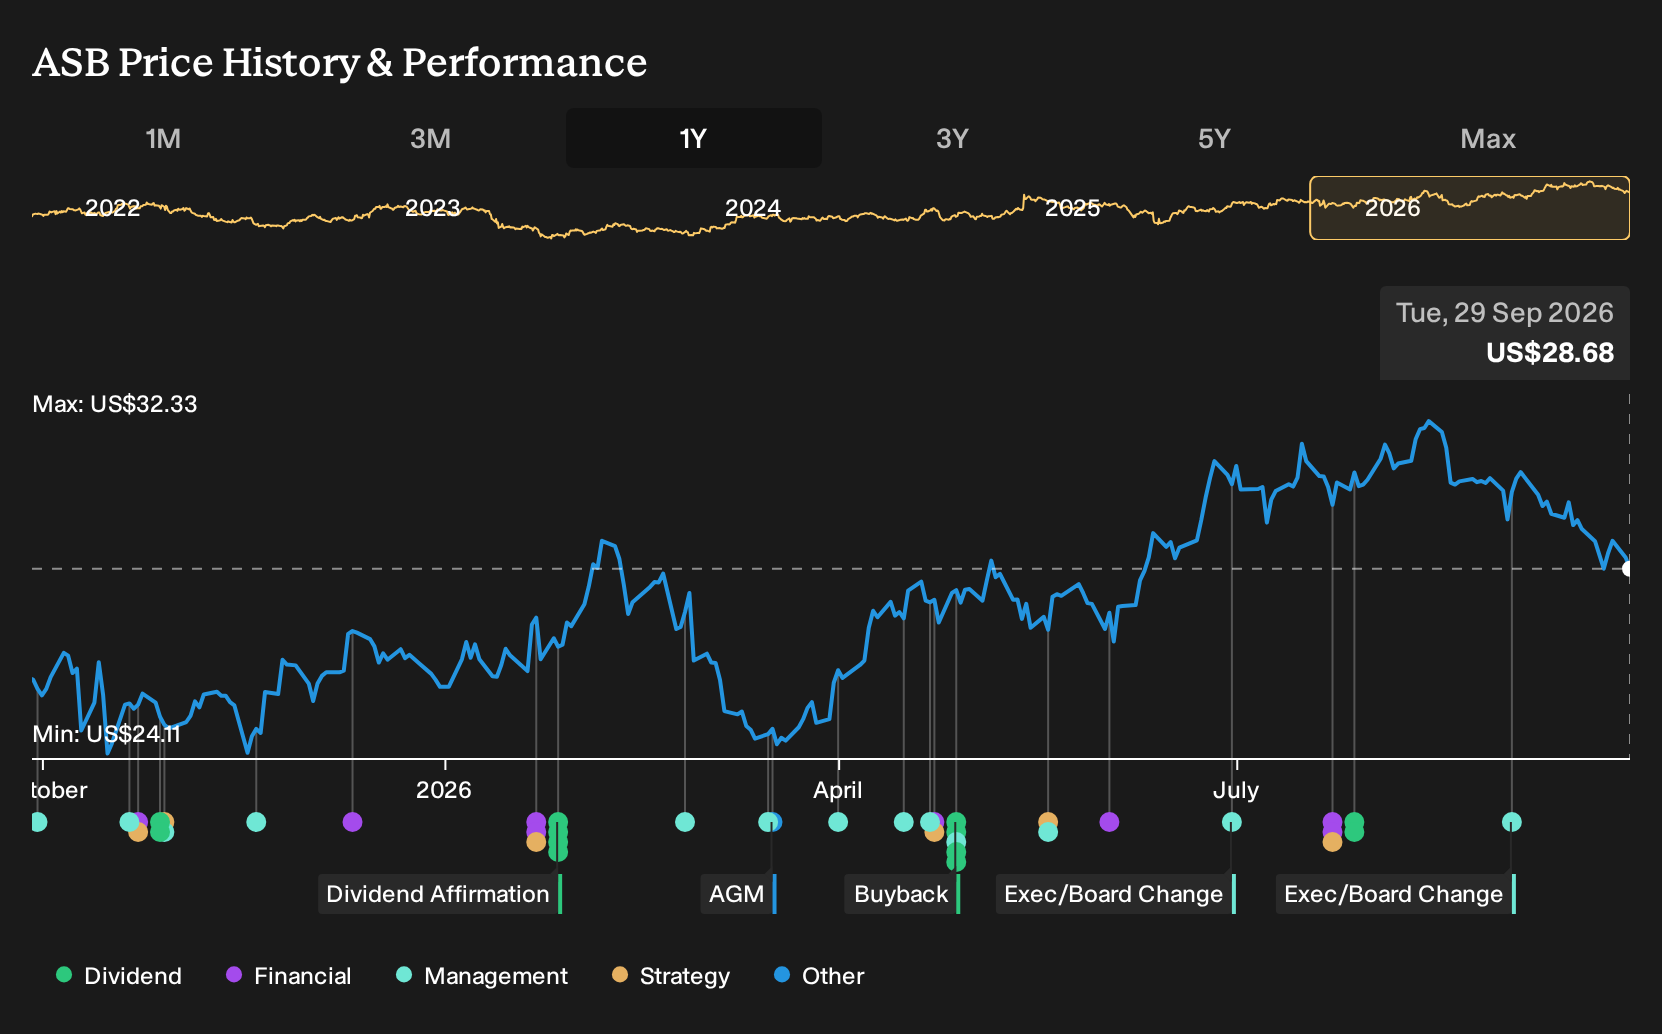
Recent discussion around Associated Banc-Corp’s dividend puts the payout at the center of the investment case. The bank currently pays a dividend yield of 3.35%, backed by what is described as a manageable payout ratio and earnings that analysts expect to grow, although not at very high rates.
That income profile ties directly into the main catalysts. Analysts see earnings expanding around 12.6% per year and net profit margins at 31.6%, which is cited as supporting ongoing distributions if execution on lending mix, deposits, and efficiency continues. For you as an income focused holder, the operational question is whether those drivers are durable enough to keep funding that dividend over time.
What the earnings path implies for Associated Banc-Corp
Associated Banc-Corp's current dividend story plugs directly into a set of explicit analyst assumptions on revenue and profit. Those estimates sketch out what would need to happen in the financials for the income stream to keep looking secure on paper.
Analysts are working off revenue that is expected to rise by 11.8% a year over the next three years, with profit margins moving from 31.6% today to 32.0% by 2029. Earnings are modeled to move from US$491.3 million today to US$696.2 million by 2029, which is an increase of about 42%. On those figures, the consensus view has Associated Banc-Corp generating about US$2.2b of revenue and US$696.2 million of earnings in 2029.
Uncover why Associated Banc-Corp's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster between US$33.56 and US$53.24, so some private investors see Associated Banc-Corp priced much richer than others. That split sits alongside a story of higher yielding commercial and CRE lending, plus funding and regulatory risks, giving you clear reasons to compare multiple viewpoints before deciding.
Explore another Associated Banc-Corp fair value estimate, including one that suggests it could be worth just $33.56.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Associated Banc-Corp research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Associated Banc-Corp. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Associated Banc-Corp's overall financial health at a glance.
Looking for more investment ideas beyond Associated Banc-Corp?
Once you have a view on Associated Banc-Corp, it can help to widen the lens and compare it with other opportunities that fit your income, quality, or risk profile using the Simply Wall St Screener.
- For investors who want smaller companies with upside potential but still care about balance sheet strength, scan through 9 elite penny stocks with strong financials and see which ones merit a place on your watchlist.
- If your priority is cushioning downside risk while still staying in equities, consider filtering for 32 resilient stocks with low risk scores that may better match your tolerance for volatility.
- Those hunting for high quality businesses with solid fundamentals that are not yet widely followed can review the 17 high quality undiscovered gems and build a shortlist worth deeper research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com