
Should Chip Sector Weakness Require Action From Hua Hong Grace Semiconductor Stock Investors?
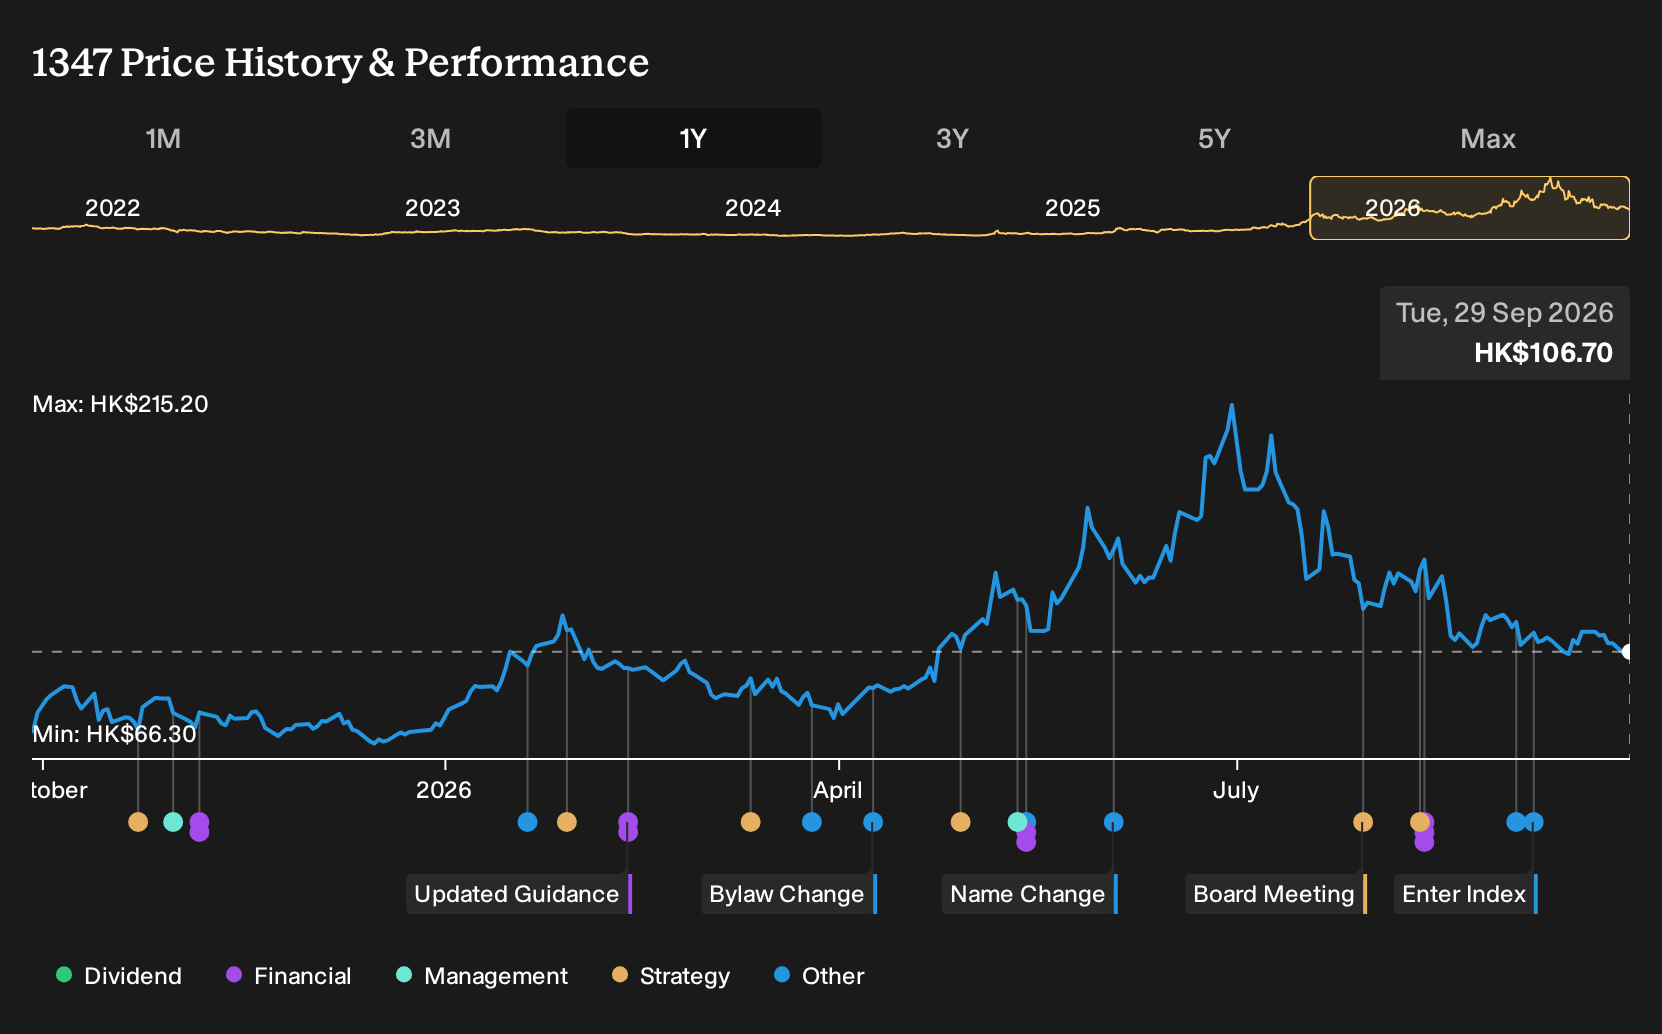
- Hua Hong Grace Semiconductor's shares fell in recent Hong Kong trading, in line with broader weakness in chip stocks, with no new company specific developments reported.
- The sector wide setback highlights how Hua Hong Grace Semiconductor's valuation and funding intensive expansion plans remain heavily exposed to shifts in sentiment toward semiconductor demand and capacity.
- We now look at how Hua Hong Grace Semiconductor's investment narrative is affected by sector wide chip weakness and sentiment driven pressure.
Hua Hong Grace Semiconductor Investment Narrative Recap
For Hua Hong Grace Semiconductor, the key consideration is whether demand from areas such as AI related chips, EVs and industrial control can continue to fill its mature node and specialty capacity as new fabs ramp. The sector pullback and the 4.6% drop in the latest session mainly affected sentiment rather than the nuts and bolts of operations.
The near term swing factor remains how smoothly Fab9 and other expansion plans ramp without creating idle capacity that weighs on margins and cash flow. A key risk at this stage is that heavy capex and a concentrated China revenue base meet softer orders, which could turn the current growth build out into a profitability headwind.
With no fresh company specific announcement directly linked to the latest share move, the most relevant reference point is still the broader expansion and capacity plans that management has outlined around Fab9 and the targeted new fab for 2027. These projects shape how to think about both the current sell off and any potential recovery in chip demand.
Those build outs require sustained investment and leave Hua Hong Grace Semiconductor exposed if utilization eases or pricing weakens. They are also central to the current catalysts that analysts focus on, including expectations around earnings and margin trends, while amplifying key risks such as high capital intensity, potential overcapacity and reliance on domestic policy support.
Hua Hong Grace Semiconductor is currently modeled on a relatively punchy set of assumptions. Analysts are baking in revenue growth of 19.0% per year and see earnings moving from $102.7 million today to $452.3 million by 2029, which implies roughly a 4x increase in profit from current levels. On those forecasts, the business would be generating about $4.5 billion of revenue and $452.3 million of earnings in 2029.
Uncover why Hua Hong Grace Semiconductor's fair value indicates a 35% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative angle on Hua Hong Grace Semiconductor focuses on capacity utilization as a positive catalyst rather than a risk. The most optimistic analysts were already pencilling in revenue of about $5.7b and earnings of $566.7 million by 2029 before this chip led pullback. That is a far brighter scenario than consensus. The latest sector slump may prompt you to revisit both stories and decide which assumptions feel closer to your own view.
Explore 4 other Hua Hong Grace Semiconductor fair value estimates, including one that suggests as much as 158% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hua Hong Grace Semiconductor research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hua Hong Grace Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hua Hong Grace Semiconductor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Hua Hong Grace Semiconductor?
If Hua Hong Grace Semiconductor has you rethinking your chip exposure, it can help to widen the lens and see how other businesses stack up on quality, valuation and resilience using the Simply Wall St Screener.
- For investors who want potential value combined with quality fundamentals, consider scanning through a curated set of 198 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you than high octane growth, filter for 226 resilient stocks with low risk scores that may better fit that brief.
- When you want to go beyond the usual tickers and uncover lesser known stories with solid metrics, sort through our 620 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com