
Learn Why The Bull Case For Descartes Systems Group (TSX:DSG) Could Change Following AI Trade Tool Launch
- Descartes Systems Group recently introduced the Descartes Datamyne AI Agent, a conversational tool built into its global trade intelligence platform that uses natural-language queries, visualizations and shipment records to help sourcing, sales, supply chain and market intelligence teams cut research time on more than 500 million annual shipment records across 230 markets.
- The launch points to a push by Descartes Systems Group to turn complex trade data into faster, decision-ready outputs for customers, which could influence how users approach supplier discovery, competitor tracking and trade risk assessment inside existing workflows.
- We will now see how Descartes Systems Group's investment narrative could be affected by this new Datamyne AI Agent capability.
Scan how Descartes Systems Group fits into the broader AI supply chain trend by reviewing a curated short list of 88 AI infrastructure stocks that could be building similar data-driven advantages.
Descartes Systems Group Investment Narrative Recap
To own Descartes Systems Group, you need to believe that rising global trade complexity, e commerce and logistics automation will keep pulling more customers into its logistics technology platform and data products. The Datamyne AI Agent fits that thesis by trying to make a very large trade data set more usable, which could support customer retention and broader adoption if it executes well.
In the near term, the key swing factor is how consistently Descartes can turn that demand backdrop into higher organic services revenue, not just acquisition led expansion, while managing softer freight and trucking volumes in some markets. The biggest operational risk is competitive pressure from other logistics and AI focused providers, which could compress pricing and slow wins if the Datamyne AI Agent and related tools fail to differentiate meaningfully.
The Datamyne AI Agent launch is the announcement that matters most for this update. It directly targets a risk in the story that global trade intelligence becomes more crowded and price competitive. By giving sourcing and compliance teams natural language access to 500 million shipment records a year, Descartes Systems Group is trying to keep its data product central to customer workflows.
For catalysts, this tool is closely tied to the idea that recurring services revenue can expand as trade rules grow more complex and e commerce volumes require better visibility. If the AI Agent helps customers identify suppliers, track competitors and assess trade risks inside the same environment, that can support cross sell into routing, transportation management and customs solutions, while still leaving Descartes exposed to swings in global trade policy and logistics activity.
Descartes Systems Group's current narrative assumes revenue growth of 11.3% per year and points to earnings today of $163.8 million and a consensus forecast of $275.4 million by 2029. That implies an earnings increase of about $111.6 million over the period.
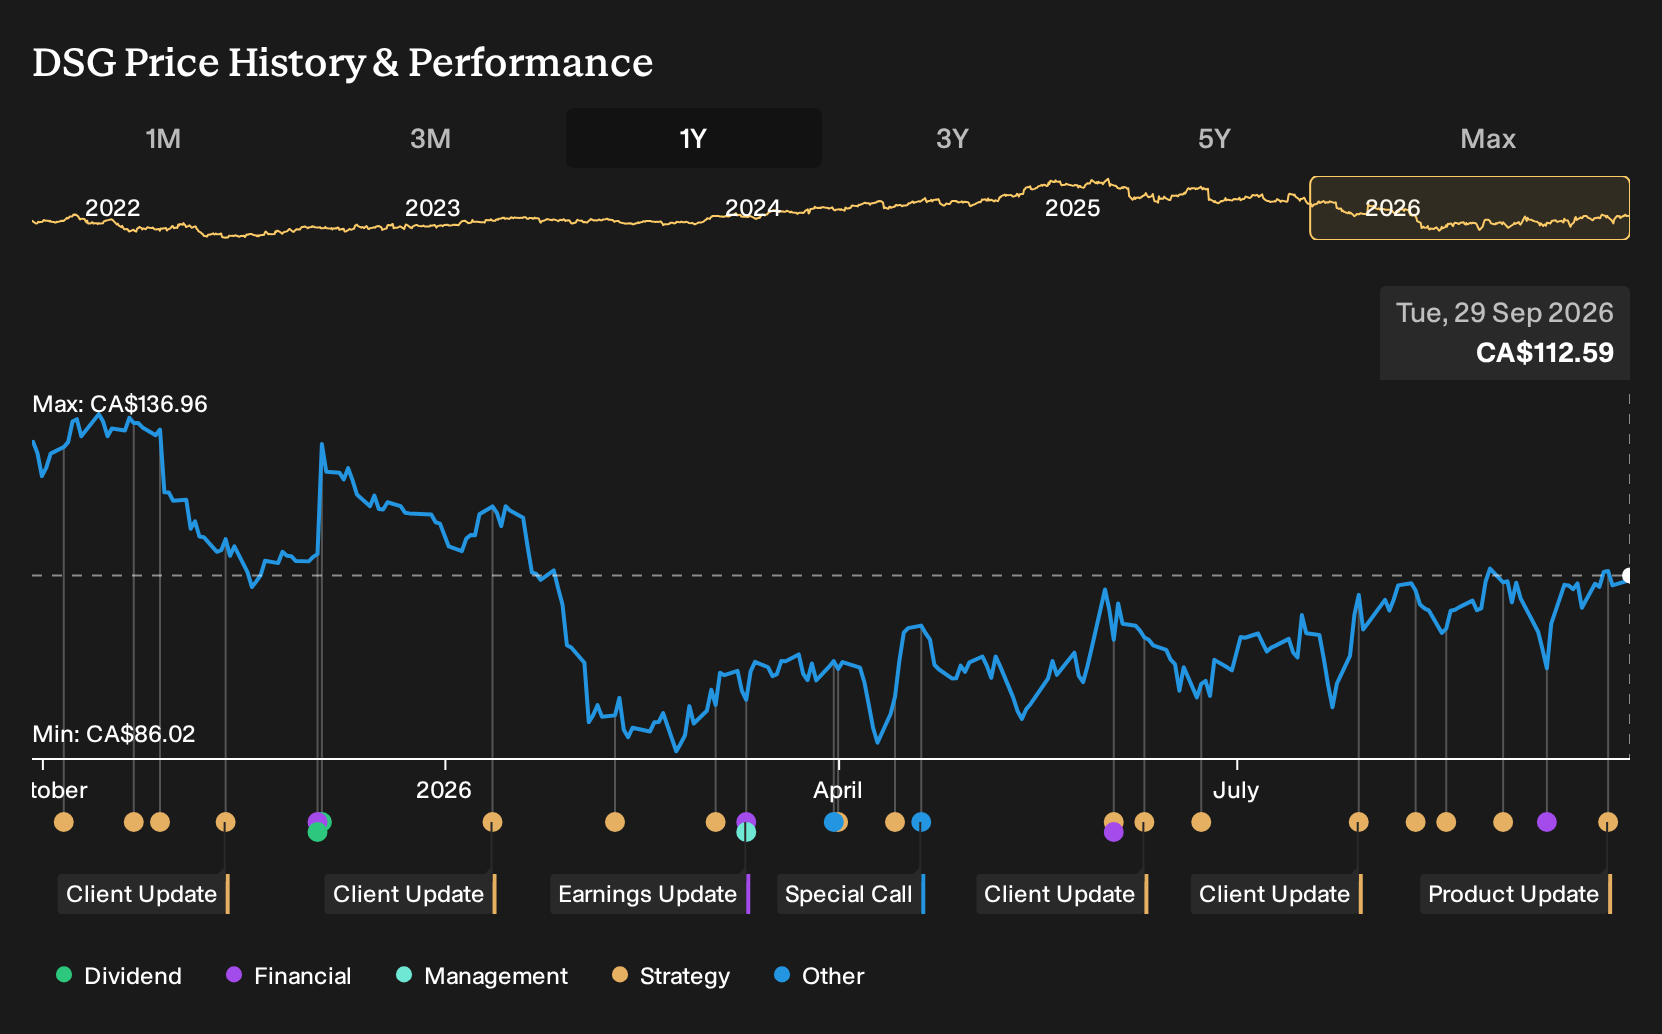
Uncover why Descartes Systems Group's fair value indicates a 14% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community cluster between about US$128 and US$160, so even this small sample of retail views shows a meaningful spread in what Descartes Systems Group might be worth. Compare those opinions with the new Datamyne AI Agent rollout and multiple upcoming conference appearances, then decide which scenarios you find most convincing.
Explore 2 other Descartes Systems Group fair value estimates, including one that suggests as much as 42% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Descartes Systems Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Descartes Systems Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Descartes Systems Group's overall financial health at a glance.
Looking for more Descartes Systems Group style ideas?
If the Descartes Systems Group story has you thinking about where else technology, data and resilient cash flows might intersect, it can help to widen the lens with a few targeted screens on Simply Wall St.
- For investors who care most about balance sheet strength, start with companies highlighted in our list of solid balance sheet and fundamentals (7 results) and see which ones match your risk tolerance.
- If stability with income is a priority, review a curated set of businesses in the 1 dividend fortresses and compare their payout profiles and fundamentals side by side.
- To hunt for under-the-radar opportunities with strong underlying metrics, scan the 9 high quality undiscovered gems and build a watchlist tailored to your own thesis.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com