
What DNOW Stock Lawsuit Means For Shareholders
- DNOW recently faced a securities class action lawsuit alleging misleading disclosures around its merger with MRC Global, including issues tied to implementing a new enterprise resource planning system, and it had previously presented at the Water Tower Research Virtual Insights Conference in September 2026.
- The litigation focus on merger communications and ERP execution places DNOW's integration capabilities, cost discipline, and operational reliability under a sharper spotlight for investors assessing its fundamentals.
- We will now assess how DNOW's investment narrative could shift as merger disclosure litigation raises fresh questions about integration and execution.
Broaden your watchlist beyond DNOW by scanning a curated set of 32 resilient stocks with low risk scores that put balance-sheet strength and execution quality front and center.
DNOW Investment Narrative Recap
To own DNOW, you need to be comfortable with an energy focused distributor that is currently unprofitable but aiming for improved earnings, helped by digital tools and international exposure. The key near term catalyst remains execution on integration, systems and service quality, since that is what underpins volumes and pricing power across upstream, midstream and industrial customers.
The lawsuit around the MRC Global merger and ERP rollout concentrates attention on that same execution question. If ERP and merger integration disrupt ordering, inventory or delivery, the biggest operational risk right now is service reliability. If the litigation proves more procedural than operational, the impact on short term business drivers may be limited.
The Water Tower Research Virtual Insights Conference on 22 September 2026 matters here because it gives DNOW a forum to address precisely these concerns. You can watch for how management talks about ERP stability, customer service levels and integration milestones to gauge whether the operational story still lines up with the equity case.
Any update around cash generation, balance sheet strength and spending priorities at that event also ties back into catalysts. A distributor with US$4.1b of revenue, no debt and a focus on energy transition products has options, but the lawsuit and ERP issues put a premium on clean execution and tight cost control before those options translate into better outcomes.
What The Current DNOW Forecasts Assume
DNOW's narrative projects US$5.8b revenue and US$205.7m earnings by 2029. This rests on analysts assuming 12.5% yearly revenue growth and an earnings swing of about US$393.7m, from a loss of US$188.0m today to the 2029 consensus level.
Uncover why DNOW's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
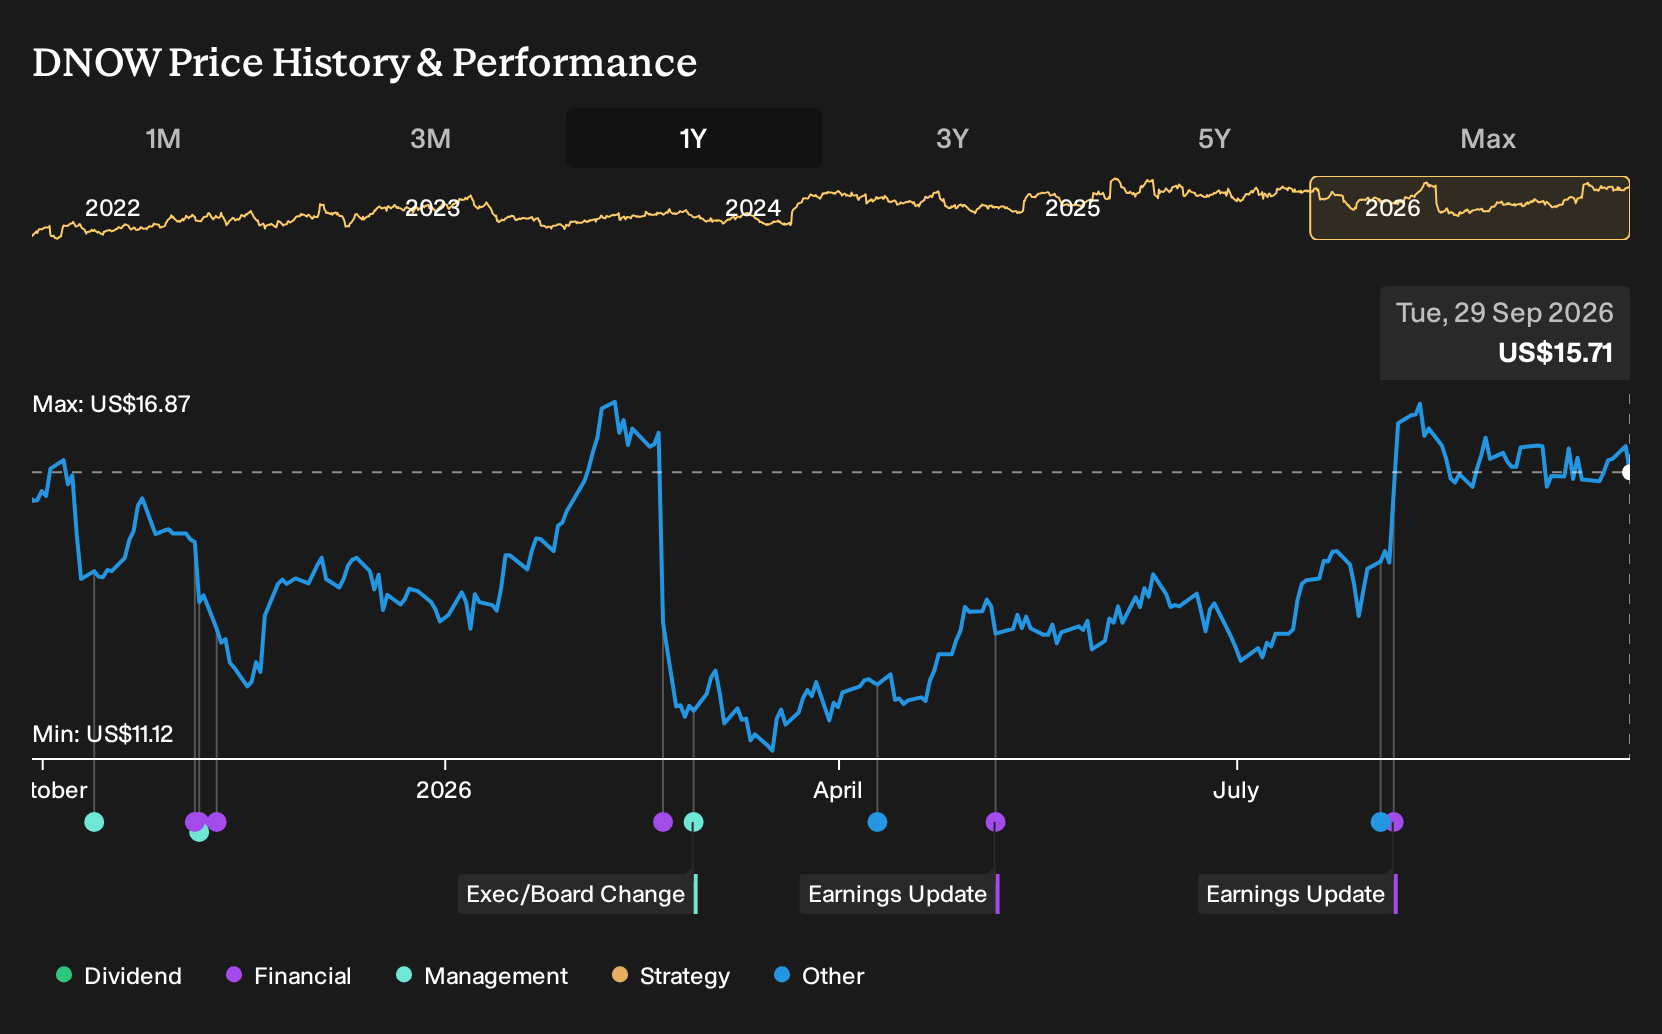
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$18.75 and about US$24.13, which already span a wide gap for DNOW even before the lawsuit and ERP issues are factored in. Read these views as a starting grid. Opinions clearly diverge; explore multiple angles before judging how the merger and legal overhang could shape DNOW's outcomes.
Explore 2 other DNOW fair value estimates, including one that suggests it could be worth just $18.75.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DNOW research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for DNOW. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DNOW's overall financial health at a glance.
Looking For More Ideas Beyond DNOW?
If the DNOW story has you reassessing risk, balance sheets and future potential, it can help to compare it with other candidates that share some of the qualities you care about. The Simply Wall St Screener lets you filter for those traits directly so you can build a watchlist that fits your own risk and return preferences.
- Prioritise resilience first by reviewing a 32 resilient stocks with low risk scores to help keep volatility and fundamental risk scores in check.
- If value is your focus, scan a 32 high quality undervalued stocks that blends strong cash generation with balance sheet support.
- For investors who like overlooked stories, take a look at a 17 high quality undiscovered gems that pairs quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com