
Will New AI Integrations Change ZoomInfo Technologies' (GTM) Narrative
- Recent announcements from ZoomInfo Technologies include a Superhuman Go connector, a Replit integration for ZoomInfo MCP, and the launch of Talent Autopilot for recruiters, all now live and tied into its GTM.AI context layer and governance controls.
- These additions deepen ZoomInfo Technologies' reach into everyday productivity and developer tools, which could reinforce its role as embedded go to market infrastructure across sales, marketing, and recruiting workflows.
- We will look at how ZoomInfo Technologies' expanding GTM.AI integrations, including Superhuman Go, may influence the existing investment narrative around AI adoption.
Scan how ZoomInfo Technologies fits into the broader AI buildout by comparing it against a curated list of 88 AI infrastructure stocks powering tools such as sales agents, copilots, and data rich workflows.
ZoomInfo Technologies Investment Narrative Recap
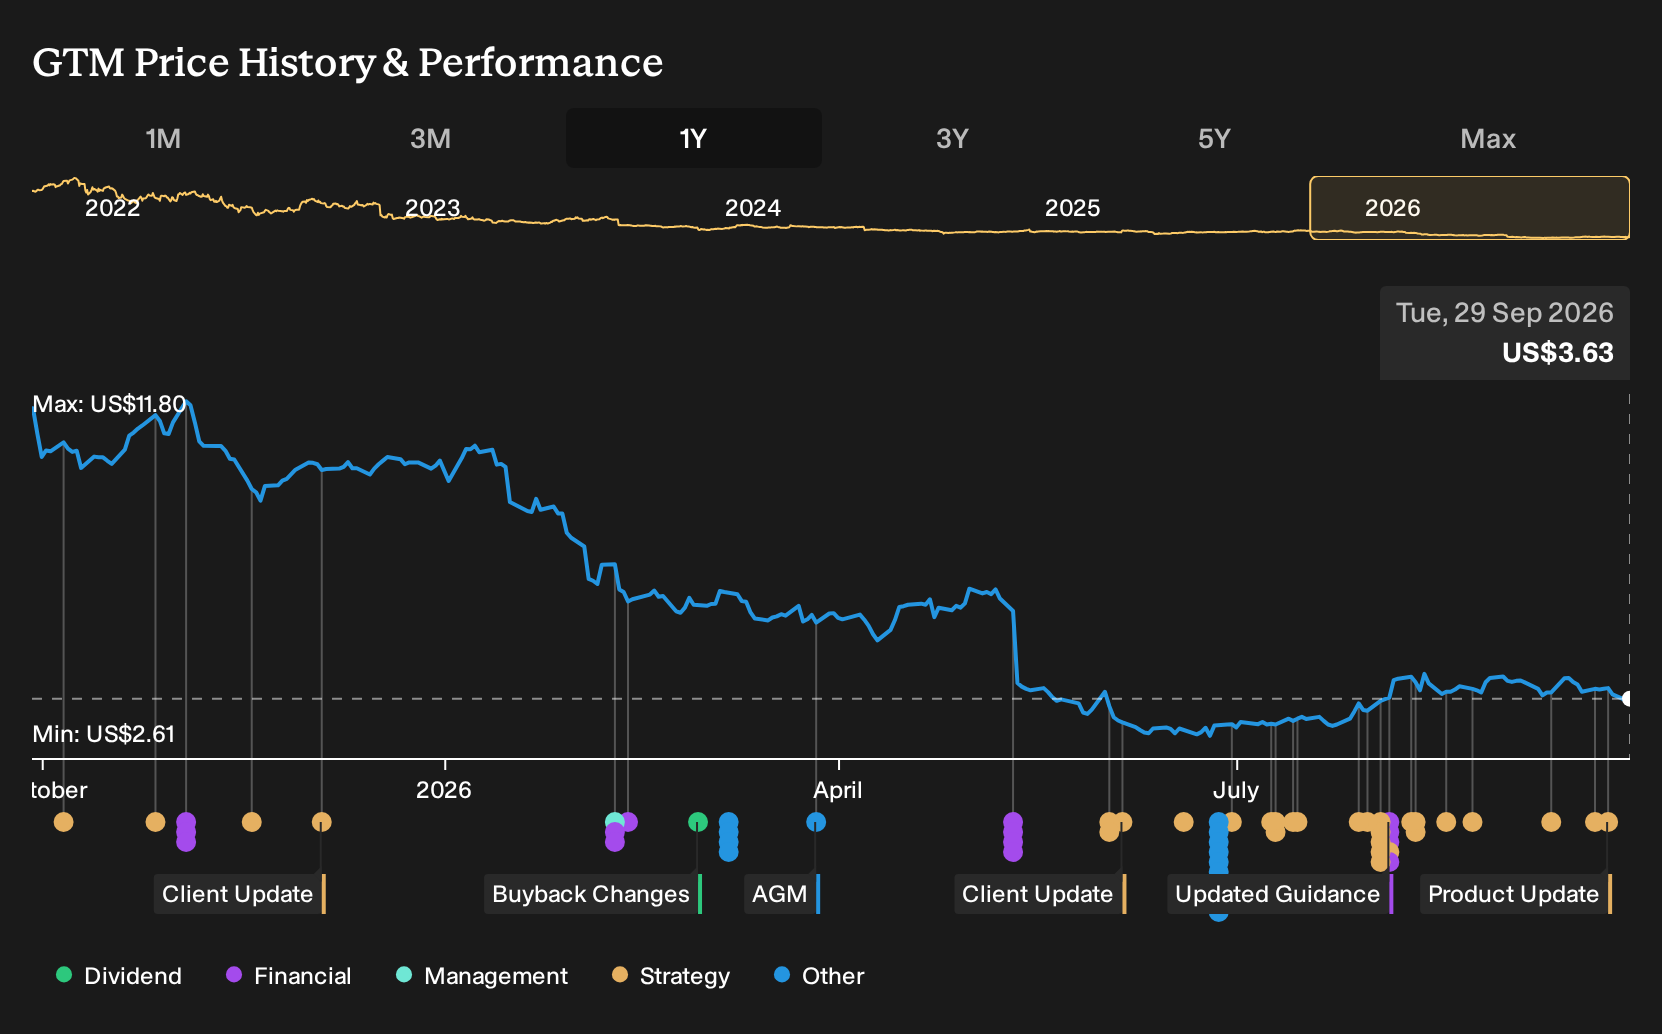
To own ZoomInfo Technologies, you need to believe its GTM.AI data layer and workflow tools can stay central to how large enterprises run sales, marketing, and recruiting, even as revenue is forecast to decline 1.8% a year. The short term swing factor remains whether upmarket wins and AI use cases can offset pressure from smaller customers and a weak share price record.
The biggest risk still sits in concentration on large clients and the threat that AI data and workflows become commoditized while ZoomInfo carries high debt and ongoing losses of US$541.0 million. The recent Superhuman Go, Replit, and Talent Autopilot launches look helpful for execution but do not obviously change that risk balance yet.
The Superhuman Go connector is the clearest tie in to the current ZoomInfo Technologies story. It drops verified GTM.AI data straight into a daily email and productivity surface where sellers and go to market teams already live. That matters for any thesis that leans on deeper embedding in customer workflows rather than just selling contact lists.
For catalysts, this integration lines up with the idea that enterprises want unified data feeding their agents, copilots, and CRMs. Execution now comes down to adoption, measurable usage, and whether this kind of connector helps defend pricing and retention as rivals and open source tools target similar AI powered workflows.
ZoomInfo Technologies' analyst narrative points to revenues of US$1.2b and earnings of US$391.8 million by 2029, built on a forecast 1.3% yearly revenue decline and an earnings swing of about US$932.8 million from a current loss of US$541.0 million to the projected profit base.
Discover how ZoomInfo Technologies' fair value points to a 27% potential upside to its current price before that gap begins to close.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into AI connectors like Superhuman Go as a possible inflection point for ZoomInfo Technologies. They were already modeling flat revenue with earnings of about US$320.1 million by 2029 and a higher 10.4x P/E. These forecasts came before this launch, so opinions and models may continue to evolve.
Explore 4 other ZoomInfo Technologies fair value estimates, including one that suggests as much as 222% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your ZoomInfo Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ZoomInfo Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ZoomInfo Technologies' overall financial health at a glance.
Looking for more ZoomInfo Technologies sized investment ideas?
If ZoomInfo Technologies has you thinking about where else AI driven workflows and solid fundamentals could matter, the Simply Wall St Screener can help you surface other companies that fit your style in a structured, data first way.
- If capital protection sits high on your priority list, focus on businesses that score well on resilience and balance sheet strength by filtering for 32 resilient stocks with low risk scores that aim to keep downside risk in check.
- For readers hunting for quality at a reasonable entry point, narrow your search to companies trading below their assessed fair value by scanning through 32 high quality undervalued stocks that pair fundamentals with potential mispricing.
- Income focused investors who want cash returns on top of any price moves can zero in on higher yield opportunities by reviewing 6 dividend fortresses that prioritize strong payouts and durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com