
Lower Fuel Economy Costs Might Change The Case For Investing In GM Stock
- General Motors and recycling partner Cirba Solutions reported the completion of a closed loop EV battery pilot that used 100% recycled nickel, cobalt and manganese in new cathode active material for cells assembled at Factory ZERO and Spring Hill, with the first vehicles already delivered to consumers.
- The new U.S. fuel economy standards, which are expected to lower long term compliance costs for automakers, intersect with GM's cash generation and buybacks to sharpen focus on how efficiently the business converts regulatory breathing room into durable operating results.
- We will look at how General Motors' investment narrative evolves as lower fuel economy compliance costs reshape expectations for capital allocation.
See how General Motors compares on value and balance sheet strength alongside other potential opportunities with a curated set of 32 high quality undervalued stocks.
General Motors Investment Narrative Recap
To own General Motors, you need to be comfortable with a heavy capital spend on EVs, software and U.S. manufacturing while the core truck and SUV business carries the load. The recycling pilot is directionally helpful for long term battery costs and supply security, but on its own it does not change the near term story.
The key near term swing factor is execution on EV launches and quality, with warranty costs and market share pressure in hybrids still front of mind. The biggest risk remains high investment colliding with slower EV adoption or weaker pricing, which could keep margins thin and make large projects harder to earn back.
The most relevant recent shift around General Motors is the new U.S. fuel economy rule that is expected to cut compliance costs by an estimated US$20.4b through 2031. That relief gives the company more room to lean into EV development and programs like the Cirba recycling loop without the same regulatory cost drag.
For you as a shareholder, the central question is how efficiently GM turns that additional flexibility into cleaner execution on key catalysts. Those catalysts include EV profitability, software monetization and continued buybacks after a roughly 19.5% drop in the diluted share count through Q2 2026, while still managing debt that is not yet well covered by operating cash flow.
What The General Motors Analyst Case Is Really Asking You To Underwrite
General Motors' long term script in the analyst models is relatively clear. By 2029, those forecasts point to about US$195.5b in revenue and US$8.2b in earnings on the back of modest 1.8% yearly top line growth, up from US$1.9b in earnings today, which implies an earnings increase of roughly US$6.3b.
Uncover why General Motors' fair value indicates a 24% potential upside to its current price that could narrow quickly.
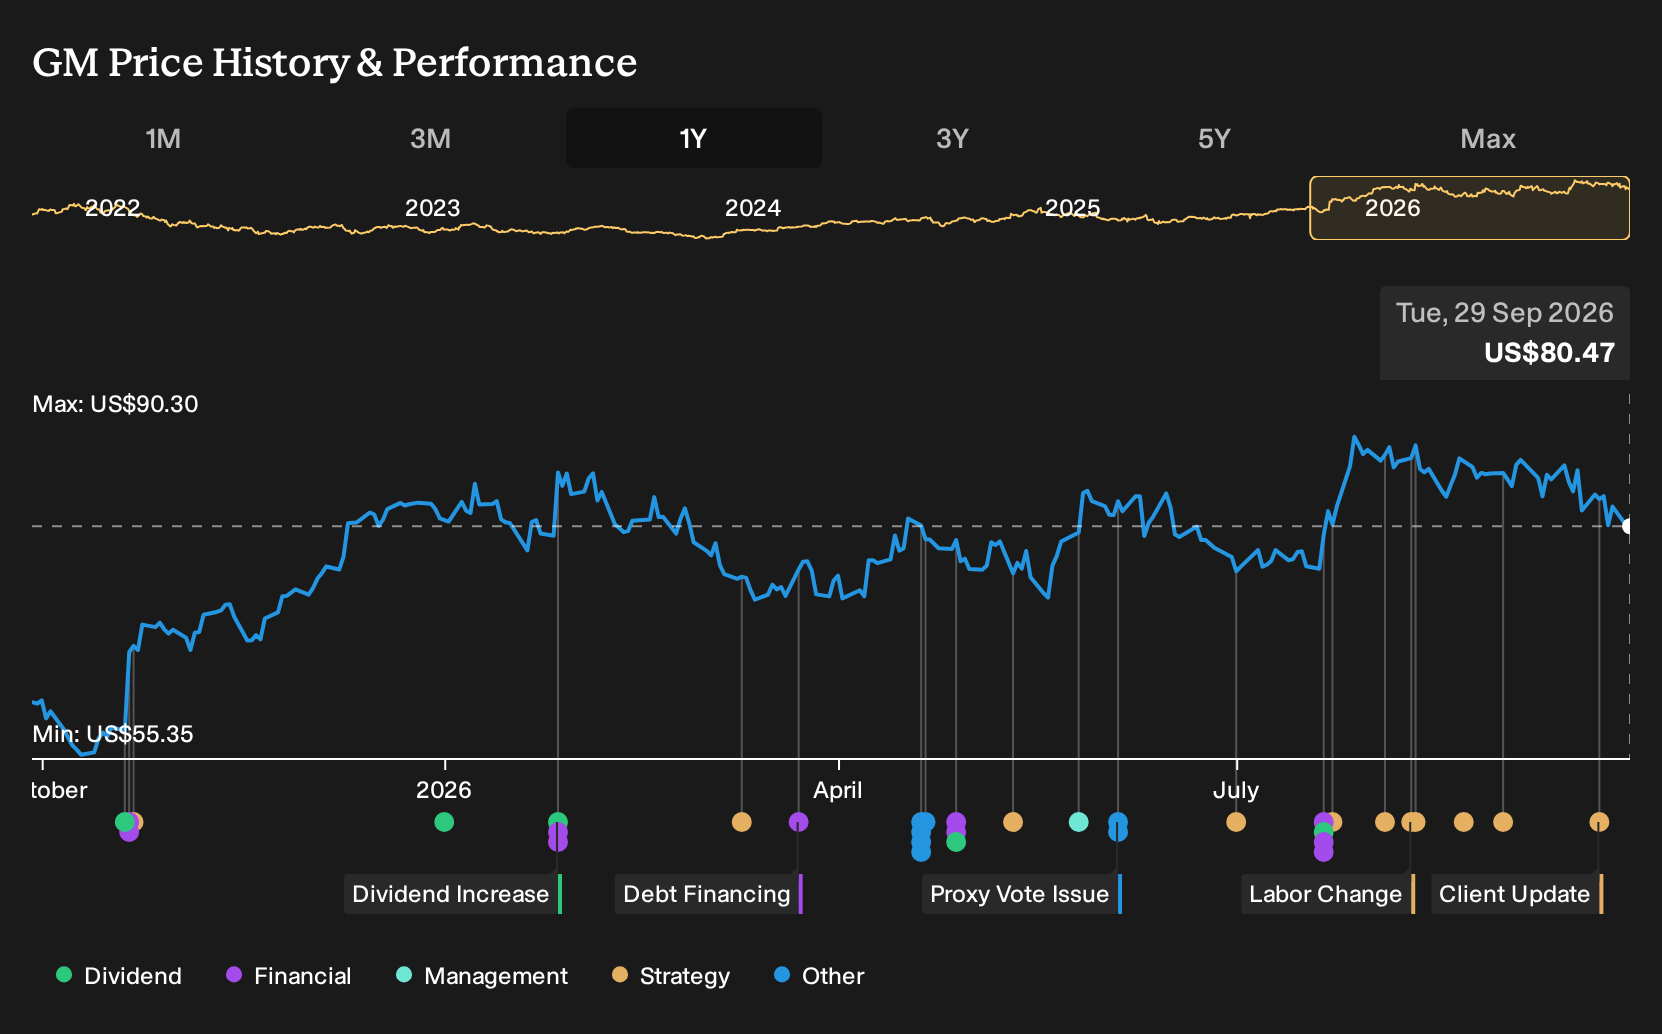
Exploring Other Perspectives
For contrast, focus on the bearish analysts who worry about intensifying EV competition for General Motors. Before this recycling news, the lowest forecasts assumed revenue around US$188.1b by 2029 and still only supported a US$75 price target. That is a far more cautious story, and this new battery loop could push those views to evolve.
Explore 7 other General Motors fair value estimates, including one that suggests as much as 17% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your General Motors research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for General Motors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate General Motors' overall financial health at a glance.
Looking For More Investment Ideas Beyond General Motors?
If this General Motors story has sharpened your thinking about capital allocation, risk and return, it can be useful to line that view up against a wider watchlist. The Simply Wall St Screener lets you quickly filter for different profiles so you can compare GM with other candidates that might fit your return and risk preferences.
- If you want stability and income to balance a cyclical stock like General Motors, consider companies that appear in our 6 dividend fortresses for potential high-yield payers with robust fundamentals.
- If downside protection is front of mind, especially when backing capital intensive stories like GM, you can focus on businesses that show up in the 32 resilient stocks with low risk scores to see which stocks our model scores as more resilient.
- For investors hunting for potential future leaders alongside more established players such as General Motors, scan the 17 high quality undiscovered gems to find less followed companies with stronger quality signals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com