
3 Oil And Gas Stocks With Strong Cash Flow Exposure To Higher Oil Prices
Markets are waking up to a harsh mix of sliding U.S. equity futures, surging Treasury yields and oil prices pressing toward triple digits, while fresh Middle East headlines unsettle already cautious traders. That kind of stress test can punish weak balance sheets and reward stronger operators. This article walks through 3 large integrated oil and gas stocks exposed to this news backdrop and explains why each could matter for your portfolio decisions today.
The three stocks below are just a starting sample. The full Global Integrated Oil & Gas and Energy Producers screen surfaced 6 more companies with equally compelling narratives that are not covered in this article.
If you want to move quickly from headlines to a focused watchlist, head straight into the Global Integrated Oil & Gas and Energy Producers screener to identify, compare and analyze the highest conviction ideas that fit your criteria.
Northern Oil and Gas (NOG)
Overview: Northern Oil and Gas is a US focused independent producer that acquires and develops oil and gas assets, giving investors direct exposure to commodity driven upstream cash flows within the energy producers theme.
Operations: Northern Oil and Gas generates all its US$2.0 billion revenue from US oil and gas exploration and production activities in the United States.
Market Cap: US$2.5b
Northern Oil and Gas matters for this screen because it is a pure upstream play. The company is tightly linked to crude pricing and energy security, with cash generation shaped by how its acquisition heavy model performs through the current oil shock.
"The company's disciplined shift toward acquisitions of long-dated, stable production assets amid a volatile commodity environment positions NOG to benefit from continued global energy demand and the ongoing importance of energy security, supporting more resilient long-term revenue and less volatile cash flows.
What really moves the needle from here is how one pressure on its funding mix ultimately feeds through to margins and long run cash returns.
That funding squeeze is the hinge. Read the full narrative for Northern Oil and Gas to see how Northern Oil and Gas could turn acquisition heavy spending into accelerating long term cash strength.
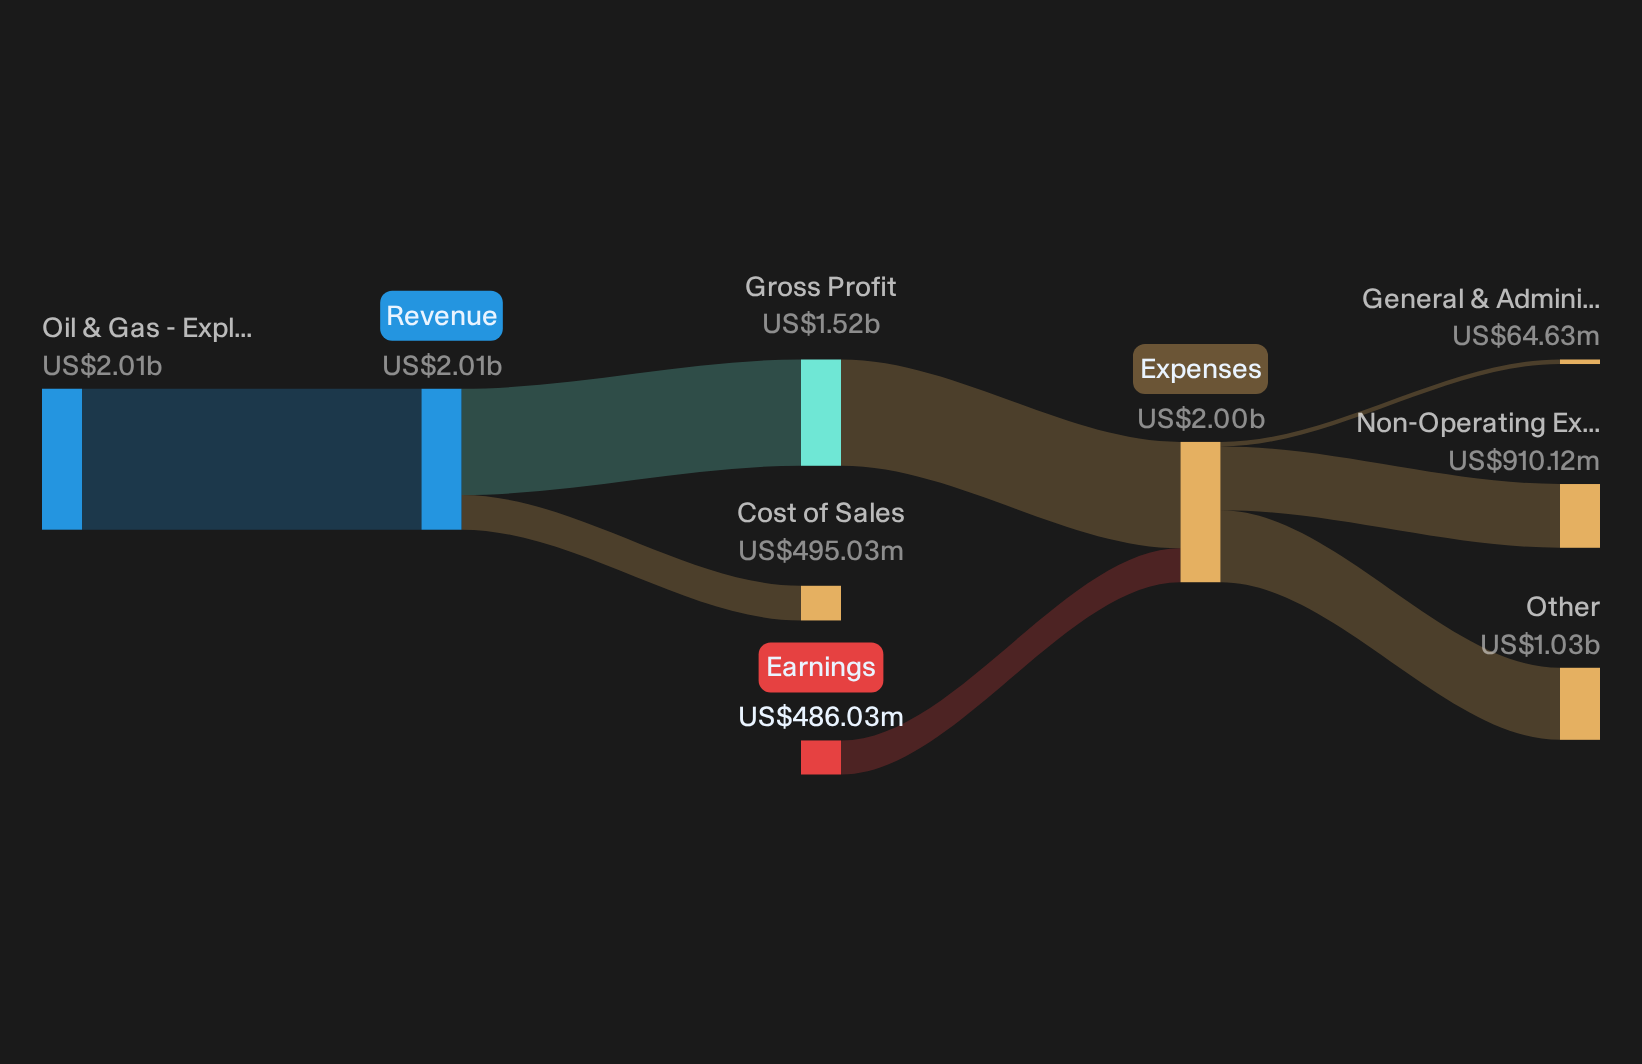
Magnolia Oil & Gas (MGY)
Overview: Magnolia Oil & Gas is a Houston based independent producer that drills for oil, gas and liquids in South Texas, giving investors focused upstream exposure within the Global Integrated Oil & Gas and Energy Producers theme.
Operations: Magnolia Oil & Gas generates about US$1.5b in revenue from oil and gas exploration and production in the United States.
Market Cap: US$5.6b
Magnolia Oil & Gas matters here because it offers direct leverage to crude prices, while the screener criteria help filter for balance sheet and shareholder return discipline that can influence how any windfall pricing translates into investor outcomes.
"The enlarged Giddings position following the WildFire Energy acquisition, with nearly 1.3 million net acres and multi-zone potential, gives Magnolia Oil & Gas room to shift future drilling toward higher oil cut areas that could support a richer liquids mix and improve revenue quality and cash margins over time."
What really decides how that plays out for you is how one emerging pressure on profitability interacts with this bigger, more oil weighted footprint.
That hinge is where Magnolia Oil & Gas gets interesting, and the full narrative for Magnolia Oil & Gas shows whether this bigger footprint is quietly accelerating or masking shareholder returns.

California Resources (CRC)
Overview: California Resources is a California based energy producer and carbon management company focused on oil, gas, power generation and CO2 storage.
Operations: California Resources generates about US$3.4b from Oil and Natural Gas operations, with total US revenue of roughly US$3.7b.
Market Cap: US$4.6b
California Resources fits this Global Integrated Oil & Gas and Energy Producers screen as a larger, California focused producer that layers in carbon management and midstream assets on top of its core oil and gas business.
"Although California Resources highlights an integrated California platform across production, midstream, power, CCS, and data center sites as a source of future contracted cash flows, the recent marketing disputes and takeaway bottlenecks that built about 1,500 boe/d of unsold oil and cut roughly US$25 million from quarterly adjusted EBITDAX show that this integration can still translate into higher operating costs and weaker differentials, which can pressure net margins if replicated."
What really shapes how California Resources trades this cycle is what happens if a single cost pressure quietly reshapes those future cash returns.
If that cost pressure is the real swing factor, read the full narrative for California Resources to see whether California Resources is quietly accelerating or stalling future cash strength.

Seeking Fresh Alternatives Before Momentum Flips
New themes can move from quiet to breakout quickly. Prices can reprice rapidly once early money starts building positions. Scan fresh ideas before the crowd notices and consider acting before liquidity tightens.
- Spot potential turnaround stories with cleaner balance sheets and resilient earnings profiles by running the list of solid balance sheet and fundamentals (25 results) while it is still under the radar for most investors.
- Track structural shifts in automation and industrial efficiency by following the 93 robotics and automation stocks before capital chases the next wave of momentum and narrows your entry window.
- Explore opportunities linked to demand for grid resilience and electrification by filtering the 39 power grid technology and infrastructure stocks while the strongest operators may still reflect hesitation in their pricing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com