
Netwealth Group Fell 40% While The Case For It Never Settled
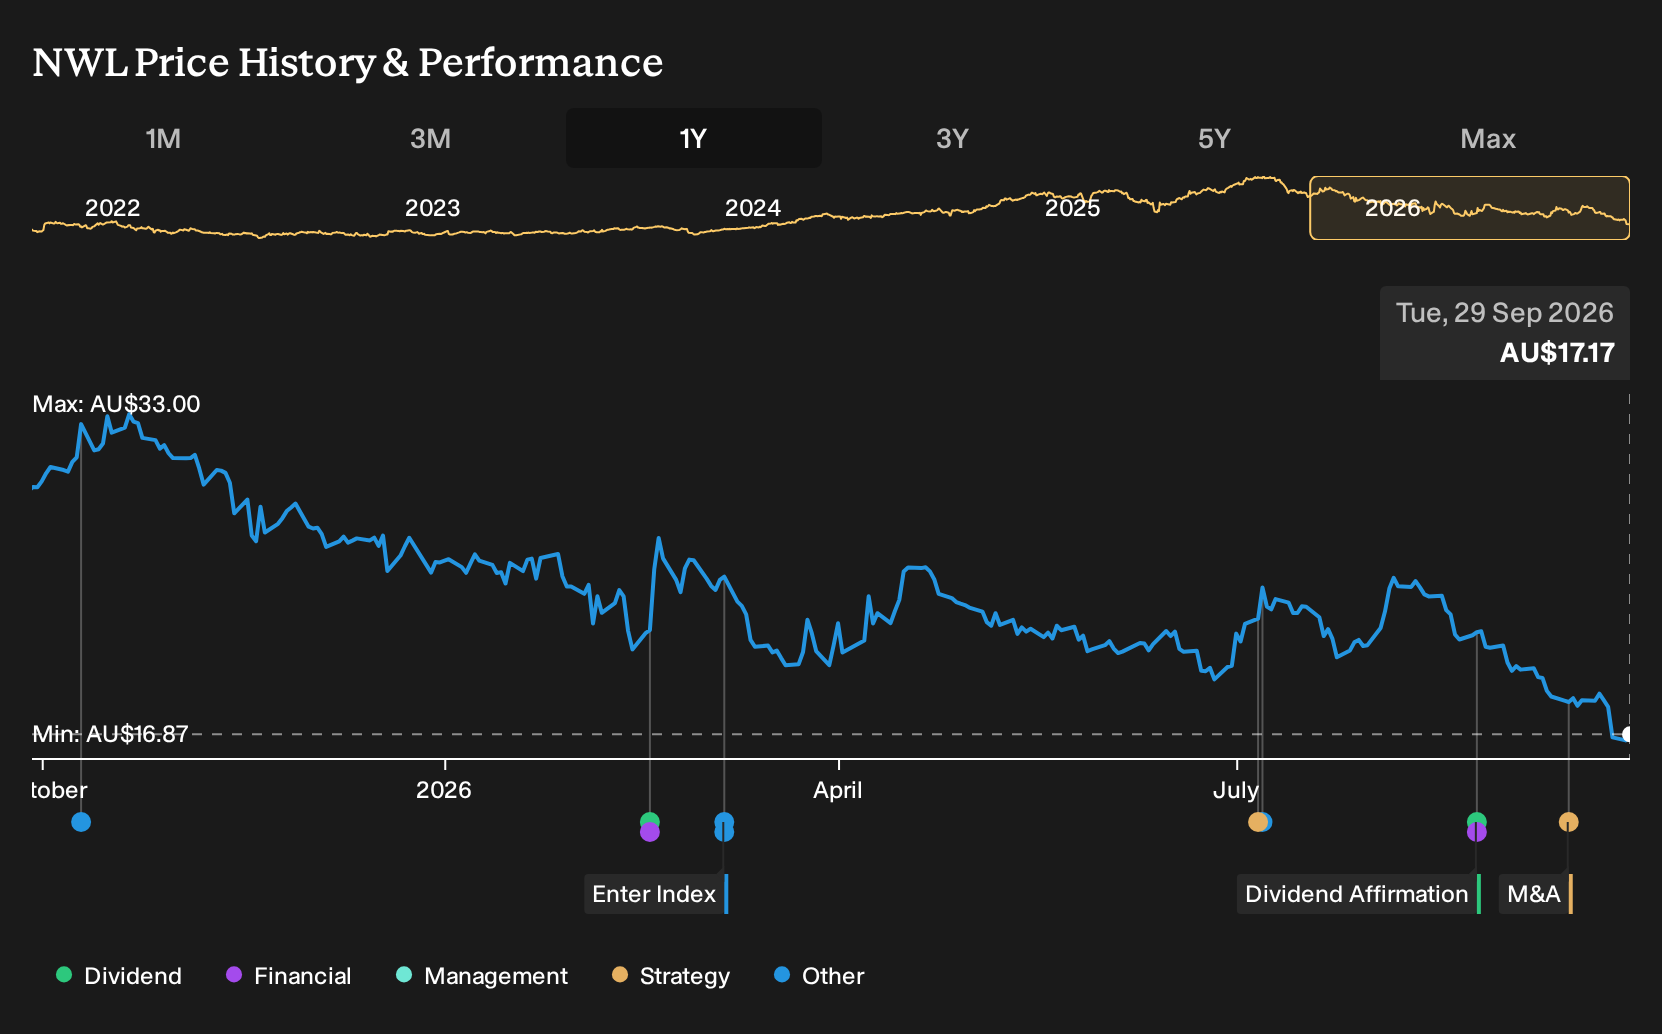
If you had backed Netwealth Group on 29 September 2025 expecting digital transformation and wealth transfer tailwinds to do the heavy lifting, the outcome would have felt brutal. Holding Netwealth Group over the past year would have meant a 40.4% loss, including dividends. That gap between story and result is stark. What did the original bullish and bearish cases fail to allow for in those specific revenue, margin and P/E assumptions?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Netwealth Group has already moved. See which of 5 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Were Weighing On Netwealth Group
The shares cost A$29.4 at the start of the period, and anyone looking at Netwealth Group then had to choose between two very different stories that both sounded reasonable.
On the bullish side, the case titled Digital Transformation And Wealth Transfer Will Shape Investment Trends put Fair Value at A$41.5. Supporters leaned on assumptions of rapid AI adoption and platform scalability that could support higher net margins and faster earnings growth.
On the bearish side, the view described as Rising Global Compliance Burdens Will Erode Margins Amid Digital Competition put Fair Value at A$15.2. That camp focused on rising regulatory and cyber security costs that could lift compliance spending and steadily pressure profitability.
What The Results Changed For The Netwealth Group Thesis
The fresh Morgan Stanley Wealth Management Australia platform deal gave Netwealth Group extra proof for the bullish story that leaned on tech adoption and adviser uptake. Reported numbers added a wrinkle. Total revenue and net income both rose between H2 2025 and H2 2026, yet net margin slipped from 34.9% to 31.8%, which challenged the cleaner margin expansion the optimistic case relied on. Overall, the evidence cut both ways.
The clear hinge here was profitability quality. When you see sales and profit move up but the margin percentage edge down, treat any story about operating leverage as unproven and go straight to the reported margin line in the next set of accounts.
What Today’s Netwealth Group Price Already Assumes
Netwealth Group now trades at A$17.17, after a 40.4% loss over the past year from A$29.4. The selected Narrative argues that its Fair Value figure sits above the current price.
That view leans on sustained digital investment, adviser productivity gains and broader product coverage. A buyer today must judge whether adviser platform adoption and inflows can deliver that level of recurring earnings power.
"Netwealth's continued investment in best-in-class digital experience, platform functionality, and data analytics aligns with the ongoing digitisation of financial services and increasing regulatory focus on transparency, positioning the company to capture greater adviser and client net inflows, bolster revenue growth, and strengthen platform stickiness."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
One Step Beyond Netwealth
Netwealth Group sits where advice, portfolios and client money meet. That is only one layer of how savings actually move.
Every portfolio rebalance and model change still needs secure payment settlement. Your account switch, fee debit or pension drawdown all rely on that hidden plumbing.
Another business specialises in running global payment rails and related services. It gives banks, merchants and digital platforms tools to move money safely.
The open question is how that payments heavyweight evolves as advisers digitise, flows spread and fresh ways to send money keep appearing.
One Narrative has already put a figure on it. → Uncover the company trading 25% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com