
Asian Stocks Estimated To Be Trading Below Fair Value In September 2026
In September 2026, Asian markets have been navigating a complex landscape marked by inflation concerns and fluctuating interest rates, mirroring trends seen in global indices. Despite these challenges, investors are keenly eyeing opportunities to identify stocks that may be trading below their fair value. In such an environment, a good stock is often characterized by strong fundamentals and the potential for growth even amidst broader economic uncertainties.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Shizuki Electric (TSE:6994) | ¥1228.00 | ¥2315.92 | 47% |
| Kumagai GumiLtd (TSE:1861) | ¥1254.00 | ¥2417.99 | 48.1% |
| Kingnet Network (SZSE:002517) | CN¥15.87 | CN¥31.52 | 49.6% |
| Ichikoh Industries (TSE:7244) | ¥560.00 | ¥1077.09 | 48% |
| Double Medical Technology (SZSE:002901) | CN¥40.56 | CN¥79.35 | 48.9% |
| Dongwon Industries (KOSE:A006040) | ₩35600.00 | ₩71040.45 | 49.9% |
| China Coal Energy (SEHK:1898) | HK$10.51 | HK$20.10 | 47.7% |
| Cheil Worldwide (KOSE:A030000) | ₩17880.00 | ₩34232.72 | 47.8% |
| Astellas Pharma (TSE:4503) | ¥2294.00 | ¥4331.42 | 47% |
| AK Medical Holdings (SEHK:1789) | HK$4.83 | HK$9.52 | 49.2% |
Let's review some notable picks from our screened stocks.
Plover Bay Technologies (SEHK:1523)
Overview: Plover Bay Technologies Limited is an investment holding company that designs, develops, and markets software-defined wide area network routers and related products, with a market cap of HK$8.15 billion.
Operations: The company generates revenue from three main segments: Sales of SD-WAN Routers - Fixed First Connectivity ($21.10 million), Sales of SD-WAN Routers - Mobile First Connectivity ($76.53 million), and Software Licenses and Warranty and Support Services ($44.17 million).
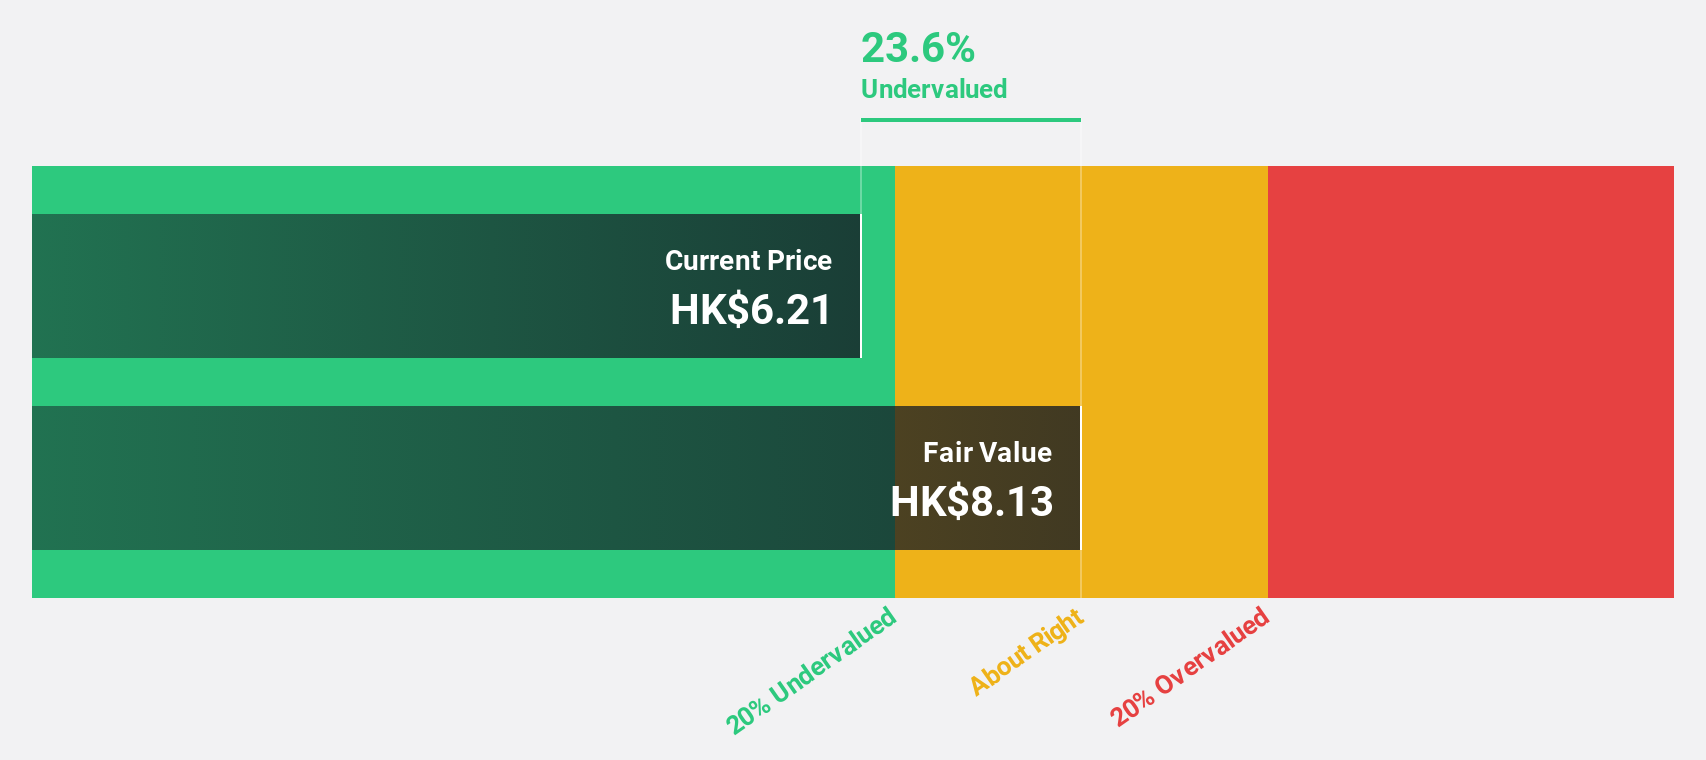
Estimated Discount To Fair Value: 20%
Plover Bay Technologies is trading at HK$7.37, below its estimated future cash flow value of HK$9.21, suggesting it may be undervalued based on cash flows. Earnings are forecast to grow 14.1% annually, outpacing the Hong Kong market's 11.1%, and revenue growth is expected at 13.7%. Recent earnings showed sales rising from US$62.94 million to US$74.6 million year-on-year, with net income increasing from US$21.67 million to US$27.72 million for the same period.
- Upon reviewing our latest growth report, Plover Bay Technologies' projected financial performance appears quite optimistic.
- Click here to discover the nuances of Plover Bay Technologies with our detailed financial health report.
Osaka Soda (TSE:4046)
Overview: Osaka Soda Co., Ltd. manufactures and sells basic and functional chemical products across Asia, Europe, North America, and internationally with a market cap of ¥233.20 billion.
Operations: The company's revenue is derived from its segments in Healthcare (¥15.96 billion), Basic Chemical (¥43.41 billion), and Functional Chemical (¥29.89 billion).
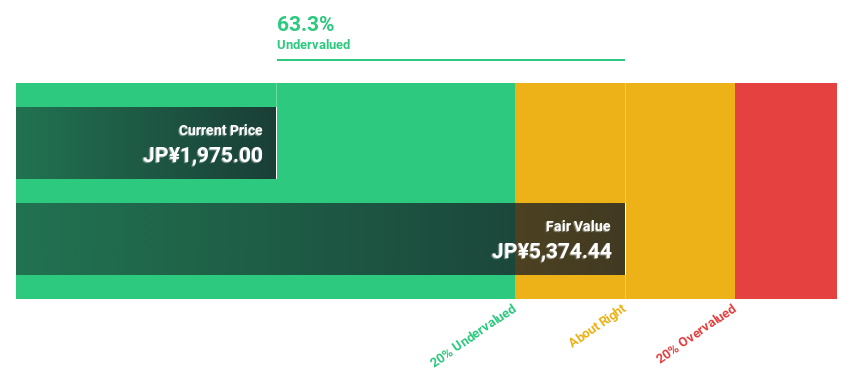
Estimated Discount To Fair Value: 29.4%
Osaka Soda is trading at ¥1,936, below its estimated cash flow value of ¥2,742.95. Despite a volatile share price and slower forecasted earnings growth compared to the JP market, it remains undervalued by over 20% based on discounted cash flows. The company revised its fiscal guidance upward due to increased market prices for Allyl Ethers and stable healthcare product sales, reporting improved net income from ¥3.05 billion to ¥4.95 billion year-on-year in Q1 2026.
- According our earnings growth report, there's an indication that Osaka Soda might be ready to expand.
- Get an in-depth perspective on Osaka Soda's balance sheet by reading our health report here.
Accton Technology (TWSE:2345)
Overview: Accton Technology Corporation is engaged in the development, manufacturing, and sale of computer network systems and wireless LAN hardware and software products both in Taiwan and internationally, with a market capitalization of NT$1.01 trillion.
Operations: The company generates revenue of NT$310.62 billion from its computer networks segment.
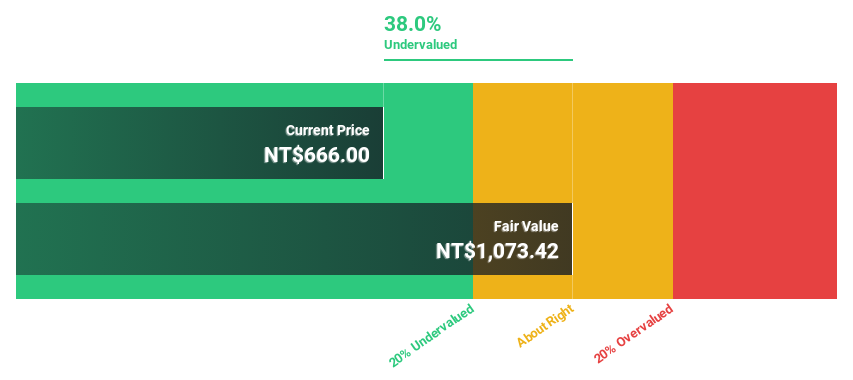
Estimated Discount To Fair Value: 37.1%
Accton Technology is trading at NT$1,810, significantly below its estimated future cash flow value of NT$2,876.39. Despite recent share price volatility, the company shows strong financial performance with net income doubling year-on-year in Q2 2026 to NT$11.05 billion and earnings per share nearly doubling as well. Forecasts indicate earnings growth of over 35% annually and revenue growth surpassing market averages, underscoring its potential undervaluation based on robust cash flows.
- Our comprehensive growth report raises the possibility that Accton Technology is poised for substantial financial growth.
- Click here and access our complete balance sheet health report to understand the dynamics of Accton Technology.
Seize The Opportunity
- Embark on your investment journey to our 87 Undervalued Asian Stocks Based On Cash Flows selection here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com