
Brexit Trade Rules Put Weir Stock And EasyJet Shares Back In Focus
Brexit is back on the table, and this time the debate is not just about politics. It is about which UK exporters and EU facing groups could gain or lose if market access rules, tax policy and public ownership all shift again. Investors who ignore that mix of trade rewiring and fiscal change risk missing important moves. This article looks at three stocks from the screener that appear positioned to navigate the latest twist in UK EU relations.
The three stocks below are only a sample of what surfaced on this theme. The full screen identified 40 more UK Export-Oriented and EU-Facing Companies with equally compelling trade and policy stories that are not covered here.
If you want to move beyond headlines and identify, filter and analyze the companies that best fit your own risk and return preferences, head straight to the UK Export-Oriented and EU-Facing Companies screener.
Weir (LSE:WEIR)
Overview: Weir PLC supplies highly engineered equipment, wear parts and digital services to global mining customers, with export-heavy exposure including Europe.
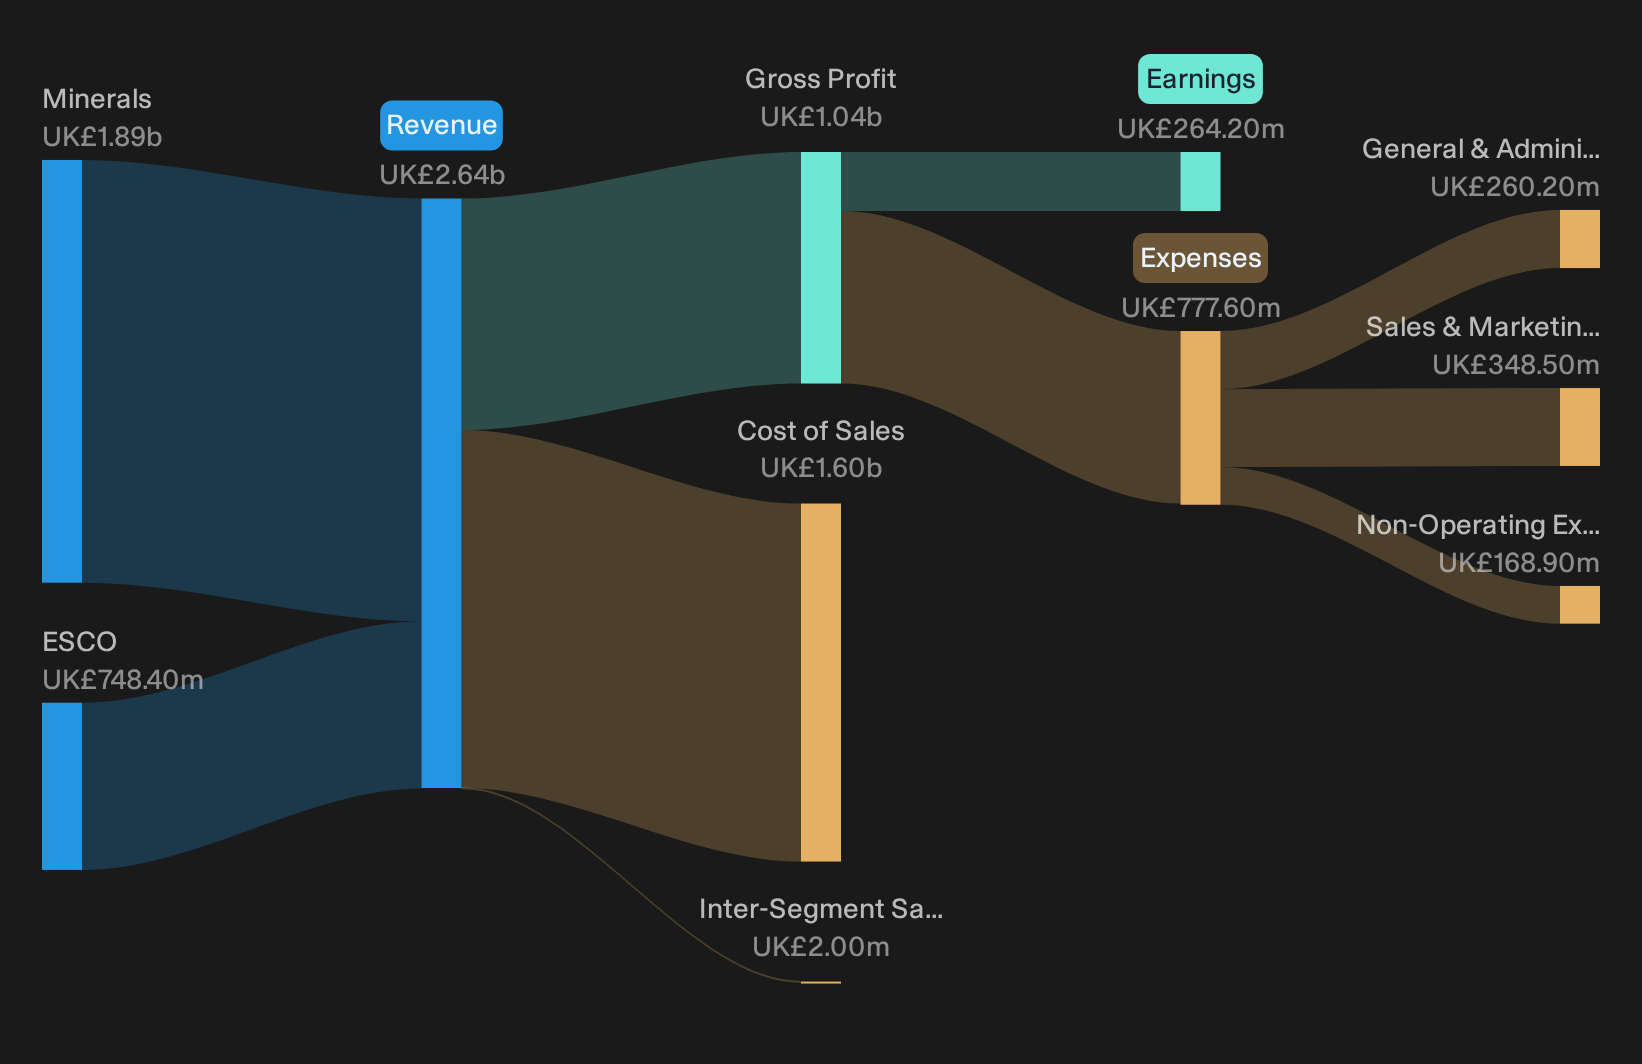
Operations: The business generates about £1.9b from its Minerals unit and £748 million from ESCO, with income spread across North America, South America, Australasia and other mining regions.
Market Cap: £7.0b
Weir matters for this UK Export-Oriented and EU-Facing Companies theme because its mining equipment flows across borders, so any shift in EU access or trade friction feeds directly into demand, pricing power and service workloads.
"Ongoing investments in R&D at around 2% of sales, higher CapEx at roughly 1.3x depreciation and the multi year SAP S/4 rollout could keep fixed costs elevated."
What really moves the needle for Weir now is how one unresolved pressure shapes the balance between export-driven activity and margin resilience.
That pressure point is exactly where the full narrative for Weir shows how Weir’s export engine, capital spend and policy risk could be quietly decoupling from headline sentiment.
easyJet (LSE:EZJ)
Overview: easyJet is a UK based low cost airline flying mainly between the UK and Europe, with additional holiday and travel services.
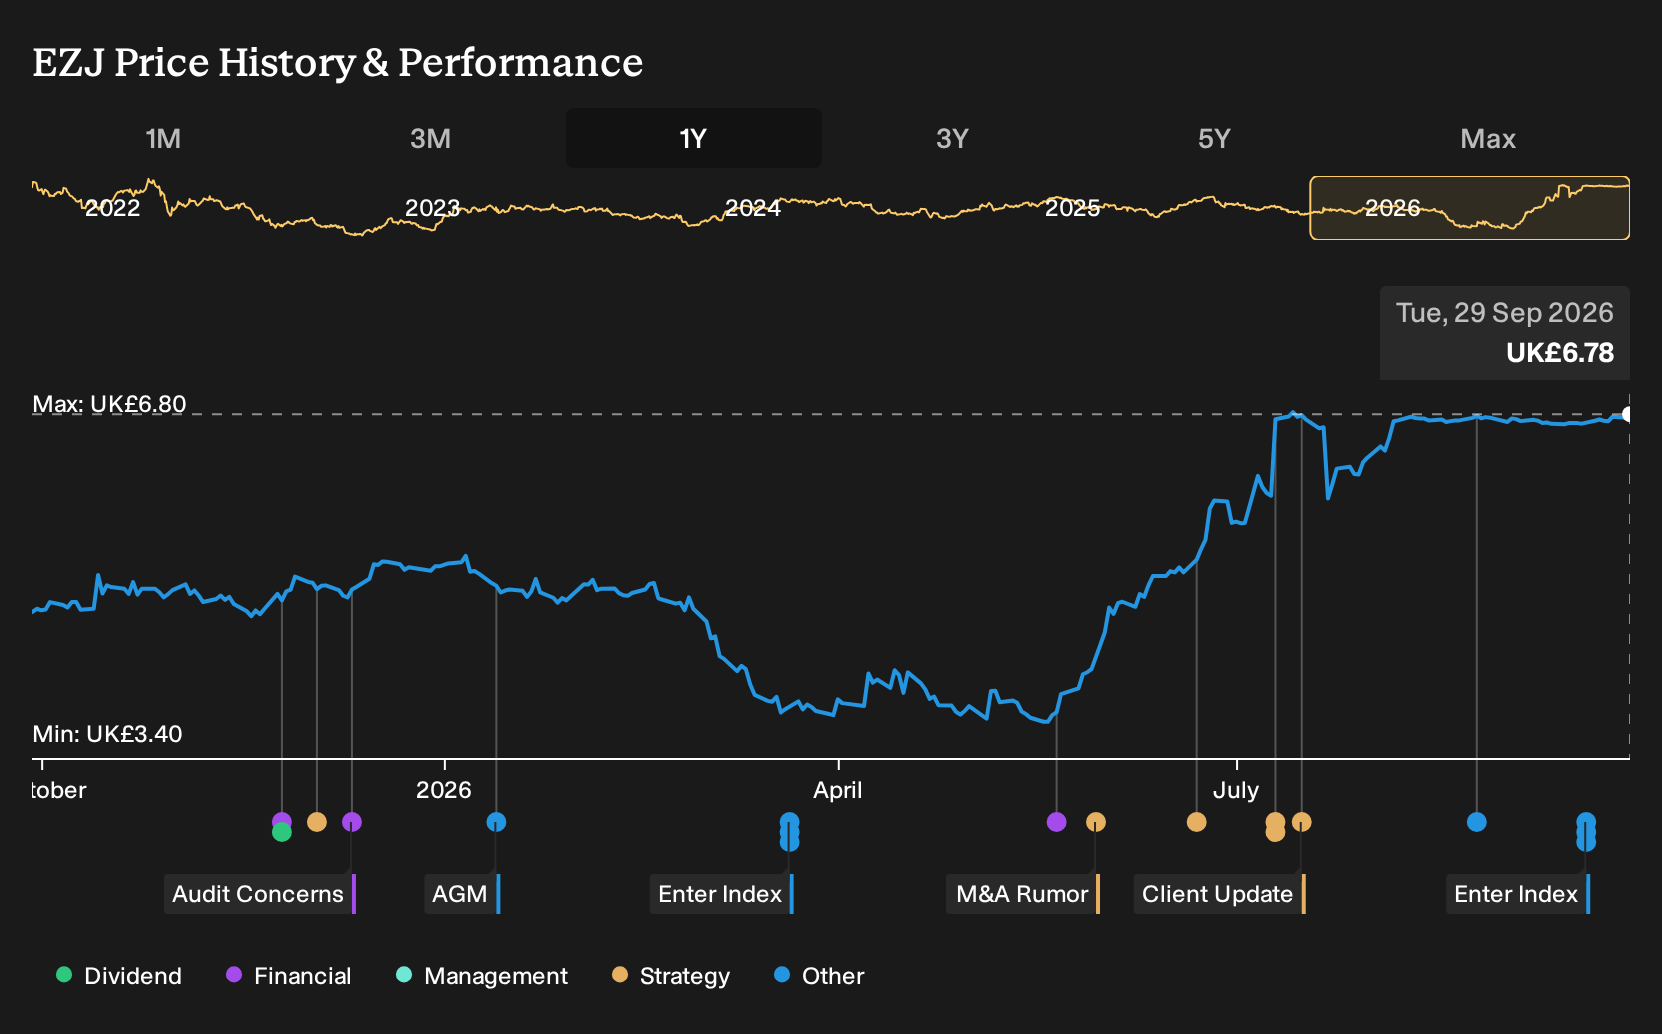
Operations: easyJet generates about £9.0b from its Airline division and £2.1b from EasyJet Holidays, with smaller intergroup adjustments and broad European exposure.
Market Cap: £5.1b
For this UK Export Oriented and EU Facing Companies theme, easyJet matters because its low cost model depends on smooth UK EU aviation access. Even modest rule changes can quickly alter route economics and passenger demand patterns.
"It's a brutally competitive market without doubt, and with competitors such as Ryanair and its mercurial CEO around, you get perhaps some extra heat compared with other industries."
What really counts for easyJet now is how one quiet shift in cross border rules and costs shapes the balance between load factors and fares.
That quiet shift starts to matter when you read the full narrative for easyJet, which lays out how easyJet’s EU exposure could turn regulatory friction into accelerating earnings power.
Smith & Nephew (LSE:SN.)
Overview: Smith & Nephew designs and sells orthopaedic implants, sports medicine tools, and advanced wound care products to healthcare providers worldwide.
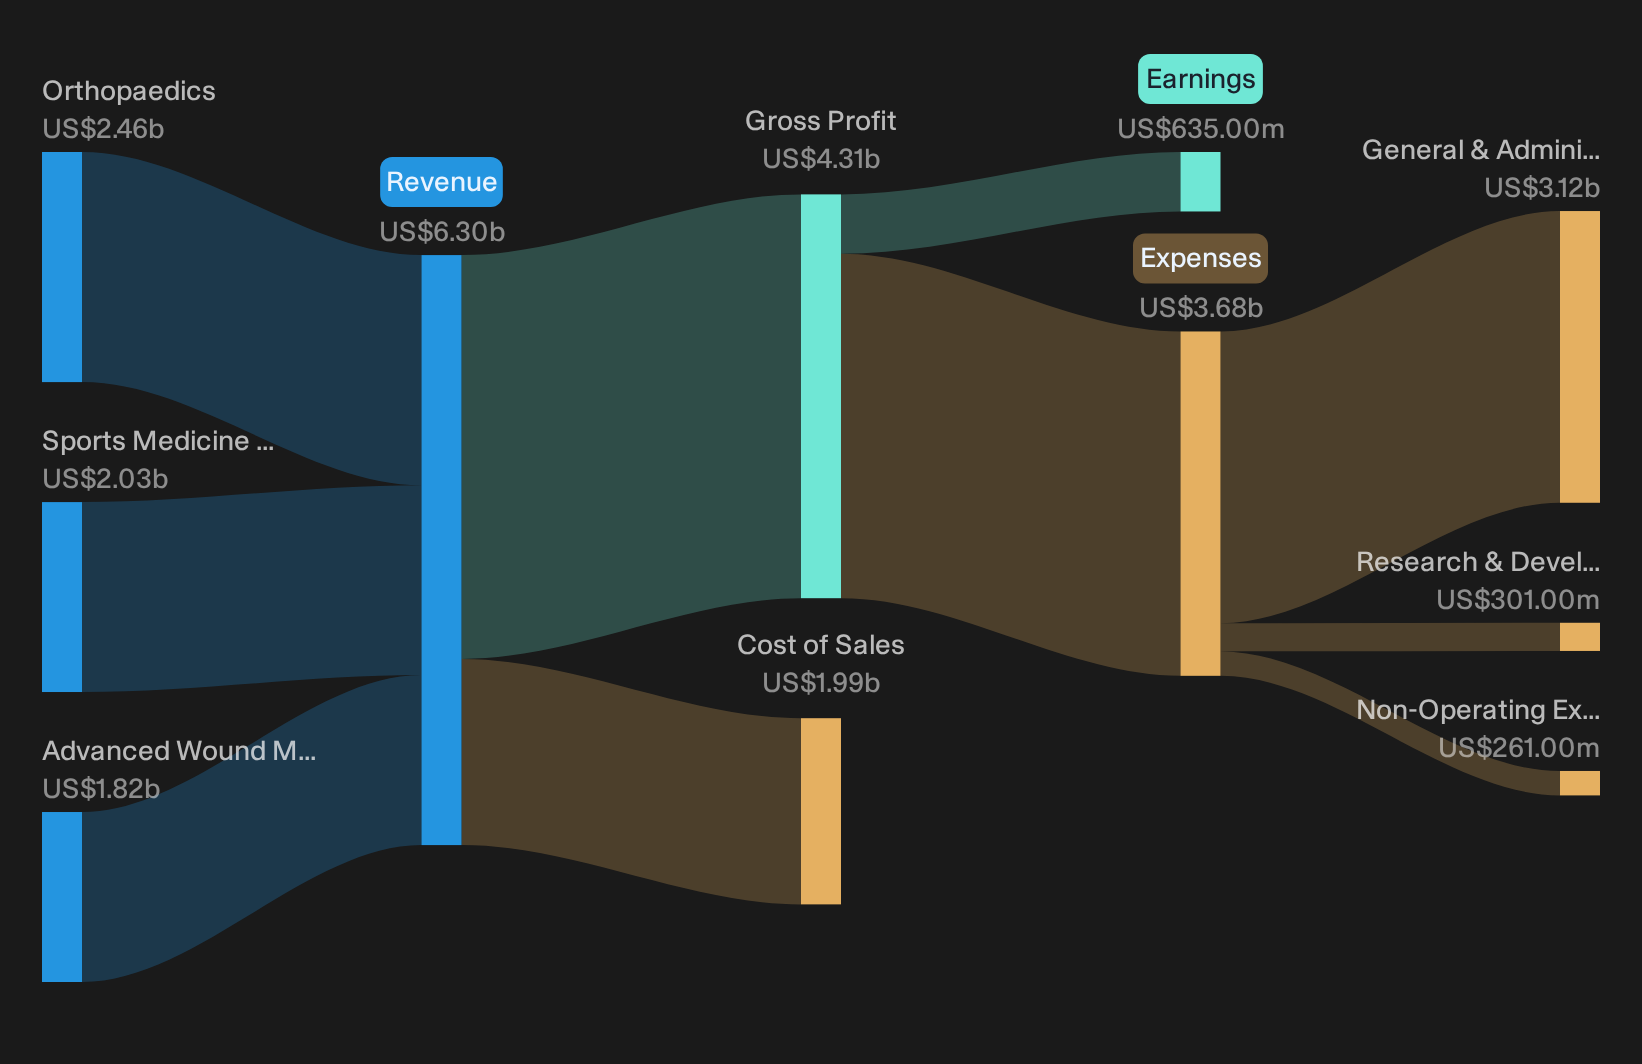
Operations: Smith & Nephew generates about $2.5b from Orthopaedics, $2.0b from Sports Medicine & ENT, and $1.8b from Advanced Wound Management.
Market Cap: £8.5b
Smith & Nephew matters for this UK Export Oriented and EU Facing Companies screen because its joint implants, surgical tools and wound therapies depend on smooth cross border supply chains and market access into European healthcare systems.
"Ongoing operational transformation (12-Point Plan) and supply chain optimization are yielding visible gains: inventory days have dropped, legacy capacity and costs have been reduced, and group margins have expanded by 240 bps since H1 2023."
What happens next for Smith & Nephew depends on how one unseen pressure shapes the trade off between export driven demand and margin progress.
That hidden pressure point is exactly where the full narrative for Smith & Nephew shows whether Smith & Nephew’s margin rebuild is quietly accelerating or still masking deeper risks.
Seeking Fresh Alternatives Beyond Brexit?
Fresh opportunities do not wait. By the time momentum hits the headlines, the ideal entry can be gone. Scan what others miss while it matters, then get in early.
- Spot cash rich businesses before the crowd by zeroing in on a curated list of solid balance sheet and fundamentals (10 results) that filters out weak fundamentals and balance sheet strain.
- Ride potential income momentum with a focused pool of 1 dividend fortresses that screens for higher yields while weaker payouts are still dropping from view.
- Track the next wave of automation before it flies across mainstream coverage by working through carefully filtered 92 robotics and automation stocks aligned with real revenue and balance sheet data.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com