
Prysmian (BIT:PRY) Could Be 19% Undervalued On Its Electrification Growth Story
Prysmian (BIT:PRY) drew fresh attention after its recent share move, with the price closing at €124.80. Investors are weighing that level against the group’s multiyear return profile and current earnings power.
The recent 1 day share price return of 1.84% to €124.80 comes after a mixed few months for Prysmian, with the 30 day share price return of 2.25% offset by a 90 day decline of 12.79%. Over longer periods, momentum has been strong, with a year to date share price return of 38.85% and a 5 year total shareholder return of 346.37% pointing to sustained value creation for investors who stayed invested through the swings.
Scan Prysmian’s momentum against other potential breakouts by reviewing the hand picked 197 high quality undervalued stocks that pair solid fundamentals with compressed valuations.
Prysmian now trades near €124.80 after a strong run, while recent three month weakness hints at profit taking. Does that price still leave meaningful upside, or has most of the easy gain already been captured before the valuation work even starts?
Most Popular Narrative: 18.5% Undervalued
The most followed valuation narrative for Prysmian puts fair value at €153.05, well above the recent €124.80 close. That gap rests on a view that electrification, grid upgrades and data traffic can justify stronger earnings and a richer multiple over time.
The combination of strong investment trends in electrification, grid modernization, and robust data center buildout, especially in the U.S., is expected to support substantial revenue growth in Prysmian's core Power Grid, Transmission, and Digital Solutions divisions, as evidenced by accelerating order intake, upgraded guidance, and capacity expansions.
See why 32 investors see Prysmian as 18% undervalued.
Result: Fair Value of €153.05 (UNDERVALUED)
Still, Prysmian’s reliance on supportive trade policies and the smooth delivery of large grid projects could quickly challenge this upside story if tariffs shift or projects stumble.
Find out about the key risks to this Prysmian narrative.
Another Angle On Prysmian’s Valuation
The SWS DCF model paints a cooler picture than the €153.05 fair value narrative. On that framework, Prysmian at €124.80 is trading above an estimated future cash flow value of €96.79, which points to an overvalued reading rather than an 18.5% discount. Which story do you lean toward when real money is on the line?
For a clearer sense of how that cash flow view is built and where the sensitivities sit, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
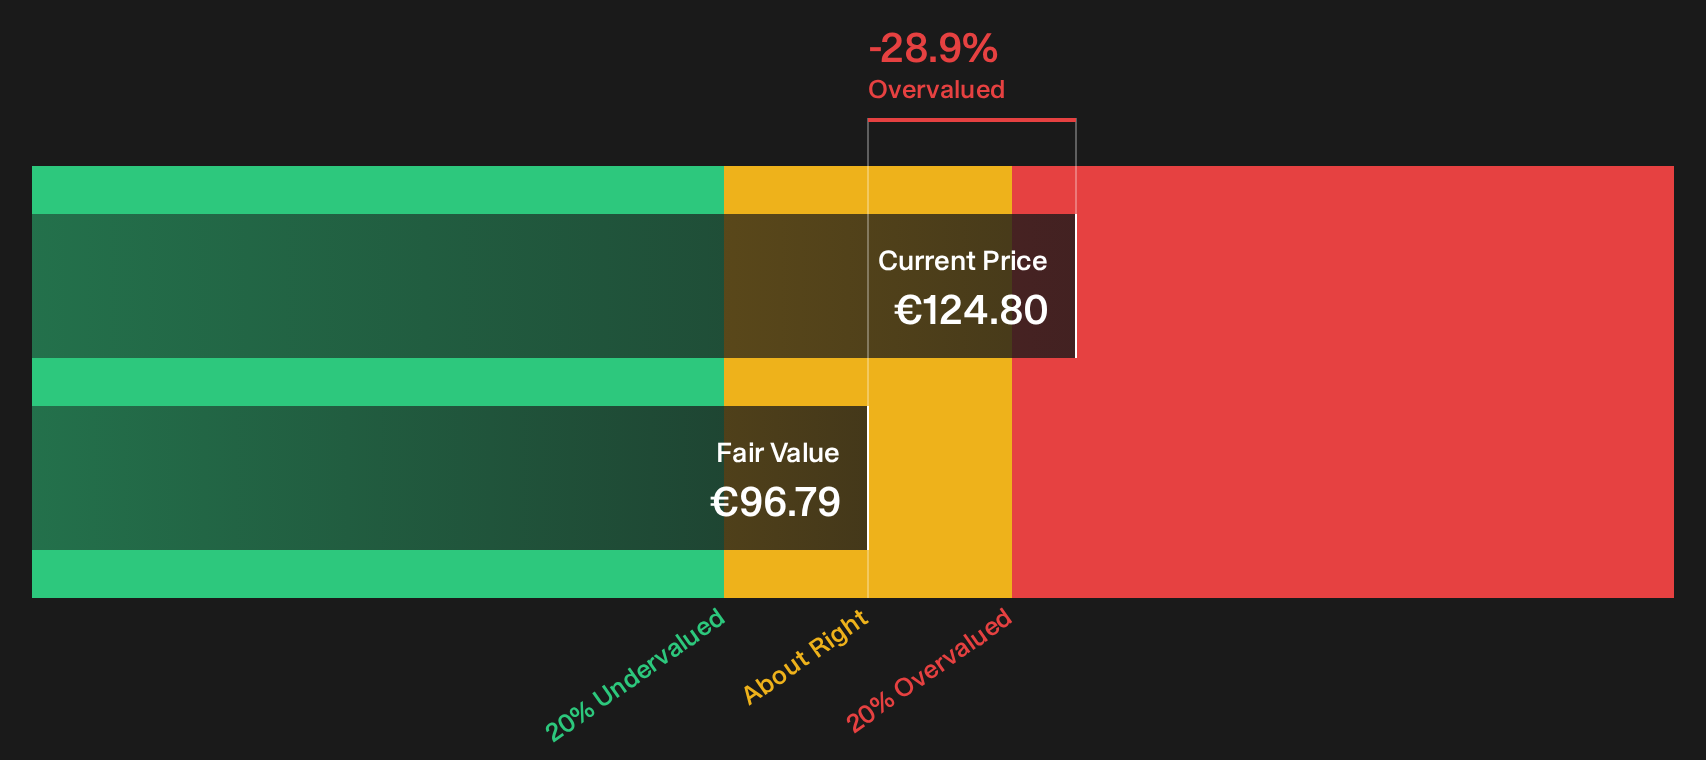
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Prysmian for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 197 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Prysmian so far, with both risk flags and clear upside angles in play, mean you need to weigh the trade off yourself and move before the narrative shifts. To see both sides laid out in one place, review the 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Prysmian?
Do not stop with Prysmian. Broaden your opportunity set now by stress testing your current watchlist against fresh ideas sourced from Simply Wall St screeners.
- Target potential mispricings by scanning a 197 high quality undervalued stocks that combine sturdy fundamentals with compressed valuations before the crowd catches on.
- Strengthen your income stream by reviewing a 163 dividend fortresses that focus on higher yield while still keeping an eye on resilience.
- Dial down portfolio risk by filtering for a 227 resilient stocks with low risk scores that prioritize sturdier financial profiles when markets get choppy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com