
Intel (INTC) Just Drew Fresh Attention, So What Is The Market Weighing?
Intel (INTC) is back in focus after Advantech expanded its WEDA powered Edge AI ecosystem, with Intel aligning its broad product portfolio and Open Edge platform to simplify Edge AI deployment at scale.
Recent trading has been choppy for Intel, with the share price down 6.4% over the past week even after a strong 29.6% 1 month share price return and a very large 194.4% year to date gain. The 1 year total shareholder return of 245.5% and 3 year total shareholder return of 230.3% point to powerful long term momentum that recent AI safety concerns and sector wide pullbacks have only partially cooled.
Spot 88 AI infrastructure stocks that could ride the same Edge AI buildout story Intel is plugged into through its work with Advantech and Open Edge platforms.After a near 200% surge this year and with only a fraction of a percent separating Intel’s share price from the average analyst target, the real issue is whether investors are now paying mostly for past excitement or for earnings that still are not reflected in the numbers.
Most Popular Narrative: 77% Undervalued
Intel closed at $115.93 while the most followed narrative pegs fair value at $500.93, a wide gap that frames the entire valuation debate. The share price now sits on one side of the argument and the narrative fair value sits far on the other.
compared to ARM, x86 does face an overhead penalty due to hypervisor translation on the assumption that ARM has been natively built. However the majority of applications are not natively built (aside from webpages), which would mean ARM would suffer a significant emulation penalty in terms of performance. additionally even with a natively compiled binary for ARM, x86 could still come out on top due to ARM being less cache efficient as the same application compiled for ARM generates larger code objects which could lower cache hit rate (depending on application)
See why 79 investors see Intel as 77% undervalued.
According to Suen, the narrative argues that Intel's x86 software ecosystem and potential foundry role are not fully captured by the current quote. That story supports a fair value of $500.93, which implies a 76.9% discount to the narrative estimate relative to the present share price.
Result: Fair Value of $500.93 (UNDERVALUED)
However, Intel’s story could be knocked off course if x86 software advantages narrow against ARM, or if its foundry ambitions fail to win meaningful third party demand.
Find out about the key risks to this Intel narrative.
Another View: What Intel’s P/S Ratio Signals
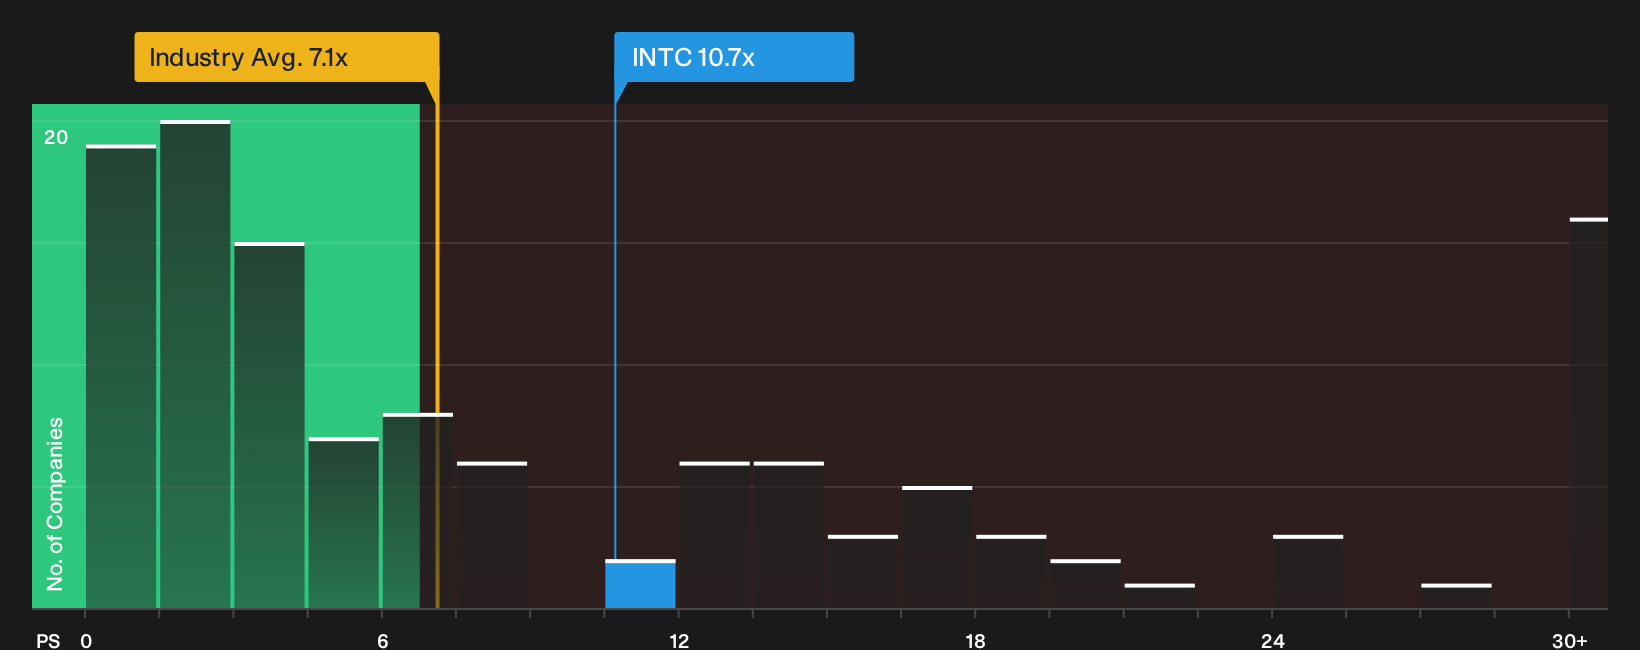
The narrative pegs Intel at $500.93, yet the market is already assigning a rich sales multiple. The P/S ratio sits at 10.7x, above the US Semiconductor industry on 7.1x, although below a peer average of 28x and near an estimated fair ratio of 11.1x.
That gap to the sector suggests limited room for error if revenue or margins disappoint, while the closeness to the fair ratio hints the market may already be pricing in a lot of the story. For an investor weighing Intel today, this may be more a question of sentiment than of undiscovered value.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Split sentiment around Intel is clear, so move quickly, study the numbers for yourself, then weigh up 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Intel?
If Intel has sharpened your interest, do not stop here. Fresh opportunities often sit just outside the obvious tickers you already follow.
- Target potential upside in companies that combine quality fundamentals with attractive valuations by running your filters through 17 high quality undiscovered gems.
- Protect your capital by focusing on stability first, then return, using the criteria packed into the 32 resilient stocks with low risk scores.
- Zero in on resilient businesses with strong finances so short term shocks matter less by scanning the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com