
Sea (SE) Stock May Be Stretched Given Today’s Earnings Power
Sea has given investors a rough ride over the past few years, and the latest stretch puts a sharper spotlight on one basic issue. Are you paying a fair price for the earnings the company is generating today?
- The stock is up 131.5% over the past 3 years, which makes the current valuation question more important for anyone considering fresh capital.
- The group relies heavily on turning its digital businesses into consistent profits, so the way earnings convert from underlying revenue can shape how comfortable you feel with the current P/E multiple.
- There is a second opinion on Sea worth weighing. See what analysts think Sea's shares could be worth.
The stock's next move may depend on whether its earnings are strong and reliable enough to support the price investors are being asked to pay today.
If you want to sanity check Sea against other valuation stories built around earnings, compare it with companies in the 31 high quality undervalued stocks
Does Sea Look Pricey on Earnings?
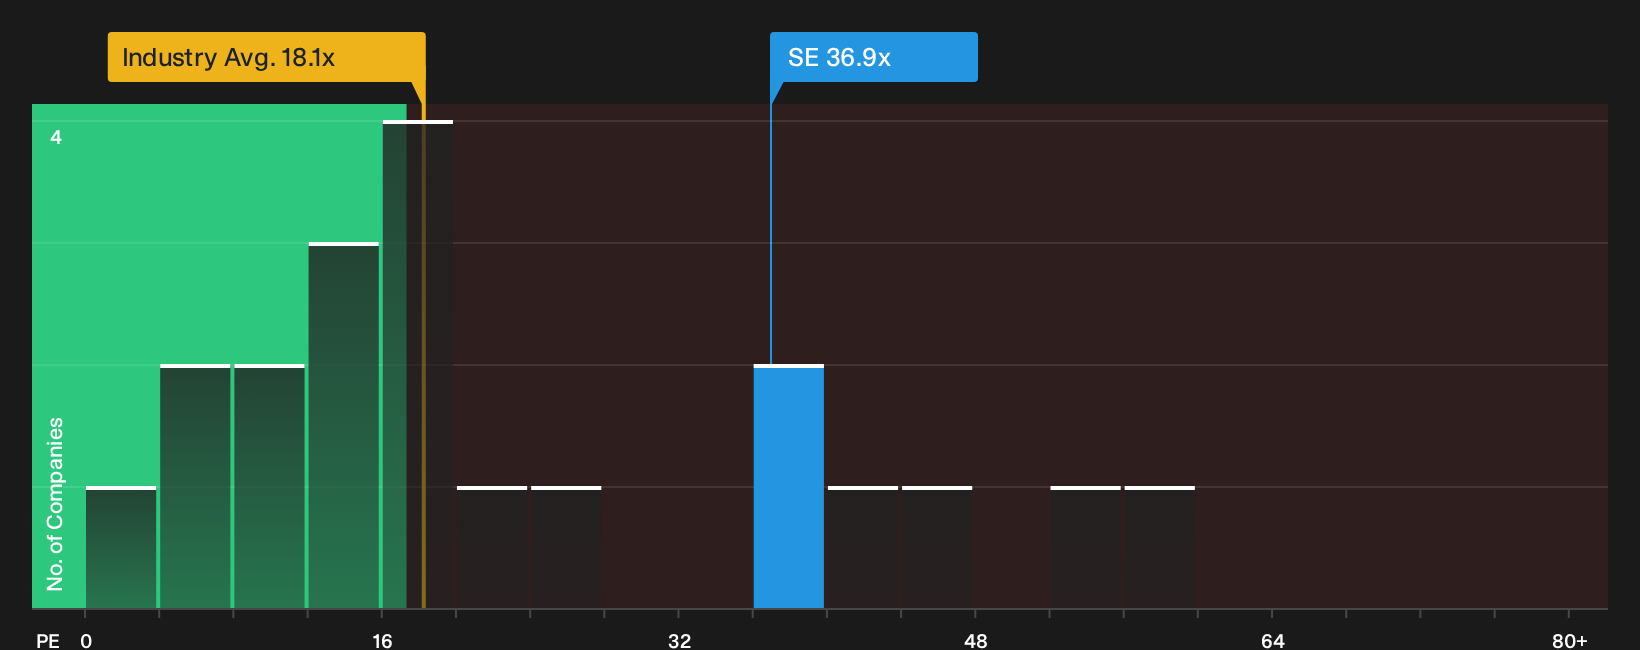
The P/E multiple suits Sea because earnings now sit at the center of how investors frame the story. On this measure, the stock trades on a P/E of 36.9x, which is well above the Multiline Retail industry average of 18.1x and also above the peer group on 23.1x. That is a clear premium price for each dollar of profit.
The Fair Ratio framework, which blends in Sea’s growth profile, margins, sector and risk, points to a lower P/E than the market is paying today. So the shares screen as overvalued on earnings relative to what that tailored benchmark suggests. For anyone considering Sea, the key question is whether the strength and durability of future profits are compelling enough to justify paying this kind of multiple. Explore the numbers behind Sea's P/E valuation.
The Sea Narrative: What Would Justify Today's Price?
Sea’s valuation puzzle only really starts to make sense once you spell out what would have to change in earnings power for the stock to be worth much more or much less than it is today. That is where Simply Wall St Narratives come in on the Community page. Each scenario anchors its number to a clear view on how Sea's growth, profitability and risk profile might evolve, giving you a reference point you can revisit as fresh results or updates arrive.
One of the top community narratives on Sea: 37% undervalued
"Current numbers, including strong revenue, EBITDA, and free cash flow alongside a weaker share price, suggest that the market is valuing Sea below what this narrative views as a reasonable reflection of the company’s business momentum."
Discover why this Narrative puts Sea at 37% undervalued.
Before acting on Sea's valuation, there is a final piece to check
Price tags are only part of the story for Sea, because our broader review has also highlighted specific risks that could change how you view the whole setup. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com