
Perseus Mining Was A Fight Over How Much Risk The Cash Could Carry
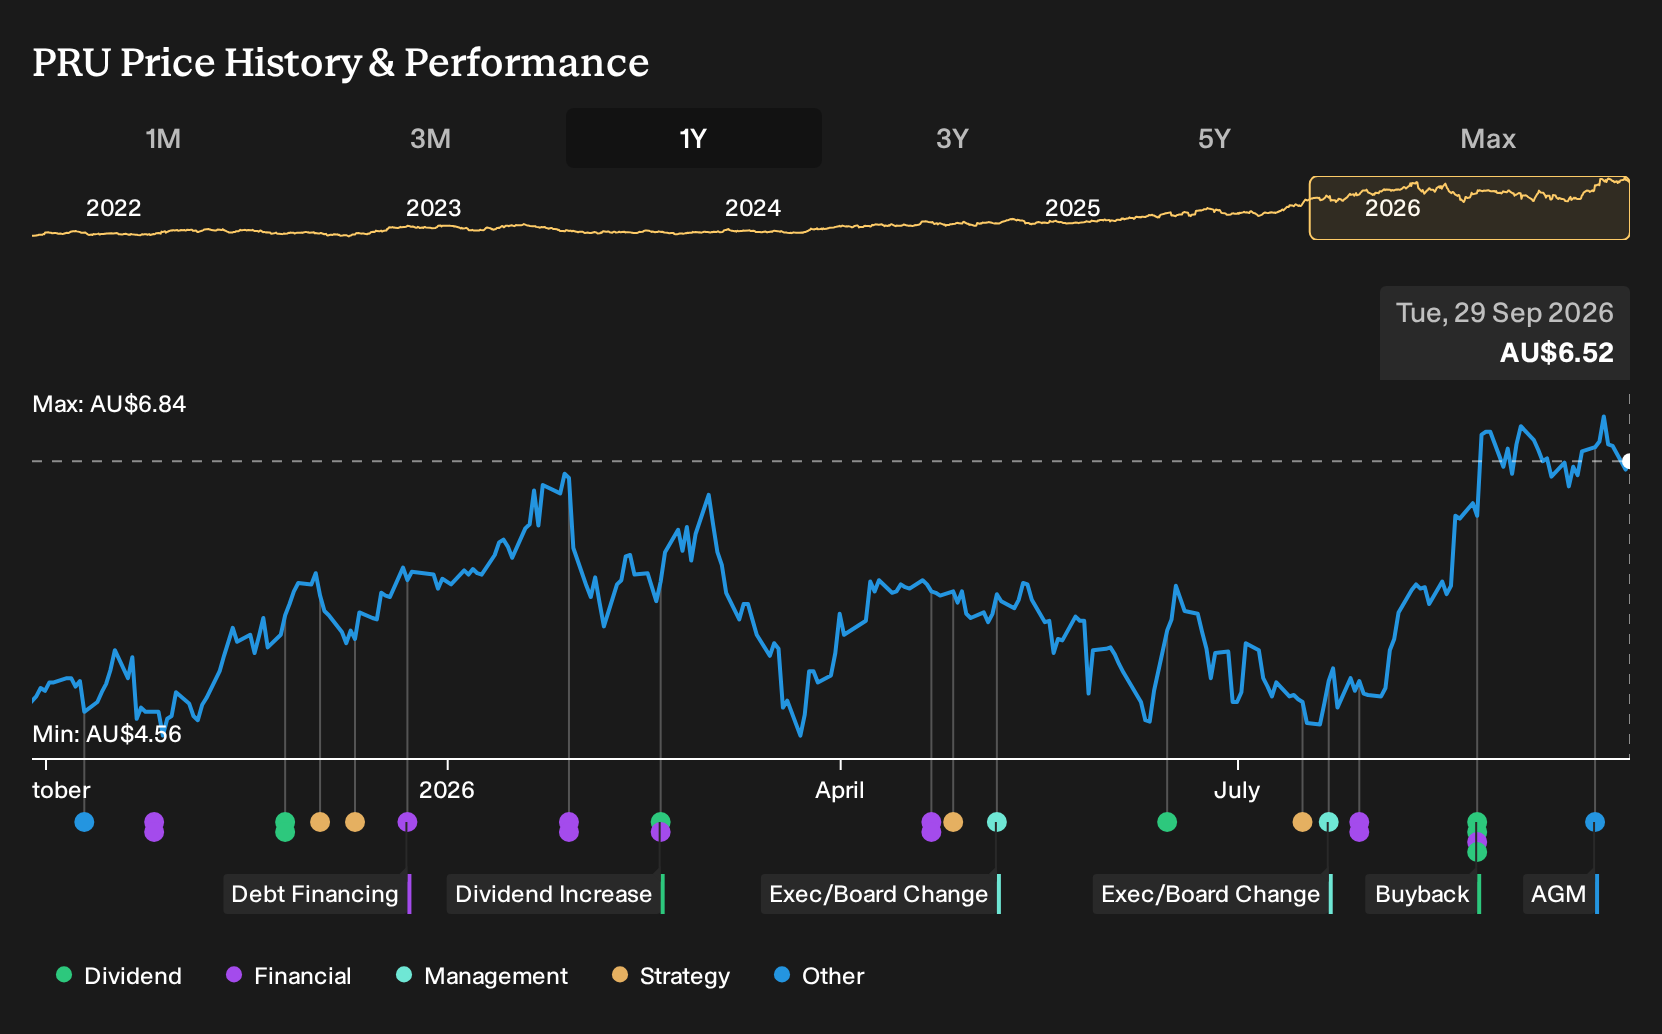
Perseus Mining has just stretched its buyback to A$150 million and doubled its interim dividend, and investors have responded with sharp interest in the story. For Perseus Mining shareholders, the return over the past year was 36.0%, including dividends. If you had been weighing a purchase on 29 September 2025, with analysts split between bullish expansion plans and worries over West African risk, what would have mattered most to your call?
This theme extends beyond Perseus Mining. See which of 36 elite gold producer stocks may still merit a closer look.
The Two Perseus Mining Stories Investors Had On The Table
The shares cost A$4.84 at the start of the period, and anyone looking at Perseus Mining then was really choosing between two very different stories about what came next.
The bullish view pointed to a Fair Value of A$5.8, the price implied if things played out as hoped, anchored in early delivery at Nyanzaga and CMA underground, with tight cost discipline and a strong net cash position enabling acquisitions.
The cautious narrative sat at a Fair Value of A$4.26 and highlighted reliance on elevated gold prices, rising all in site costs and concentration in West Africa as key sources of earnings risk.
What The Results Changed For The Perseus Mining Debate
Perseus Mining delivered higher revenue of US$875.4m and higher net income of US$264.7m in H2 2026 compared with H2 2025, and net margin improved from 28.9% to 30.2%. That outcome supported the optimistic story that focused on margins and cash generation. Concentration in West Africa and reliance on gold prices were not resolved, so the evidence still cut both ways overall.
The practical takeaway is simple. When a thesis hinges on better profitability, it is important to track whether net margin moves in the forecast direction in later results before upgrading conviction in any miner.
What Today's Perseus Mining Price Already Assumes
Perseus Mining now trades at A$6.52, after a one year gain of 36.0%. The selected Narrative argues that its Fair Value sits below this price, reflecting concern that the recent share move outpaced what its risk profile and project pipeline might justify.
The key thread is simple. A buyer today would need to judge that Perseus can keep funding growth projects and shareholder returns while absorbing commodity, regulatory and regional shocks without meaningful pressure on cash flow.
"Perseus Mining's recent surge in revenue and cash margins is heavily reliant on historically elevated gold prices, leaving future earnings vulnerable to any sustained downturn in the price of gold as global macroeconomic volatility and potential de-dollarization dampen gold's safe-haven appeal, likely resulting in declining top-line revenue and margin compression."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 35% below our estimate - builds an affiliate platform sharing infrastructure as partners pursue higher margin strategies.
- Company 2 - 49% below our estimate - ramps up specialist technicians as aging machinery and new technology increase maintenance needs.
- Company 3 - 20% below our estimate - integrates a large acquisition while upgrading mines and plants to raise throughput.
Those are three of them. See every one of the 5 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com