
Primoris Services (PRIM) Could Be 38% Undervalued On Solar Progress And Buybacks
Primoris Services (PRIM) is back in focus after reporting progress on six utility-scale solar projects, naming Matt Tetrault as President of Renewables, and completing a roughly $100 million share repurchase authorization.
Despite the fresh solar milestones and buyback news, Primoris Services is coming off a tougher stretch, with a 90 day share price return that is down 20.08% and a year to date share price decline of 43.13%. However, the 5 year total shareholder return of 205.68% points to a very different longer term story.
Scan beyond Primoris Services and see how other infrastructure and renewables contractors are priced by reviewing our curated list of 39 power grid technology and infrastructure stocks.
After a sharp pullback, even as Primoris Services completes solar projects and a US$100 million buyback, is it more compelling to step in now or wait for a cleaner entry once the valuation picture comes into focus?
Most Popular Narrative: 38% Undervalued
Primoris Services closed at $74.28, while the most followed narrative pegs fair value near $119.79. The gap hinges on how convincingly the business can turn its current project pipeline into stronger earnings.
Operational execution, improved productivity, and a favorable project mix in core segments (especially Utilities) are driving company-wide gross margin improvement and improved cash conversion, structurally enhancing Primoris's earnings and free cash flow profile.
See why 13 investors see Primoris Services as 38% undervalued.
Result: Fair Value of $119.79 (UNDERVALUED)
Still, the narrative around Primoris Services can shift quickly if renewable project issues deepen or if class action lawsuits and guidance cuts weigh further on investor confidence.
Find out about the key risks to this Primoris Services narrative.
Another View: Primoris Services Through The P/E Lens
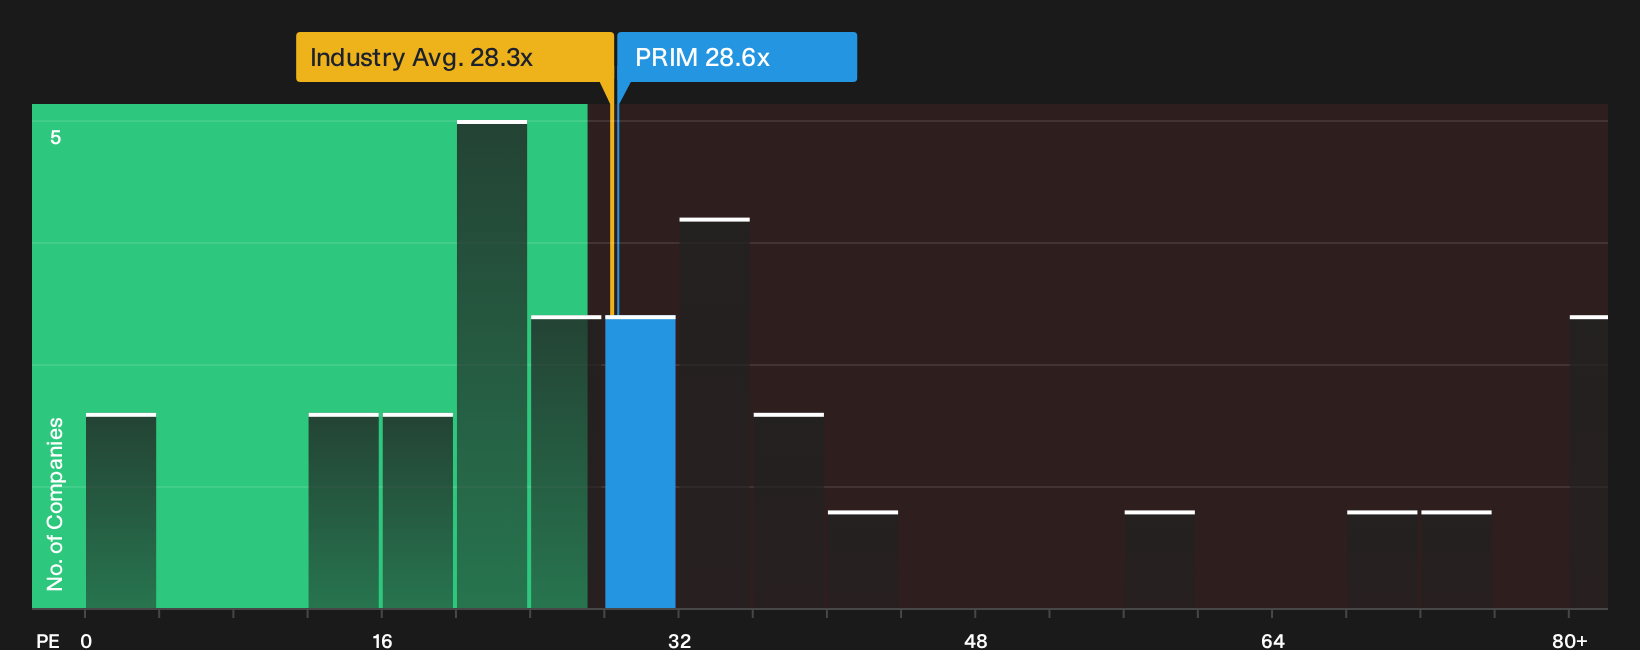
There is a different read on Primoris Services once you zoom in on how the P/E ratio stacks up. The stock trades on about 28.6x earnings, which is slightly higher than the US Construction industry at 28.3x, yet a touch lower than the peer average of 29.4x.
The fair ratio sits much higher at 43.9x. That gap leaves room for the market to either move closer to that fair ratio or stay anchored near industry levels. For an investor, the real question is whether today’s earnings quality justifies the higher fair ratio or argues for sticking with the more cautious market multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment across Primoris Services is clearly split, and that is exactly when fresh eyes on the data can be most useful. Move quickly, review both the concerns and the upside, and weigh the balance of 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Primoris Services?
Do not stop with Primoris Services when there are other angles to test your thesis. Use the screeners below to pressure test your next move.
- Target steadier returns by focusing on resilient companies in the 32 resilient stocks with low risk scores that aim to keep drawdowns in check when conditions get choppy.
- Hunt for quality at a discount by scanning the 31 high quality undervalued stocks, where stronger fundamentals and pricing may occasionally collide.
- Prioritize balance sheet strength by reviewing the list of solid balance sheet and fundamentals (25 results) and avoid missing businesses that pair financial resilience with solid operating profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com