
Nvidia And 2 AI Infrastructure Stocks Tied To Data Center Demand
AI regulation just took a softer turn, and that shift is rippling straight into the companies building the chips, data centers, and infrastructure behind the headlines. With the White House favoring voluntary principles and Washington talking up U.S. AI leadership, capital is following the pipes, not just the apps. This piece walks through three stocks exposed to that news backdrop and how their role in AI infrastructure could matter for your portfolio decisions.
The three companies highlighted below are only a small sample of the idea, and the wider screen surfaced 55 more US AI infrastructure and data center beneficiaries with equally compelling stories that are not covered here.
If you want to move from headlines to hard filters and identify which tickers best fit your own risk and return preferences, go straight to the US AI Infrastructure and Data Center Beneficiaries screener.
NVIDIA (NVDA)
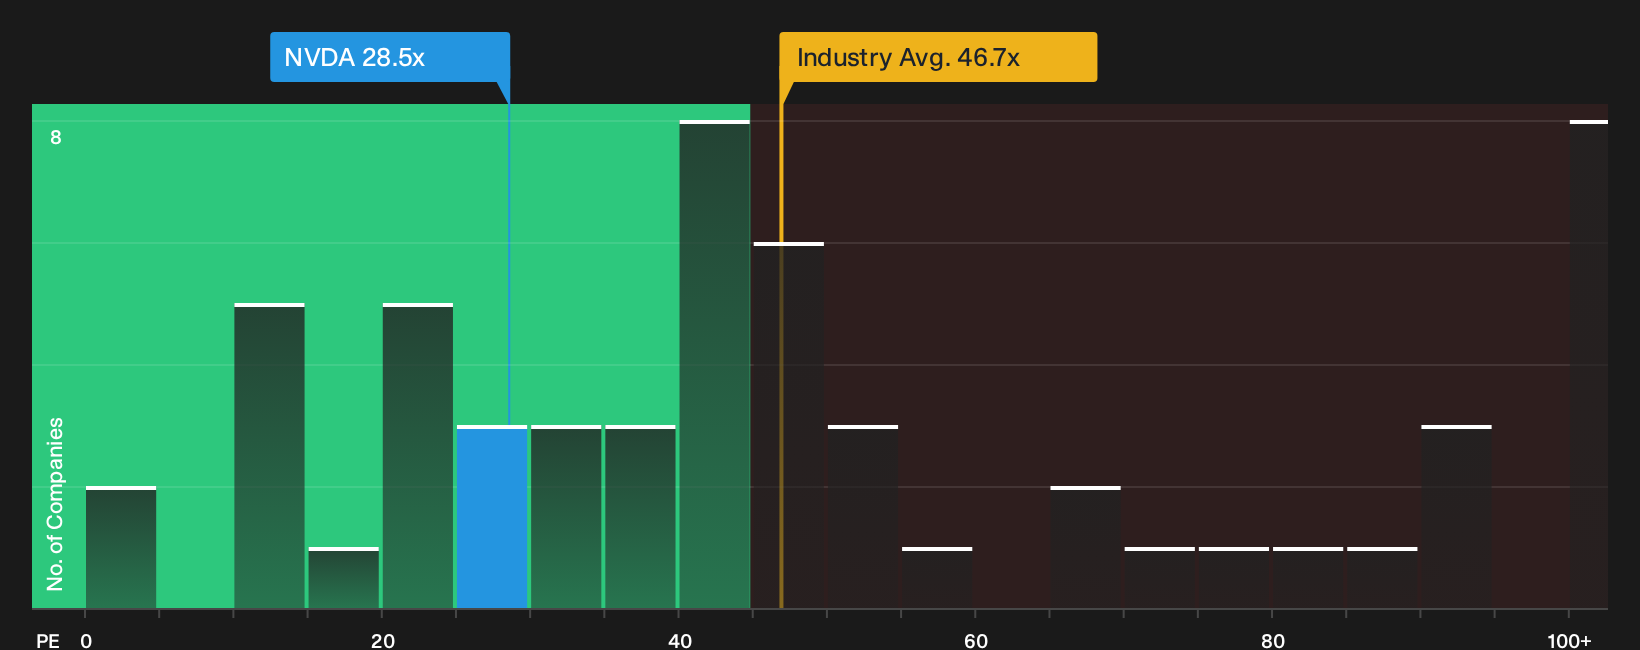
NVIDIA is a prominent example of the AI infrastructure theme in this screen, designing the GPUs and data center platforms that power many of the AI factories behind today’s buildout and turning that role into a very large global business.
NVIDIA operates two main engines. Compute & Networking, focused on AI data center platforms, contributes about US$275.4b of revenue, while Graphics adds roughly US$27.6b. The group carries a market value of about US$5.5t, reflecting its scale in AI hardware and infrastructure.
"$400b annual revenue assumes Nvidia continues to be dominant in GPU design and AI software stack. Successful competition from AMD, Intel, or a Chinese firm could affect this position. Uptake of an open-source, cheaper, or better platform than Nvidia's CUDA could significantly affect Nvidia's competitive position and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, reducing demand for Nvidia's higher-margin products."
For investors, a shift in how developers build and deploy AI models could have implications for the pricing power behind those margins.
That pricing power question is exactly what sits at the heart of the full narrative for NVIDIA, which unpacks how AI adoption, competition and CUDA risk could be evolving.
Cohu (COHU)
Cohu sits right in the plumbing of the AI buildout, supplying the test and inspection equipment chip makers use before AI processors, accelerators and memory ever reach a data center rack.
Cohu, a US$3.1b semiconductor equipment provider, earns about US$523 million from Semiconductor Test & Inspection, supplying handlers, contactors and analytics software that help qualify advanced chips for AI and data centers worldwide.
"Cohu is capitalizing on the surge in high-performance computing and the complexity of modern semiconductors (AI infrastructure, GPUs, HBM, and display drivers) by rolling out advanced, configurable handler platforms and test solutions. This is positioning the company for potential market share gains and higher equipment sales, directly impacting top-line revenue."
What matters next for Cohu is how one emerging demand pattern in AI hardware filters through to test intensity, pricing power and eventual margins.
Those test intensity and margin questions are exactly what the full narrative for Cohu unpacks, revealing how Cohu’s AI exposure, pricing power, and cycle risks could be evolving.

Camtek (CAMT)
Camtek plugs into the AI infrastructure story through the inspection and metrology tools that help keep yields high on advanced chips feeding new data centers, and its role in that part of the supply chain is what investors are watching most closely.
"Although Camtek is securing large orders tied to AI related advanced packaging through 2027, its non advanced packaging businesses such as CMOS image sensors and other 2D inspection tools are described as only stable with small growth, which could cap overall revenue expansion once the current AI and HBM cycle normalises and dilute earnings leverage."
The risk reward balance for Camtek increasingly hinges on how one concentrated driver shapes both future demand and the durability of margins.
That concentration risk is only half the story, and the full narrative for Camtek shows how Camtek’s AI cycle, broader exposure and margin path could be quietly accelerating.

Curious About Alternative Stock Paths?
Fresh ideas do not stay under the radar for long. Before the next breakout gathers momentum and prices start flying, scan these curated lists while it matters and act now.
- Spot steadier candidates that can anchor a portfolio while riskier bets swing around by starting with a curated list of solid balance sheet and fundamentals (25 results).
- Target companies already generating real cash from AI, not just headlines and hype, by running through the curated 37 profitable AI stocks that aren't just burning cash.
- Explore potential strength in metals tied to infrastructure and electrification themes by checking a hand picked 17 top copper producer stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com