
Does Zacks Strong Buy Upgrade Change The Bull Case For Horace Mann Stock?
- Horace Mann Educators Corporation was recently added to the Zacks Rank #1 list after analysts lifted current year earnings estimates by 6.2% over the past 60 days.
- This higher earnings outlook sits alongside Horace Mann Educators' work with Crayola on educator-focused programs, underscoring how its educator niche and partnerships contribute to its core insurance and retirement franchises.
- We will now look at how Horace Mann Educators' upgraded earnings outlook could influence the broader investment narrative around the business.
Scan beyond Horace Mann Educators and this Crayola partnership by reviewing our curated 17 high quality undiscovered gems that also serve specialized customer niches with focused business models.
Horace Mann Educators Investment Narrative Recap
To own Horace Mann Educators, you need to be comfortable with a focused bet on the K 12 educator market and a business built around auto, home, life, retirement, and supplemental benefits for that group. The near term swing factor is whether recent profit momentum and digital investments keep supporting policy growth, while catastrophe losses and interest rates remain key operational wildcards.
The Crayola partnership is directionally helpful but not a primary earnings driver today. The bigger risk still comes from concentration in an aging educator customer base and potential pressure on public school staffing. If those pressures intensify, new policy flow and annuity contributions could soften even if engagement programs perform well.
The recent Crayola professional development workshops look most relevant here because they deepen Horace Mann Educators’ access to active teachers inside schools. That sort of embedded presence can support lead generation into auto, property, retirement, and supplemental lines, especially as the firm leans on tools like its Catalyst lead management system.
For you as an investor, the question is execution. If these education focused initiatives translate into more contacts, better retention, and higher take up of retirement and group products, they can help offset risks tied to an aging educator cohort and weather exposed P&C margins. If engagement remains more at the brand level than transactional, the financial impact could stay modest.
Horace Mann Educators’ current profit pool of $177.3 million is projected in consensus models to reach $226.1 million by 2029. This implies a roughly $48.8 million earnings increase alongside revenue assumptions that reach $2.3 billion in that same year and require 9.9% yearly top line growth from here.
Uncover why Horace Mann Educators' fair value indicates a 24% potential upside to its current price that may not last much longer.
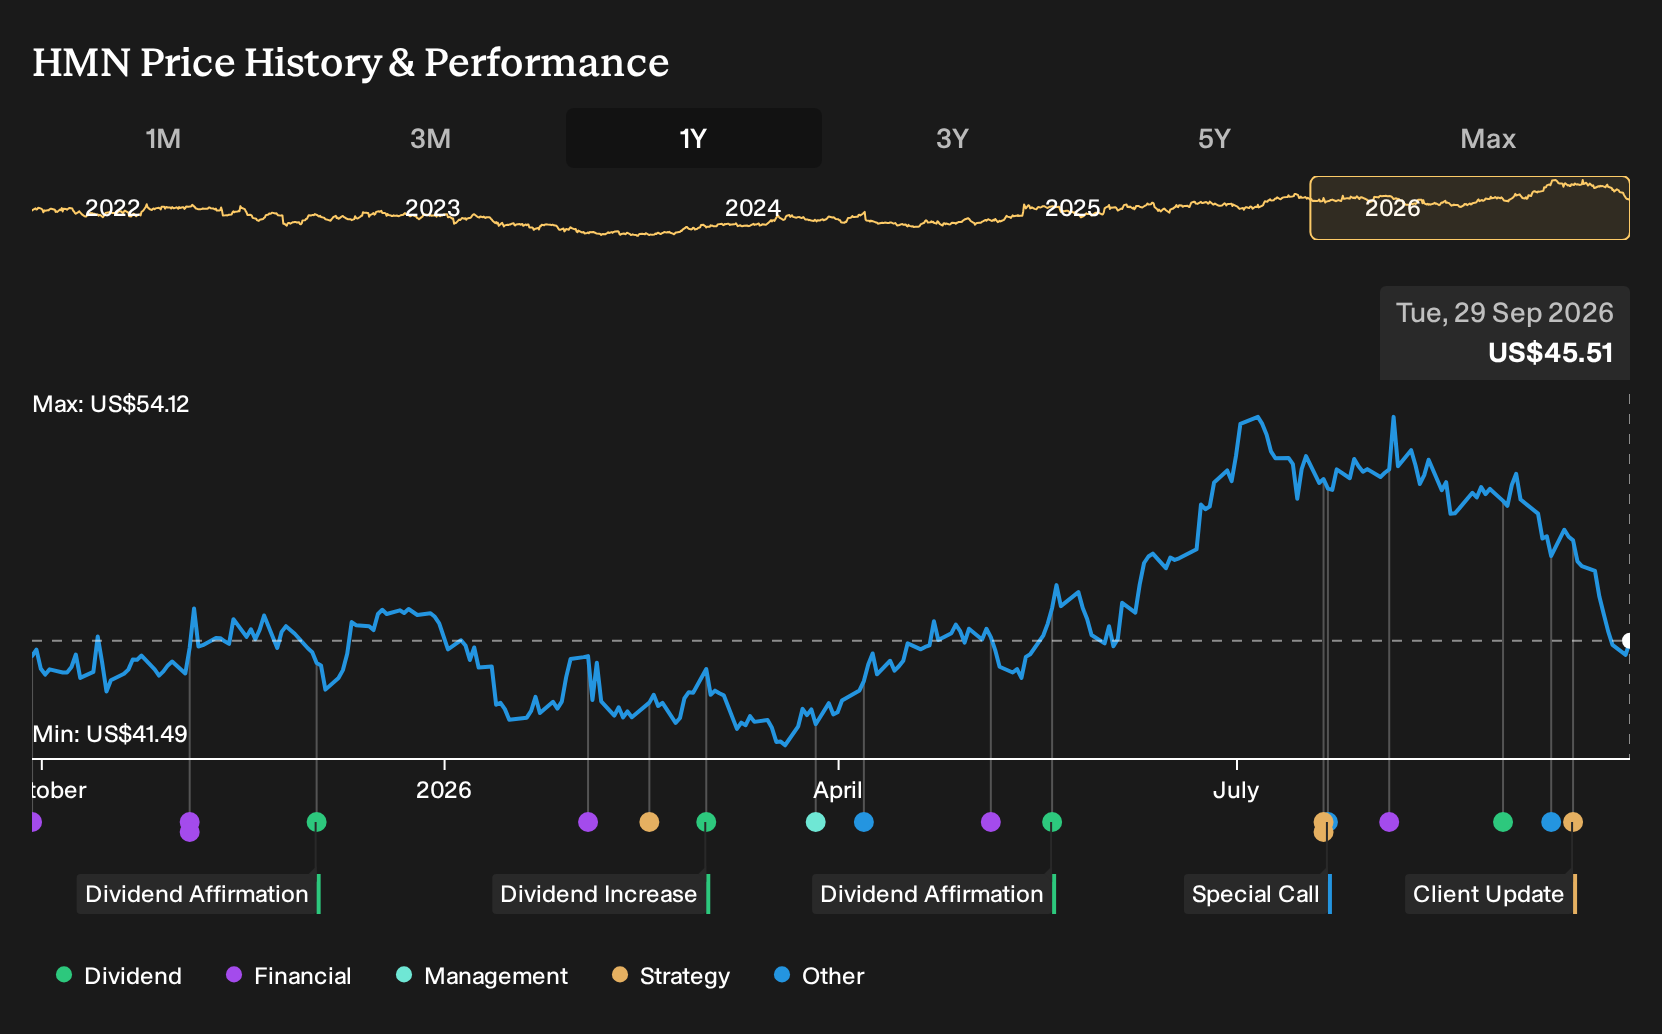
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Horace Mann Educators research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Horace Mann Educators. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Horace Mann Educators' overall financial health at a glance.
Looking For More Ideas Beyond Horace Mann Educators?
If the Horace Mann Educators story has you thinking about where else focused business models and resilient balance sheets might turn into opportunity, the Simply Wall St Screener can help you cast a wider net without losing discipline.
- For readers who want financially robust businesses that can better handle shocks, filter for companies using our list of solid balance sheet and fundamentals (25 results), which pairs sturdy finances with underlying fundamental strength.
- If your priority is capital preservation with fewer unwanted surprises, narrow the field with our 32 resilient stocks with low risk scores, which highlights businesses with more resilient risk profiles.
- For those hunting beyond well known tickers, surface potential off the radar opportunities using our 17 high quality undiscovered gems, which combines quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com