
Is Middlesex Water (MSEX) Expensive As Mixed Valuation Signals Cloud The Recent Rebound?
Middlesex Water (MSEX) has drawn fresh attention after recent share performance, with the stock closing at US$53.20. Investors are weighing a regulated utility model in relation to modest year and multi year return figures.
Recent trading has been choppy for Middlesex Water, with a 1 day share price gain of 1.43%, a 30 day share price return down 9.04%, and a 5 year total shareholder return down 43.82%. This points to fading long term momentum despite a positive year to date share price return of 5.83%.
Scan how Middlesex Water compares with other regulated utilities by reviewing a curated set of list of solid balance sheet and fundamentals (25 results) that may better match your risk and return preferences.
For Middlesex Water, the recent bounce sits between two explanations. Is the latest move a read on improving business trends, or simply sentiment snapping back after a rough multiyear stretch?
Preferred P/E of 20.9x for Middlesex Water: Is it justified?
Valuation on Middlesex Water hinges on a P/E of 20.9x at the last close of $53.20, which points to a richer pricing than several comparison points even before you look at cash flows.
The P/E multiple compares the current share price with earnings per share. For a regulated utility, this ratio often reflects how much investors are willing to pay for relatively steady earnings and modest growth expectations instead of rapid expansion.
Middlesex Water shows some support for this premium. Earnings have grown by 3.4% per year over the past 5 years, with profit growth of 10.6% in the most recent year and net profit margins at 23.2% compared with 22.1% a year earlier. Earnings are also forecast to increase by 9.44% per year, although these forecasts are described as not significantly high and are expected to rise slower than the broader US market.
Where valuation starts to look stretched is in the comparisons. The 20.9x P/E is above the Global Water Utilities industry average of 16.8x and above the peer average of 20.2x. This implies investors are paying more for each dollar of earnings than both the wider industry and a closer peer set. It also exceeds an estimated fair P/E of 18.8x, a level that the market could shift toward if sentiment or growth expectations cool.
Explore the SWS fair ratio for Middlesex Water.
Result: Price-to-earnings of 20.9x (OVERVALUED).
Still, the richer P/E on Middlesex Water could be tested if earnings growth slows or if regulators tighten allowed returns on its core utility assets.
Find out about the key risks to this Middlesex Water narrative.
Another View on Middlesex Water’s Value
A second lens tells a tougher story. Our DCF model points to a future cash flow value of $40.72 per share for Middlesex Water, well below the current $53.20 price. This suggests the stock screens as overvalued on this metric. So which signal should carry more weight for you right now?
Look into how the SWS DCF model arrives at its fair value.
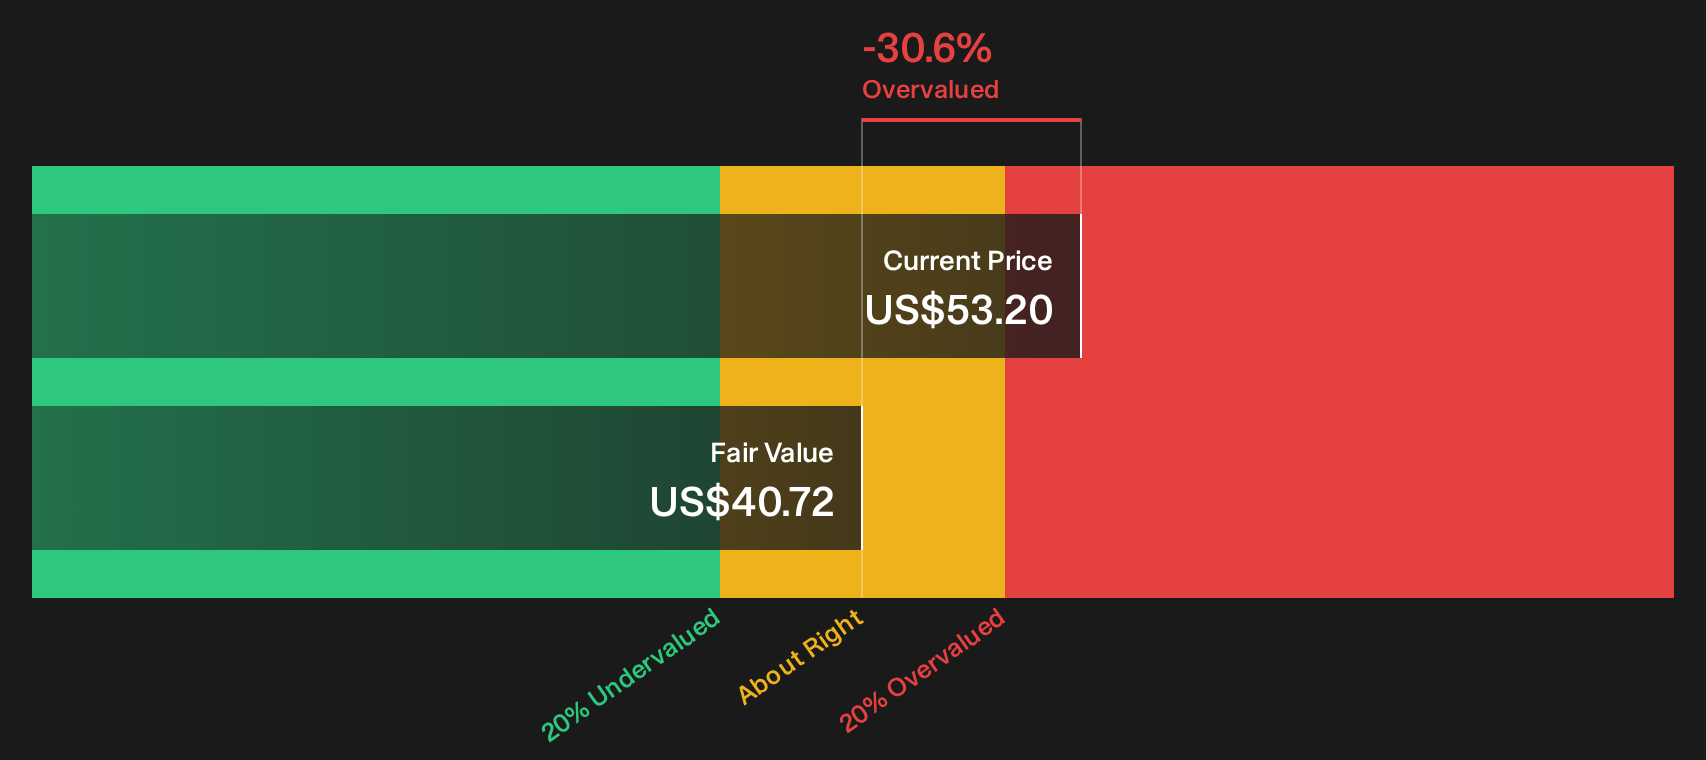
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Middlesex Water for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Middlesex Water so far. For a clearer stance, review the full picture yourself, including the 3 key rewards and 2 important warning signs.
Looking for more Middlesex Water sized investment ideas?
If Middlesex Water has you reassessing where your money works hardest, do not stop at a single ticker. Broader idea hunting often reveals better fits.
- Target steadier potential outcomes by focusing on resilient businesses in the 32 resilient stocks with low risk scores.
- Hunt for value by reviewing companies that appear mispriced on quality and fundamentals in the 31 high quality undervalued stocks.
- Seek future standouts early by scanning financially solid smaller players in the 17 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com