
RemeGen (SEHK:9995) Highlights Telitacicept Progress, Is The Stock Still Below Fair Value?
Why the Telitacicept Data Matters for RemeGen Stock
RemeGen (SEHK:9995) is back in focus after collaborator Vor Bio shared a post hoc Phase 3 analysis of telitacicept in generalized myasthenia gravis at a major neuromuscular medicine conference.
The update centers on how deeply and how long patients maintained clinical responses over 48 weeks, along with a review of tolerability, giving investors fresh information on one of RemeGen's key autoimmune assets.
Recent trading has been choppy. RemeGen's share price jumped 5.06% in the last day to HK$74.8, yet the 30-day share price return is down 10.74% and the 1-year total shareholder return has fallen 36.18%. However, the 3-year total shareholder return is almost 2x, which suggests momentum has cooled while longer term holders still sit on sizeable gains.
Spot similar biotech setups to RemeGen by scanning a hand picked list of autoimmune and healthcare specialists using the 132 healthcare AI stocks.Bulls see telitacicept strength and a long pipeline, while bears point to recent share price declines and shrinking earnings. Which side does RemeGen’s current valuation lean toward as the next step to assess?
Price-to-Earnings of 6.1x: Is it justified?
RemeGen currently trades at a P/E of 6.1x, which screens as cheap relative to both the Hong Kong Biotechs sector and its closest peers based on recent earnings.
The P/E ratio compares the current share price to earnings per share. For a research driven drug developer like RemeGen, it effectively shows how much investors are paying for each unit of reported profit, and how confident the market is that those profits will hold up.
Analysts expect earnings to decline by an average of 39.1% per year over the next three years and revenue to fall 5.8% per year, so a low P/E can reflect concerns that current profit levels are not sustainable. At the same time, the stock is trading at a 29.6% discount to the SWS estimate of fair value based on future cash flows, and analysts in aggregate expect the share price to rise by 56.4% from the current HK$74.8 level. This points to a very different read on long term potential.
Compared with the Hong Kong Biotechs industry average P/E of 18.3x and a peer average of 30.1x, RemeGen’s 6.1x multiple is far lower and implies the market is pricing in a sharp reset in profitability. The SWS fair P/E estimate of 10.1x sits well above the current ratio and signals a level the valuation could move toward if sentiment around the earnings outlook improves.
Explore the SWS fair ratio for RemeGen.
Result: Price-to-Earnings of 6.1x (UNDERVALUED)
Still, RemeGen carries real risk if telitacicept stumbles in later studies or if earnings, which have been shrinking at a 39.1% annual decline, continue to weigh on sentiment.
Find out about the key risks to this RemeGen narrative.
Another View on RemeGen’s Valuation
The low 6.1x P/E paints RemeGen as inexpensive, yet the SWS DCF model points to a different anchor for judgement. On that measure, the HK$74.8 share price trades about 29.6% below an estimated future cash flow value of HK$106.32. This frames the discount around long term cash generation rather than near term earnings pressure.
Look into how the SWS DCF model arrives at its fair value.
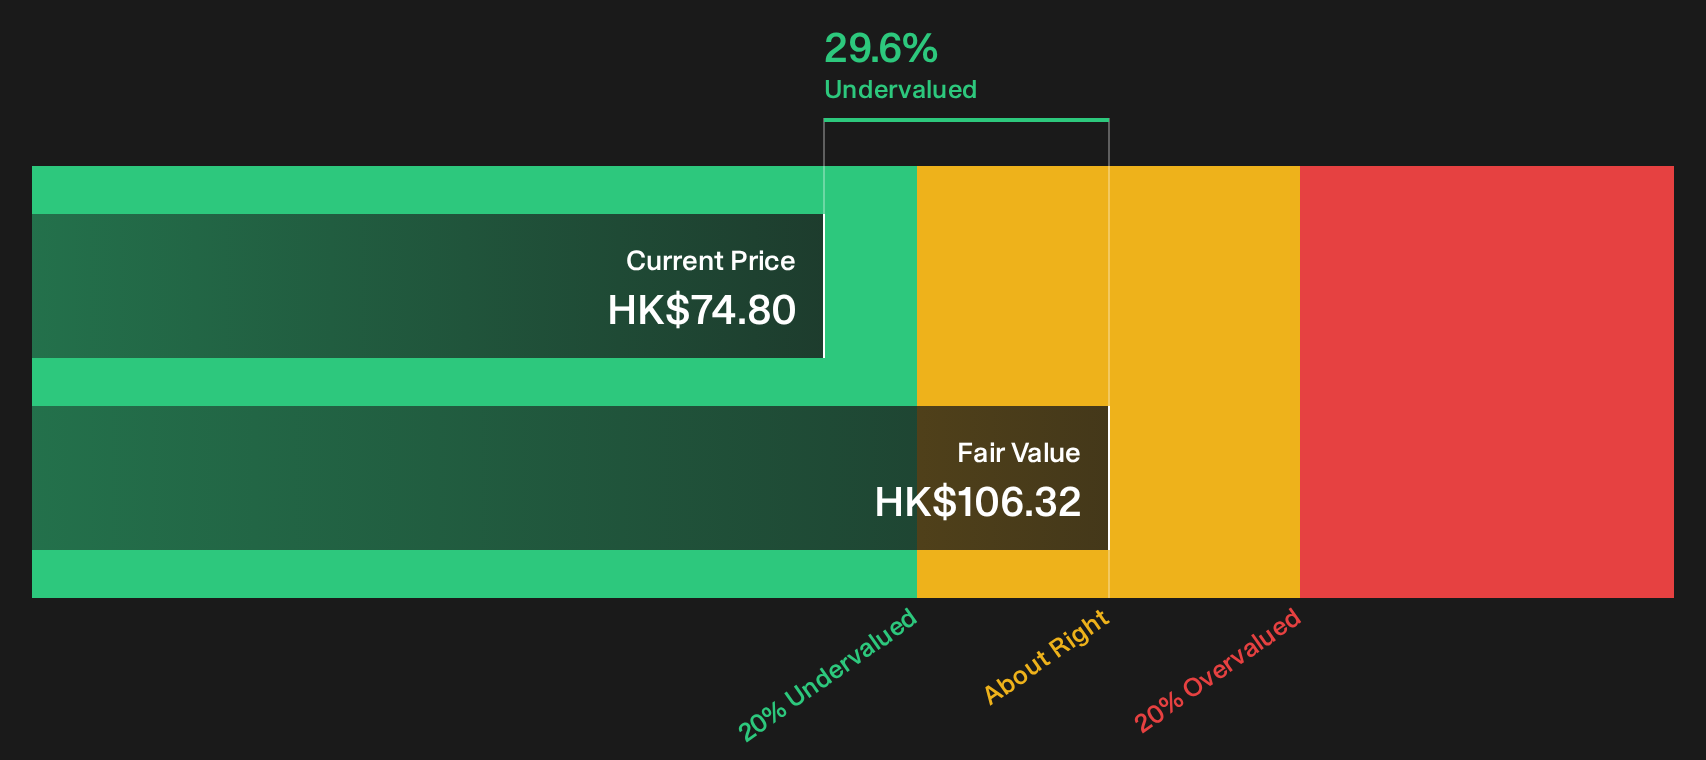
Both lenses flag potential mispricing, but they rest on very different assumptions about RemeGen’s earnings path and cash conversion. Which one feels closer to how you think this business actually matures?
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out RemeGen for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 200 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between the cautious tone around RemeGen and the potential upside on offer is reasonable. Move quickly, review the numbers, and weigh both angles with the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond RemeGen?
If RemeGen has your attention, use that momentum. Broaden your watchlist now with fresh ideas before the next move happens without you.
- Target potential mispricing by scanning a focused pool of attractively valued companies through the 200 high quality undervalued stocks.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (204 results) that can help support cash flows through tougher periods.
- Boost your income focus by tracking a curated group of yield heavyweights using the 164 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com