
Cognex (CGNX) Launches In Sight 1750 As Its Undervalued Narrative Faces A Reality Check
Cognex’s In-Sight 1750 launch and why it matters for investors
Cognex (CGNX) has rolled out its In-Sight 1750 wafer and panel identification system, aimed at semiconductor manufacturers that want fewer production interruptions, better traceability, and higher throughput without major line redesigns.
Cognex shares trade at US$59.67, with a year-to-date share price return of 61.58% and a 1-year total shareholder return of 32.57%. However, the 90-day share price performance is down 16.32%, which suggests recent enthusiasm has cooled even as longer-term momentum remains intact.
Look beyond Cognex and this wafer ID launch by reviewing a curated set of 92 robotics and automation stocks that are also aiming to automate complex manufacturing bottlenecks.
Cognex has enjoyed a strong year-to-date surge before giving back ground over the past three months. The key question now is straightforward: lock in exposure at today’s US$59.67, or wait for a potentially lower entry point and risk missing the opportunity?
Most Popular Narrative: 26% Undervalued
Cognex’s most followed narrative pegs fair value at $80.42 versus the recent $59.67 share price, so the current quote assumes a lot less than that scenario while still pricing in meaningful execution on AI vision and customer expansion.
Strong growth in logistics, packaging, and consumer electronics end markets, driven by investments in e-commerce, traceability, and quality automation, is broadening Cognex's customer base and reducing reliance on cyclical sectors. This diversification supports more stable, long-term revenue growth.
See why 30 investors see Cognex as 26% undervalued.
Result: Fair Value of $80.42 (UNDERVALUED)
Still, Cognex’s reliance on cyclical areas like automotive and semiconductor, along with pricing pressure from lower cost Asian rivals, could quickly challenge that 26% undervalued thesis.
Find out about the key risks to this Cognex narrative.
Another view on Cognex’s valuation
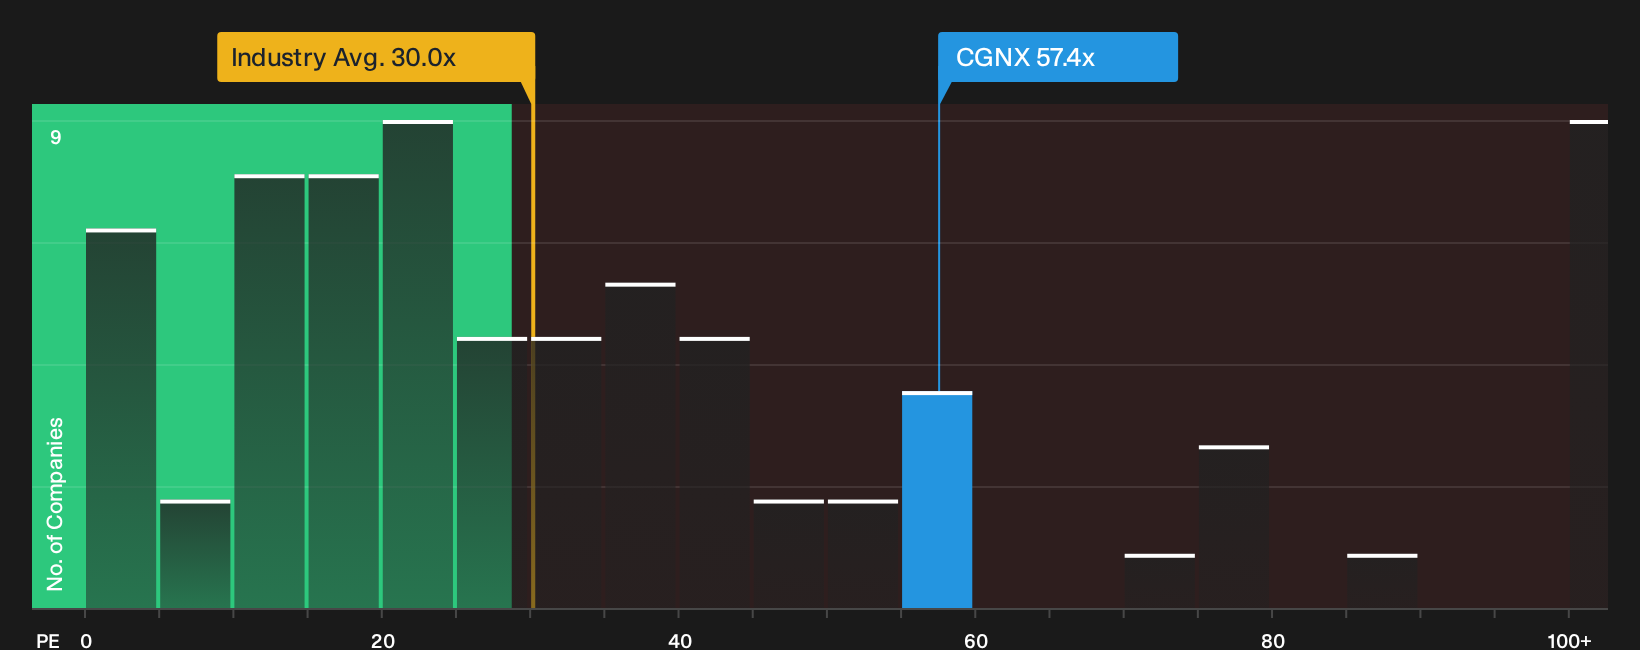
Analyst narratives suggest Cognex is undervalued, yet the current P/E of 57.4x tells a different story. That is almost double the US Electronic industry at 30x and well above a fair ratio of 33.3x, which points to richer pricing and less margin for error if growth expectations soften.
For a closer look at what this gap between current P/E, peers, and the fair ratio could mean for your risk and return expectations, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and rich expectations around Cognex leaves you undecided, move quickly to test the numbers yourself and shape your own thesis using the 3 key rewards.
Looking for more investment ideas beyond Cognex?
If Cognex has sharpened your interest in automation and quality-focused businesses, do not stop here. Broader opportunities often sit just outside your current watchlist.
- Target potential mispricings by scanning a curated pool of strong fundamentals with the 31 high quality undervalued stocks.
- Strengthen your downside protection by focusing on companies that pair robust finances with resilience using the 32 resilient stocks with low risk scores.
- Unearth underfollowed opportunities that still show solid metrics by filtering through the 17 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com