
Tutor Perini (TPC) Backlog Story Keeps Undervalued Case In Focus
Tutor Perini (TPC) is drawing fresh attention after Zacks highlighted the contractor as a top-ranked value pick. The firm cited a Zacks Rank #1 rating and an A grade on its value scorecard.
Recent trading has been choppy for Tutor Perini, with the 30-day share price return down 5.47% even though the year-to-date share price return is 21.10% and the 1-year total shareholder return is 28.80%. The 3-year total shareholder return is very large at close to 10x, pointing to strong long term momentum.
Scan beyond Tutor Perini and look for other construction and infrastructure contractors that screens identify as potentially mispriced in the 32 high quality undervalued stocks.
The share price has cooled while analyst targets and intrinsic value estimates sit much higher, leaving a wide gap to explain. Is Tutor Perini already fairly priced, or does that spread still point to value?
Most Popular Narrative: 26% Undervalued
The most followed valuation narrative puts Tutor Perini's fair value at $113.25 versus the last close at $83.98, so the story turns on whether that gap is justified by the project pipeline and profitability assumptions.
Record backlog growth, now at an all-time high of $21.1 billion (up 102% YoY), provides strong visibility and multi-year revenue predictability, as a series of major projects ramp up over the next several years.
Sustained federal and state infrastructure funding, particularly for large-scale transit and civil projects (Midtown Bus Terminal, Sepulveda Transit Corridor, Indo-Pacific Defense contracts), is fueling robust project pipeline expansion, favorably impacting both future revenue and long-term earnings growth.
See why 21 investors see Tutor Perini as 26% undervalued.
Result: Fair Value of $113.25 (UNDERVALUED)
Still, the Tutor Perini story can change quickly if mega projects run into cost disputes or delays, or if large public contracts face funding or regulatory setbacks.
Find out about the key risks to this Tutor Perini narrative.
Another View on Tutor Perini’s Valuation
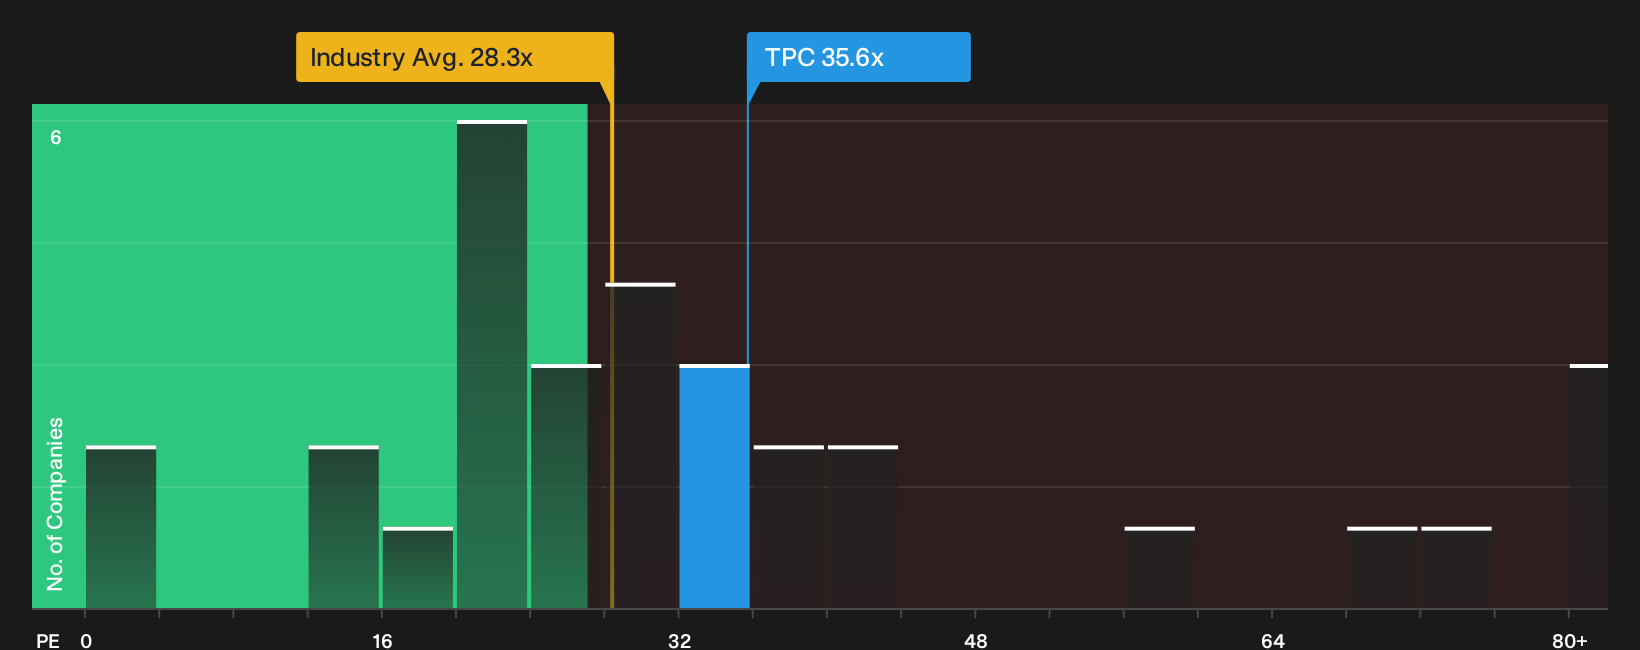
The first story around Tutor Perini leans heavily on discounted future cash flows and analyst targets that frame the stock as undervalued. A different lens uses the current P/E ratio of 35.6x versus 28.5x for the US Construction group and 26.7x for peers, even though the fair ratio sits at 50x.
That combination of a higher multiple than sector and peer averages, yet below the fair ratio, highlights valuation risk if earnings disappoint and potential upside if the market moves closer to that fair ratio. Which side of that tradeoff appears more plausible based on your own expectations for the backlog, profitability and project execution?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Tutor Perini's value and risk profile only matter if you test them against the raw numbers yourself, then move quickly to lock in your own stance with the full breakdown of 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Tutor Perini?
If Tutor Perini has your attention, do not stop there. Broaden your watchlist with other ideas sourced from disciplined screeners so you are not relying on a single story.
- Target resilient balance sheets and steady fundamentals with a curated list of solid balance sheet and fundamentals (25 results) that helps you focus on financial strength first.
- Hunt for potential mispricings by scanning the 16 high quality undiscovered gems that most investors are not watching yet.
- Prioritize capital preservation by reviewing a 30 resilient stocks with low risk scores that filters for companies with lower measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com