
Will Digital Inspection Pilot Change UTI's Narrative at Universal Technical Institute Stock
- myKaarma previously announced a pilot with Universal Technical Institute to embed its digital multi-point inspection software into UTI's new Atlanta automotive technician program, with the platform provided at no cost during the initial phase.
- The collaboration pushes Universal Technical Institute's training closer to real dealership service workflows, which may influence how employers view the quality and job readiness of its graduates.
- Next, we will look at how Universal Technical Institute's investment narrative could be influenced by this digital inspection training pilot.
Scan how Universal Technical Institute fits into a broader skills and training theme by comparing it with a curated shortlist of companies in our list of solid balance sheet and fundamentals (25 results).
Universal Technical Institute Investment Narrative Recap
To own Universal Technical Institute, you need to believe the demand for hands on, career focused training in transportation, trades, and healthcare holds up, and that management converts that demand into stronger earnings over time. The myKaarma pilot in Atlanta looks incremental rather than transformational. It may help course quality, but it does not rewrite the short term story.
The near term swing factor still sits in enrollment trends and execution on new campuses and programs. The biggest risk remains spending heavily on expansion that does not convert into profitable student volume. Regulatory shifts and funding rules also stay in the background as a constant, hard to control overhang.
The digital inspection pilot lines up with one of Universal Technical Institute’s bigger operational themes. That theme is tighter alignment with employers and more digital workflows inside its training. Integrating tools that service departments already use can help students step into real jobs with less ramp up, which matters when employers have other education options.
Announcements around Concorde Career Colleges growth and new program launches are still more central to the major catalysts, because they touch revenue scale and margin potential across the group. This Atlanta initiative instead speaks to quality of offering and differentiation. That matters for student outcomes and retention, but it does not remove the broader execution and regulatory risks.
Universal Technical Institute's analyst narrative points to revenues of US$1.1b and earnings of US$95.7 million by 2029, based on revenue growth assumptions of 9.4% per year and an earnings increase of about US$53 million from current earnings of US$42.7 million.
Uncover why Universal Technical Institute's fair value indicates a 130% potential upside to its current price that may not last much longer.
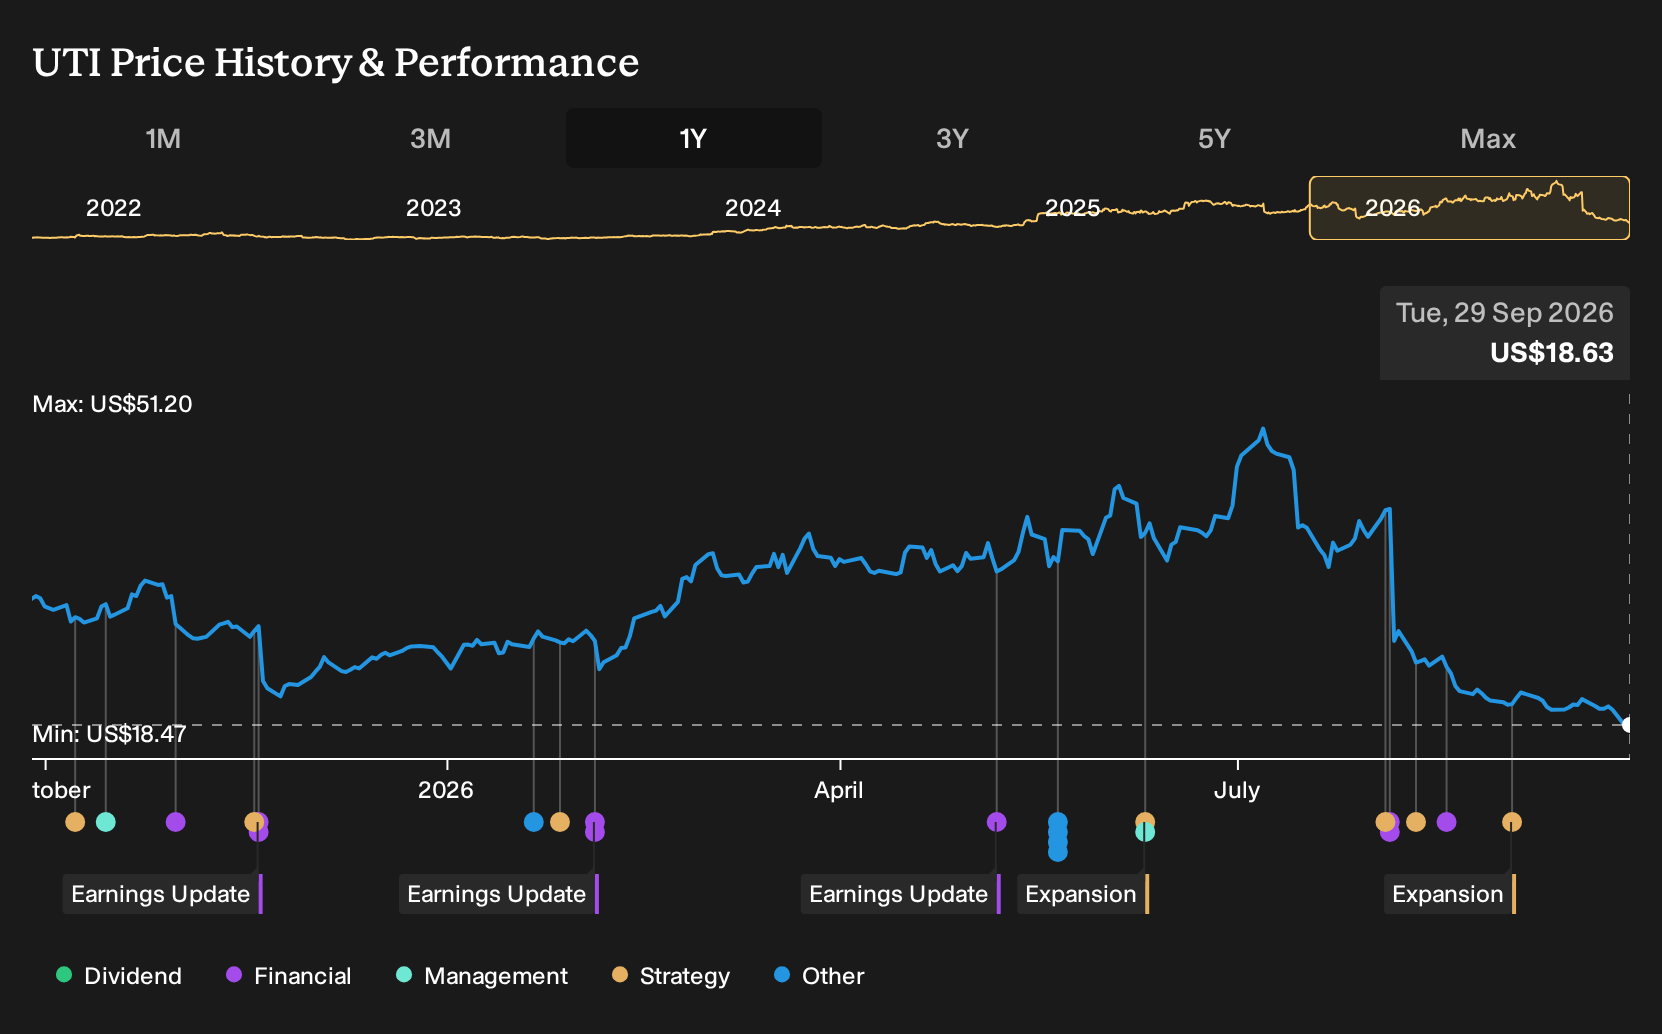
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community sit between about US$22.86 and US$42.50 per share, which already shows how far opinions on Universal Technical Institute can spread. Add to this the risks around heavy expansion spend, possible regulatory shifts, and integration complexity, and you get a wide field of outcomes you should explore further.
Explore another Universal Technical Institute fair value estimate, including one that suggests it could be worth just $22.86!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Universal Technical Institute research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Universal Technical Institute. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal Technical Institute's overall financial health at a glance.
Looking For More Investment Ideas Beyond Universal Technical Institute?
If you want to pressure test your view on Universal Technical Institute, it helps to see how other businesses with different profiles stack up side by side in the Simply Wall St Screener.
- For investors who care most about balance sheet strength and fundamentals, compare Universal Technical Institute with a list of solid balance sheet and fundamentals (25 results) that meet those criteria.
- If you are hunting for mispriced quality, line up Universal Technical Institute next to a 16 high quality undiscovered gems that may be flying under the radar.
- When risk control is the priority, stress test your thesis by weighing Universal Technical Institute against a 30 resilient stocks with low risk scores that screen well on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com