
How Higher Treasury Yields Could Affect BBVA Argentina Stock and Turkish Bank Shares
When the 10 year Treasury yield hovers near 5.24% and investors whisper about 5.5% as a pressure point for stock valuations, fixed income and equity markets start to feel like two sides of the same trade. Rising borrowing costs, richer yields on “risk free” government bonds and shifting demand for Treasuries can all reshape which stocks feel the heat and which benefit. This article walks through three stocks exposed to these Treasury market cross currents, showing how the same macro shock can create opportunity for some investors and a reason for others to stay cautious.
The stocks profiled below are only a starter set, and the same screen pulled out 18 more large-cap banks, dealers and trading firms with equally detailed stories around Treasury and rates activity that are not covered here.
If you want to go straight to the source, analyze the full universe and identify your own highest-conviction angles, head into the Fixed-Income Trading and Treasury-Market Intermediaries screener.
Banco BBVA Argentina (BASE:BBAR)
Banco BBVA Argentina links the screener theme to the real economy through its mix of retail, corporate and treasury activities in a market where government bonds and local rates matter for everyday banking returns.
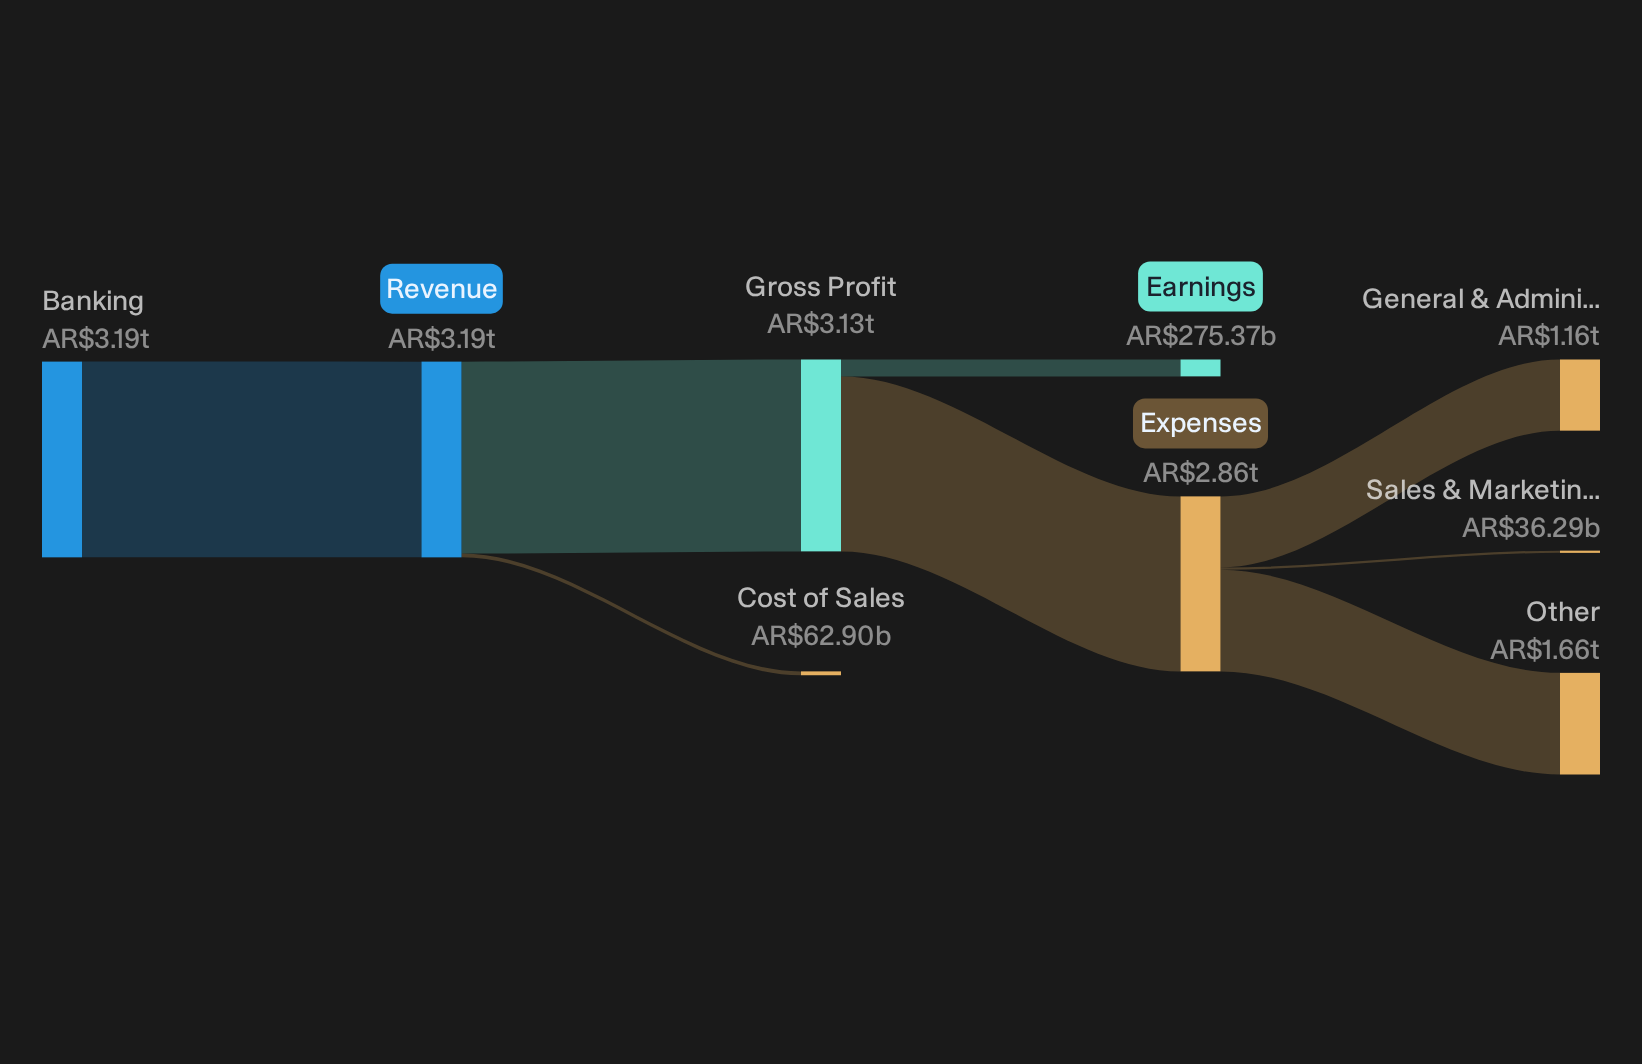
Banco BBVA Argentina runs a full-service retail and corporate bank across Argentina, where its banking segment produces ARS3,193,743 million of revenue and the stock carries an equity value of about ARS4,365.6b.
"Ongoing economic volatility, inflation, and dollarization threaten loan growth, deposit stability, and recurring revenue despite regulatory reforms and macroeconomic improvements."
What happens to BBVA Argentina’s earnings power if a single assumption about how it prices and funds its bond-heavy balance sheet breaks?
If that balance sheet assumption is starting to look fragile, read the full narrative for Banco BBVA Argentina to see how inflation, funding and bond pricing could be decoupling beneath the surface.
Akbank T.A.S (IBSE:AKBNK)
Akbank T.A.S links the fixed income and treasury theme to everyday banking in Turkey, where its trading desk, loan book and fee businesses all sit on the same balance sheet that reacts to interest rate swings and bond repricing.
Akbank T.A.S runs a broad retail, SME and corporate bank in Turkey and abroad, generating about TRY318.8b from Treasury, Other and Unallocated activities, TRY144.8b from Consumer and Private Banking, and TRY136.4b from Commercial, Corporate and SME Banking, with a market value near TRY364.5b.
"Superior risk management, innovative digital strategies, and cross-border capabilities enable robust profitability and resilience throughout economic cycles."
What that resilience looks like in practice will hinge on how one quiet shift in the rate and bond mix filters through funding costs.
That funding pivot is the hinge. Read the full narrative for Akbank T.A.S to see how Akbank T.A.S balances rate risk with fee income, capital and digital scale.

Türkiye Is Bankasi (IBSE:ISCTR)
Türkiye Is Bankasi plugs into the fixed income and treasury theme through its treasury transactions and investment activities, while still being a broad universal bank where everyday lending, insurance, and fee businesses help balance interest rate and bond market swings.
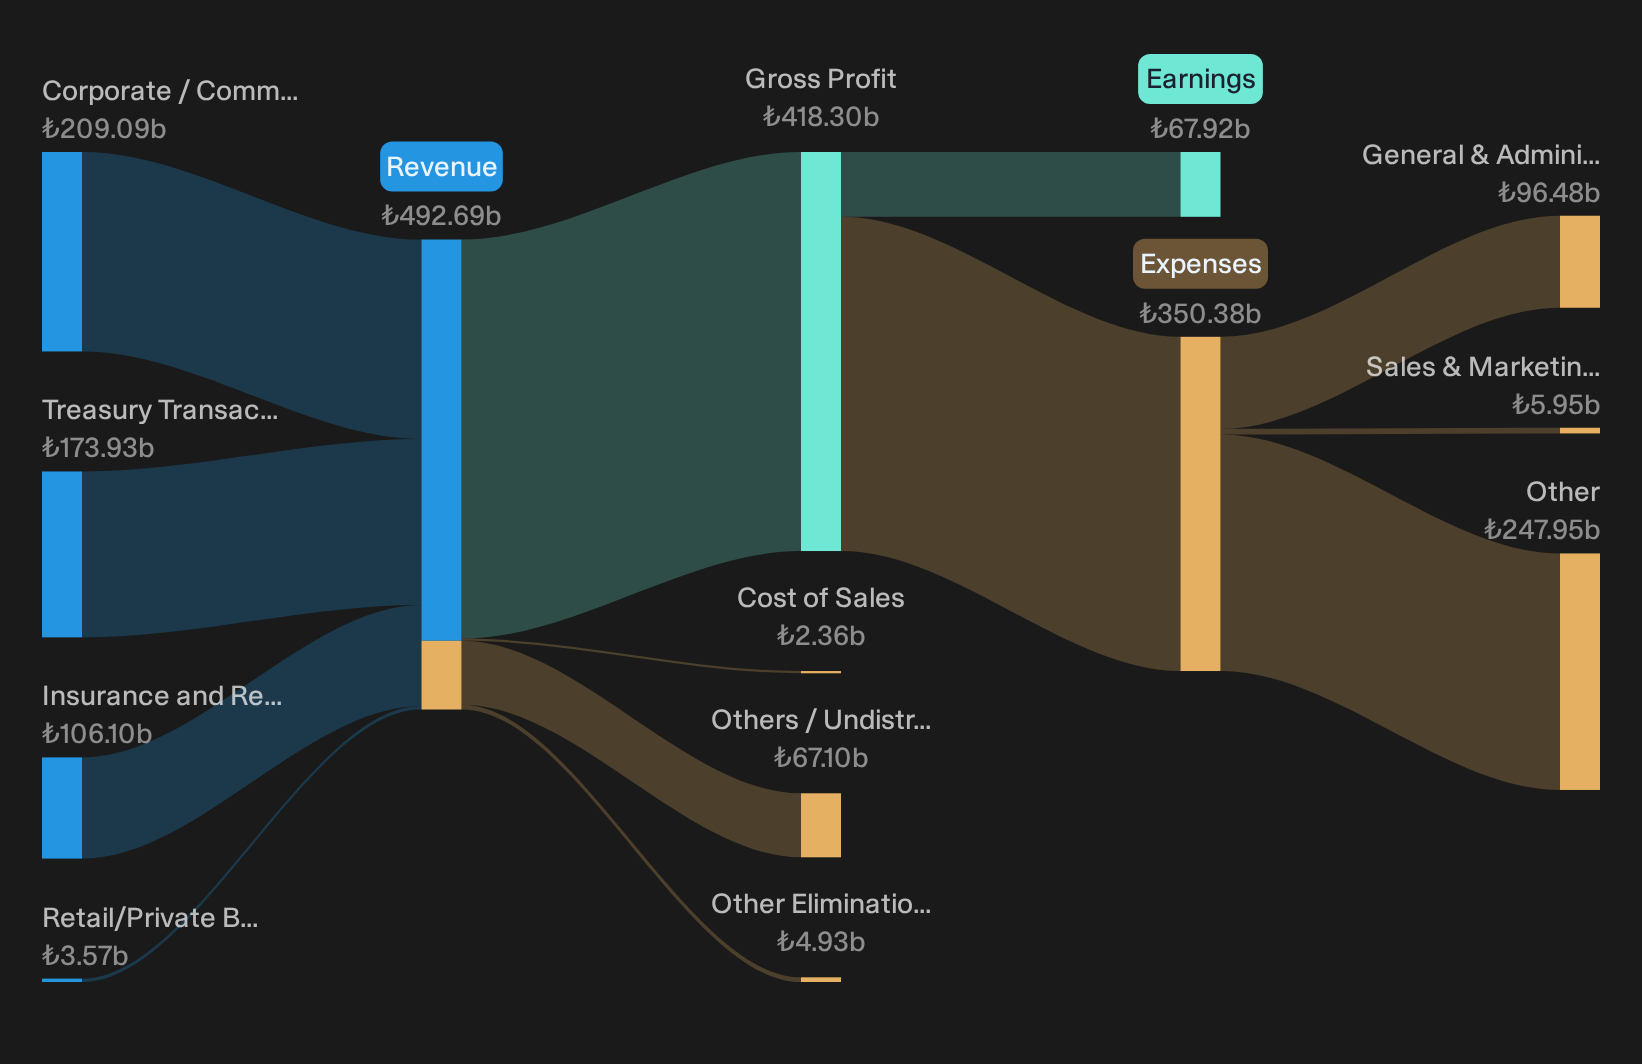
Türkiye Is Bankasi generates TRY209.1b from Corporate and Commercial Banking, TRY173.9b from Treasury Transactions and Investment Activities, TRY106.1b from Insurance and Reinsurance, and TRY3.6b from Retail and Private Banking, with a market value around TRY366b.
For investors tracking how higher global yields ripple into large Turkish lenders, Türkiye Is Bankasi offers a mix of balance sheet sensitivity and fee-heavy cushioning that frames the interest rate story in a more diversified way.
"Structurally lower deposit costs, digital expansion, and strong fee growth position the bank for accelerated earnings, enhanced margins, and superior cost efficiency over competitors."
What happens to that margin story if one quiet shift in funding costs or bond pricing upends the current balance between cheap deposits and fee revenue?
If that balance looks like it could flip faster than expected, read the full narrative for Türkiye Is Bankasi to see whether Türkiye Is Bankasi’s earnings engine is quietly accelerating.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes, early momentum and under the radar stocks can get repriced fast while it matters. Do not get caught reacting. Consider acting early instead.
- Spot cash rich businesses before the crowd starts chasing them by scanning the curated list of solid balance sheet and fundamentals (204 results) and filter for balance sheets that can handle tougher conditions.
- Explore potential trend shifts in power demand and grid upgrades by checking companies in the 39 power grid technology and infrastructure stocks that link cash generation to long term infrastructure needs.
- Track miners that could benefit if gold sentiment swings again by reviewing the hand picked group inside the 36 elite gold producer stocks while they are still under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com