
Is $400 Million Convertible Notes Altering The Investment Case For Delek US Holdings (DK)?
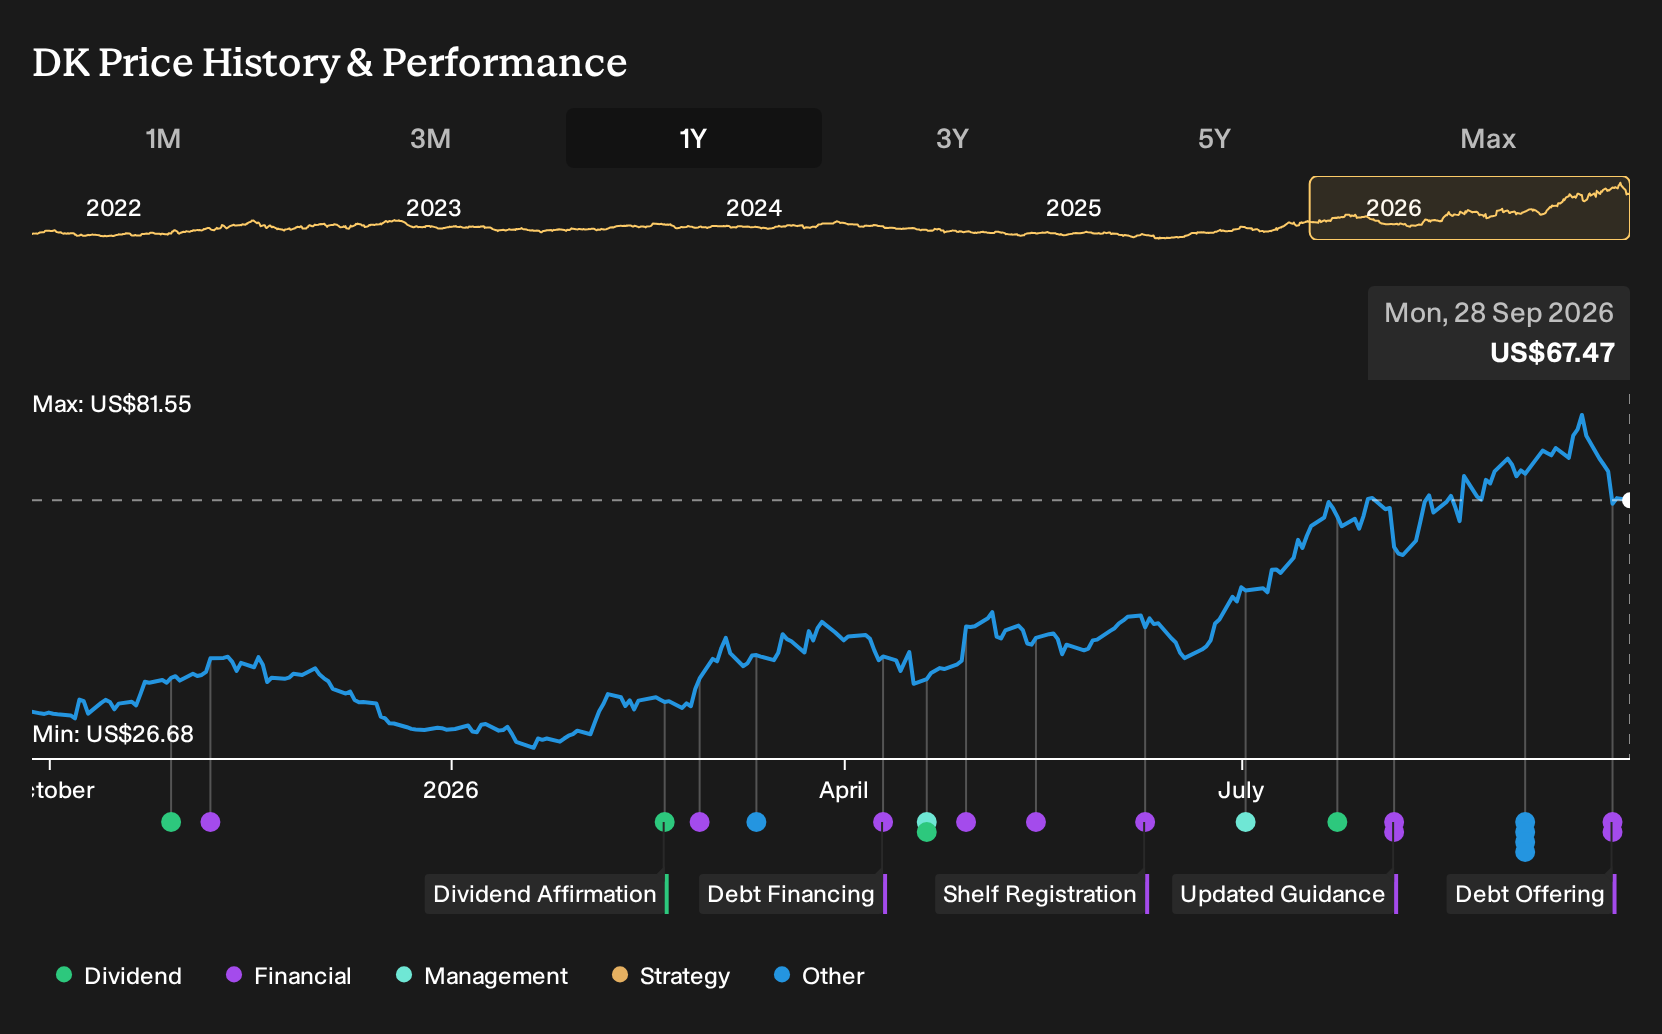
- Delek US Holdings has issued and completed a US$400 million offering of senior unsecured zero coupon convertible notes due November 1, 2031 under Rule 144A, with the notes carrying attached guarantees and callable features.
- The zero coupon, convertible and unsecured structure suggests Delek US Holdings is trading off immediate interest costs against potential future equity dilution while adding flexible long-term funding to support its downstream and midstream plans.
- We will now look at how Delek US Holdings' investment narrative is affected by the new US$400 million convertible note financing.
Compare Delek US Holdings' move into zero coupon convertibles with other balance-sheet focused plays by reviewing the curated list of solid balance sheet and fundamentals (25 results) for potential alternatives in a similar funding mindset.
Delek US Holdings Investment Narrative Recap
To own Delek US Holdings, you need to believe its refining and logistics footprint can keep generating solid cash against a backdrop of flat or softer volumes and rising energy transition pressures. The zero coupon convertible does not change that operating story in a big way in the near term. The key swing factor still sits in refining margins and execution on the enterprise optimization program.
The biggest risk remains the mix of heavy traditional refining exposure, forecast earnings contraction, and already stretched debt service coverage. Extra senior unsecured paper extends funding but does not remove those pressures. If refining conditions or small refinery exemption outcomes turn against Delek, that leverage can start to feel uncomfortable quickly.
The new US$400 million zero coupon convertible due 2031 is the clearest reference point here. It pushes out maturities and comes with no current cash interest, which can give Delek more breathing room as it works on its optimization plan and midstream buildout, but it also shifts some pressure into potential future equity dilution.
For catalysts, the focus remains on the same operational levers. The key question is whether the enterprise optimization program and logistics investments can translate into steadier margins while regulatory outcomes on renewable fuel obligations and small refinery exemptions do not erode that progress. The fresh convertible funding supports that effort in structure, yet it also increases the importance of consistent execution and careful capital allocation over the coming years.
Delek US Holdings' current setup reflects fairly flat revenue expectations and shrinking profitability. Analysts model a top line of US$12.1b and earnings of US$200.0 million by 2029, compared with earnings today of US$226.0 million. That implies a revenue growth rate that is essentially flat and an earnings decline of US$26.0 million between now and the forecast year.
Uncover how Delek US Holdings' fair value indicates an 11% potential upside to its current price that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view focuses less on refinery margins and more on long term demand risk. The most pessimistic analysts worry that faster electric vehicle adoption could drag Delek US Holdings revenue toward about US$10.8b by 2029 and require only US$1.9b in earnings, which supports a far lower P/E. Those estimates were set before this new zero coupon convertible, so you might see those forecasts shift as analysts reassess balance sheet flexibility and long term demand assumptions.
Explore 4 other Delek US Holdings fair value estimates, including one that suggests as much as 90% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own thorough research.
- A great starting point for your Delek US Holdings research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Delek US Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Delek US Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Delek US Holdings?
If the Delek US Holdings story leaves you wanting a broader watchlist, the Simply Wall St Screener can help you quickly surface other companies that better match your risk, return, or income preferences.
- For investors who want potential mispricings backed by balance sheet strength, scan through a curated set of 32 high quality undervalued stocks that combine quality fundamentals with appealing valuations.
- If capital preservation sits higher on your list than aggressive upside, focus on a 30 resilient stocks with low risk scores that may offer more resilient profiles across different market conditions.
- Those hunting for opportunities that are less widely followed can review a 16 high quality undiscovered gems with strong fundamentals that are not yet heavily covered.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com