
Why It’s Time to Load Up on Applied Materials Stock
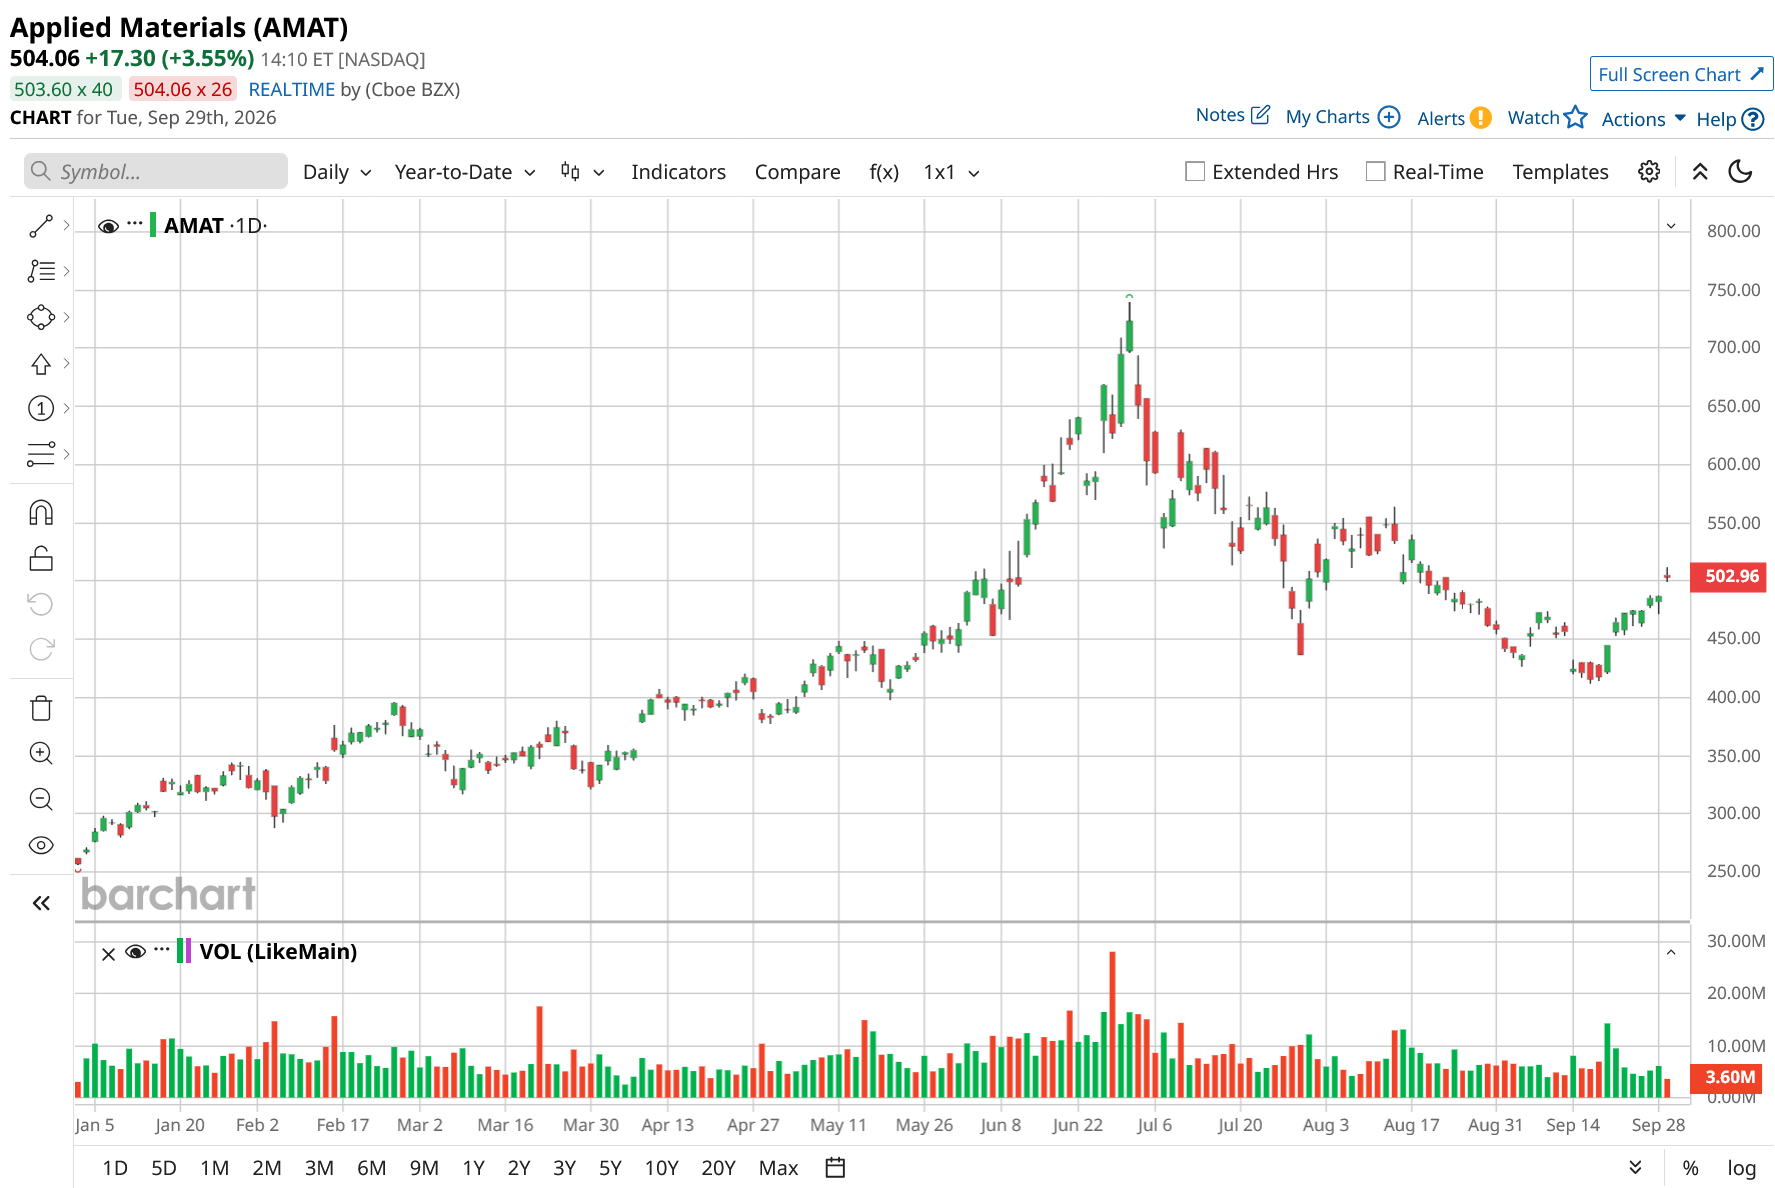
Applied Materials (AMAT) stock has climbed more than 96% year-to-date (YTD), supported by robust artificial intelligence (AI)-related demand for advanced semiconductors and the equipment required to manufacture them.
Looking ahead, continued AI adoption will be a primary catalyst for Applied Materials. As demand for AI computing grows, semiconductor manufacturers are developing increasingly sophisticated chips and are expanding production capabilities. This ongoing investment cycle is creating favorable conditions for Applied Materials, whose semiconductor manufacturing equipment and engineering technologies play a key role in chip production.
Despite its strong gains, the stock has recently pulled back, trading more than 32% below its 52-week high. The decline reflects profit-taking following its substantial rally and creates an opportunity to buy AMAT stock. While its stock has pulled back, Applied Materials is expanding its manufacturing capacity, which will help meet growing demand and support its growth.
These capacity investments indicate that the company is preparing for sustained growth in the semiconductor equipment market and seeking to capitalize on the long-term expansion of AI-driven semiconductor demand.
Applied Materials’ Growth Runway Extends Into 2027 and Beyond
Applied Materials appears well-positioned to sustain strong growth as rising investment in AI infrastructure drives demand for advanced semiconductors. Increasing spending on advanced chips, DRAM, and semiconductor manufacturing capacity is creating favorable conditions for the company. Management expects strong momentum to continue in the quarters ahead.
Demand visibility is also improving for Applied Materials. Large semiconductor customers are providing longer-term commitments, giving Applied Materials visibility into future equipment requirements. This supports a more predictable growth trajectory as customers expand capacity to meet rising semiconductor demand.
Applied Materials’ exposure to leading-edge logic, DRAM, and advanced packaging is strategically important because these technologies influence AI system performance, power efficiency, and overall cost. The company’s established position in these areas, combined with its pipeline of next-generation technologies, provides multiple opportunities to capture semiconductor manufacturers’ increasing capital expenditure.
The demand environment is also being strengthened by continued investment from cloud service providers. As the economic returns from AI infrastructure improve, these companies have greater incentive to maintain elevated capital expenditure. For Applied Materials, this could create a more durable equipment-demand cycle.
Applied Materials’ recent financial results indicate solid momentum. Its third-quarter revenue reached $9.1 billion, up 15% sequentially and 25% year-over-year (YoY).
The company has also raised its expectations for Semiconductor Systems revenue in calendar 2026 and expects to outperform the overall semiconductor equipment market. Management expects favorable conditions to extend into fiscal 2027, supported by stronger customer visibility.
Applied Materials’ improving margins support its investment case. In Q3, its adjusted gross margin increased 150 basis points YoY to 50.4%. At the same time, its adjusted operating margin reached 34%, up 190 basis points sequentially and 330 basis points YoY. Adjusted EPS rose 22% sequentially and 41% YoY to $3.50.
Looking ahead, Applied Materials’ value-based pricing strategy will help support pricing across new and existing products, while cost-efficiency initiatives provide additional protection for profitability despite elevated input costs.
Time to Load Up on AMAT Stock
Overall, Applied Materials’ growth outlook remains solid, driven by structural expansion of the semiconductor industry and the accelerating investment in AI infrastructure. Rising demand for advanced chips, memory, and advanced packaging is encouraging semiconductor manufacturers to increase capacity, creating a favorable environment for semiconductor equipment providers.
Although Applied Materials' stock has gained substantially, its recent pullback has eased valuation concerns. Moreover, its strong EPS growth trajectory suggests that the stock’s valuation remains reasonable.
AMAT stock currently trades at a forward P/E ratio of 37.9, which doesn’t appear stretched given analysts’ expectations for a 43% increase in earnings per share in fiscal 2027.
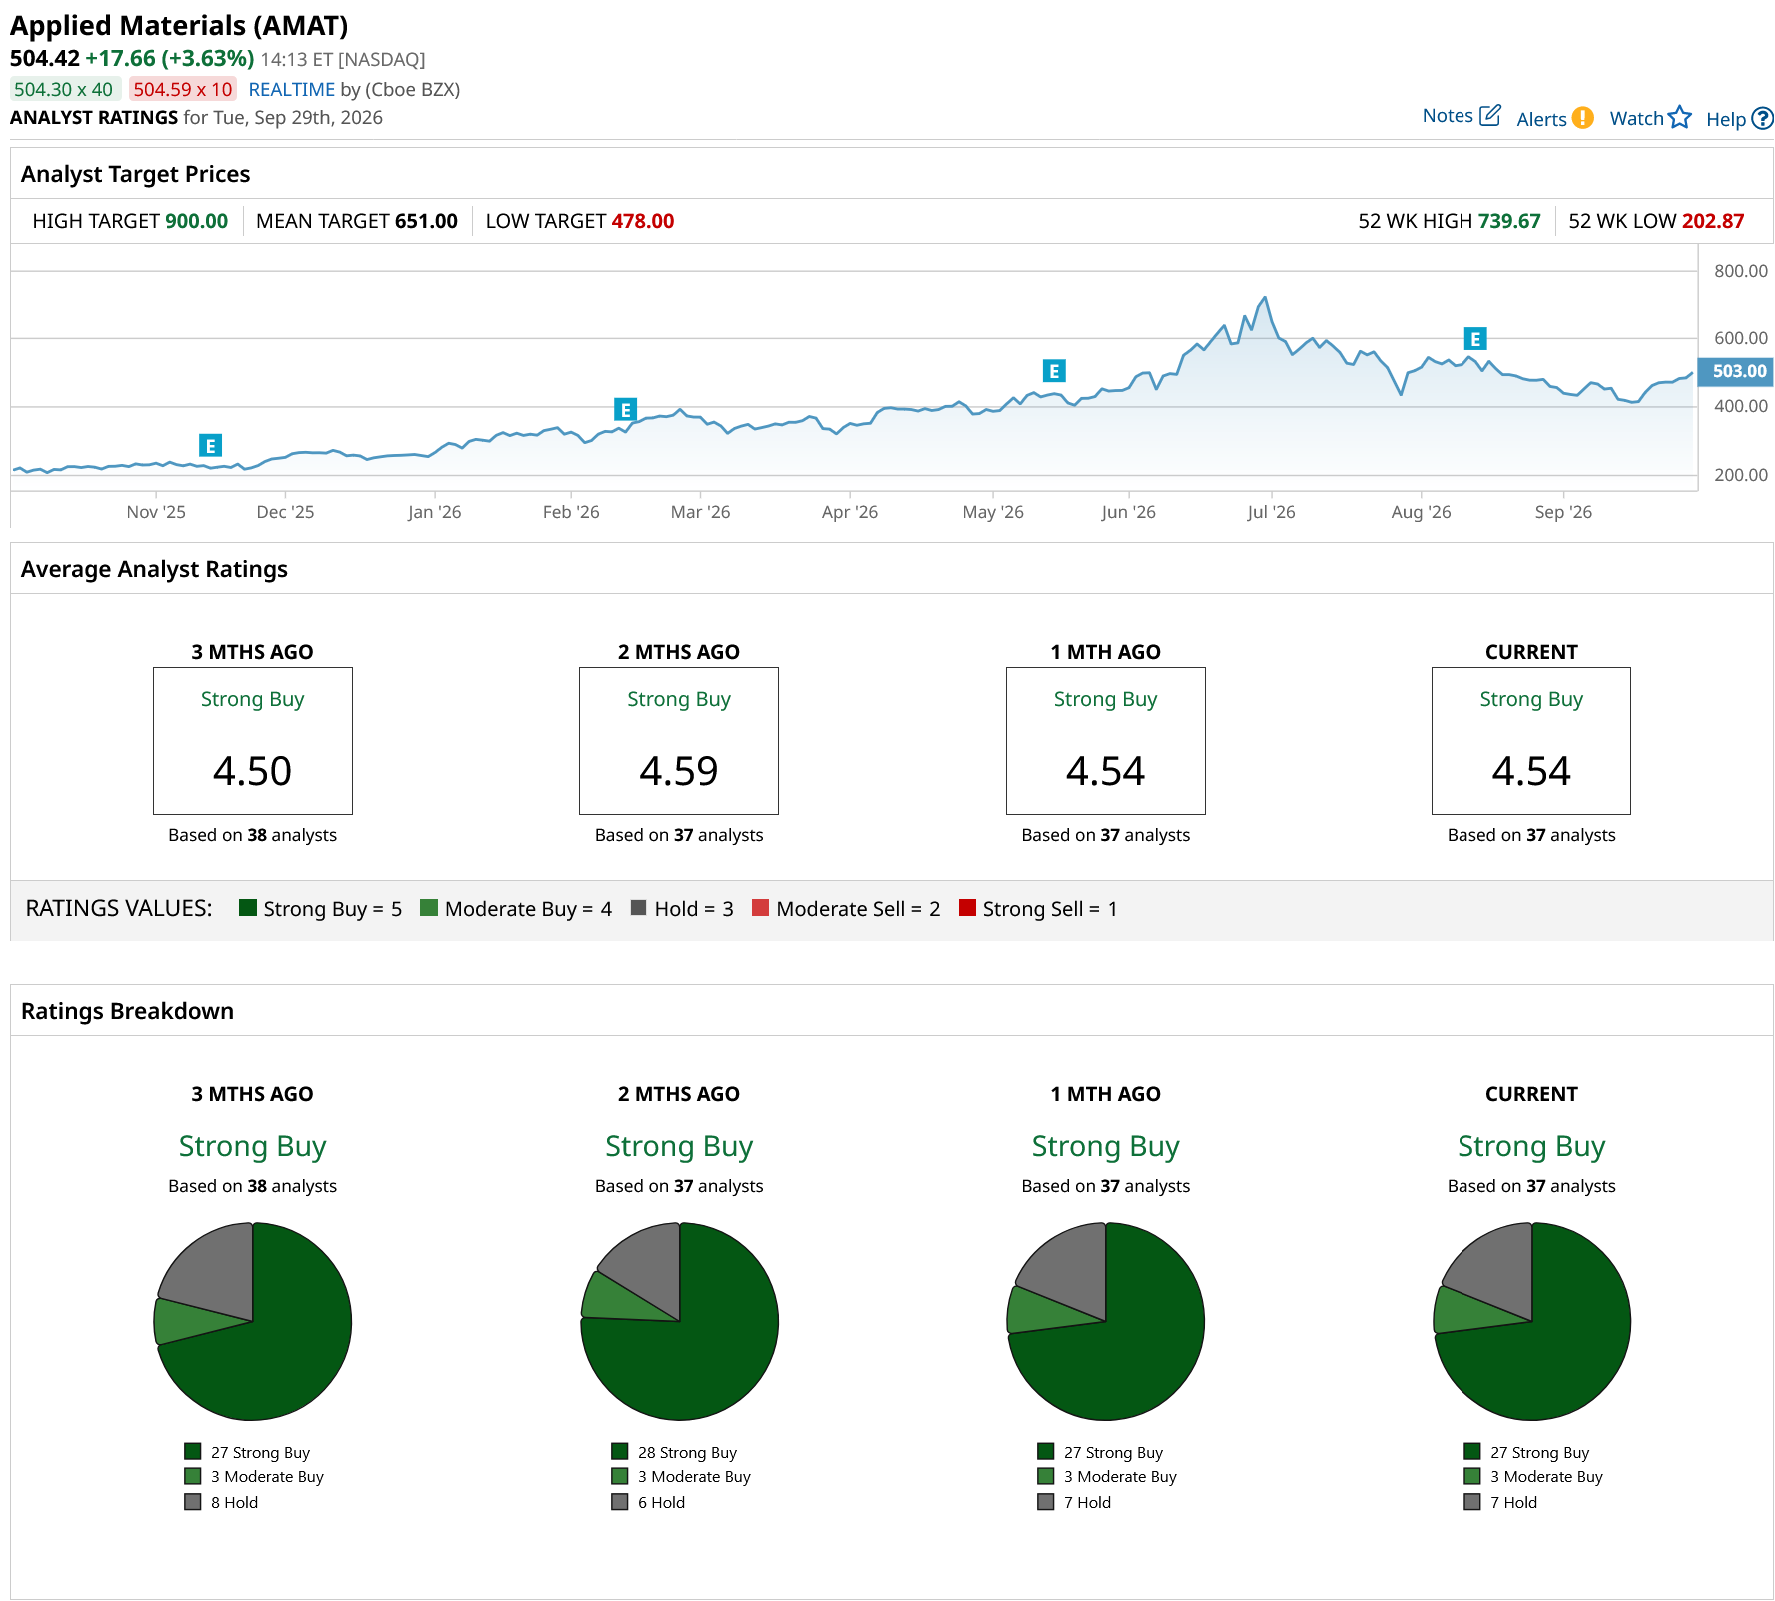
Overall, Applied Materials is well positioned to deliver solid growth. Improving margins and long-term customer commitments further strengthen its growth outlook. Analysts remain bullish, with a “Strong Buy” consensus rating.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.