
3 European Stocks That Could Benefit From Cheap Chinese Imports
European tariffs may stay pointed at Chinese exporters, but the real story for investors sits closer to home. Cheaper Chinese goods are pressuring local manufacturers while quietly improving the economics for installers, distributors and end customers. That mix of risk and potential reward is creating pockets of mispriced opportunity. This article walks through three European stocks exposed to that trade shock, and explains why their current set up deserves a closer look.
The three stocks below are just a sample of the idea, while the full screen surfaced 23 more European consumer and installer beneficiaries of cheaper Chinese imports with equally compelling narratives that are not covered here. To identify and analyze which of those 23 look like the highest conviction plays for your watchlist, head straight to the European consumer and installer beneficiaries of cheap Chinese manufactured imports screener.
Solaria Energía y Medio Ambiente (BME:SLR)
Solaria Energía y Medio Ambiente is a pure-play solar PV generator that fits the screener theme by owning and operating large photovoltaic assets while benefiting from lower equipment costs. It earns most of its €265 million or so in revenue in Spain and has a market value of about €2.1b.
For investors hunting for European beneficiaries of cheaper Chinese solar hardware, Solaria Energía y Medio Ambiente offers a clear test case of how lower panel and battery costs can feed through into returns on a growing asset base.
"Solaria's status as the leading owner of ready-to-build battery storage permits, with over 20 GWh across Spain and broader Europe, positions it to capitalize on recent regulatory tailwinds and subsidy programs. This could unlock a significant new earnings stream, with the potential to materially raise net margins as storage deployment enables greater price optimization and grid services revenue."
What matters next for Solaria is how one unresolved pressure on its project financing costs shapes the payoff from that build out.
If that financing question matters to your thesis, read the full narrative for Solaria Energía y Medio Ambiente to see how Solaria Energía y Medio Ambiente’s story could accelerate or stall.

Engie (ENXTPA:ENGI)
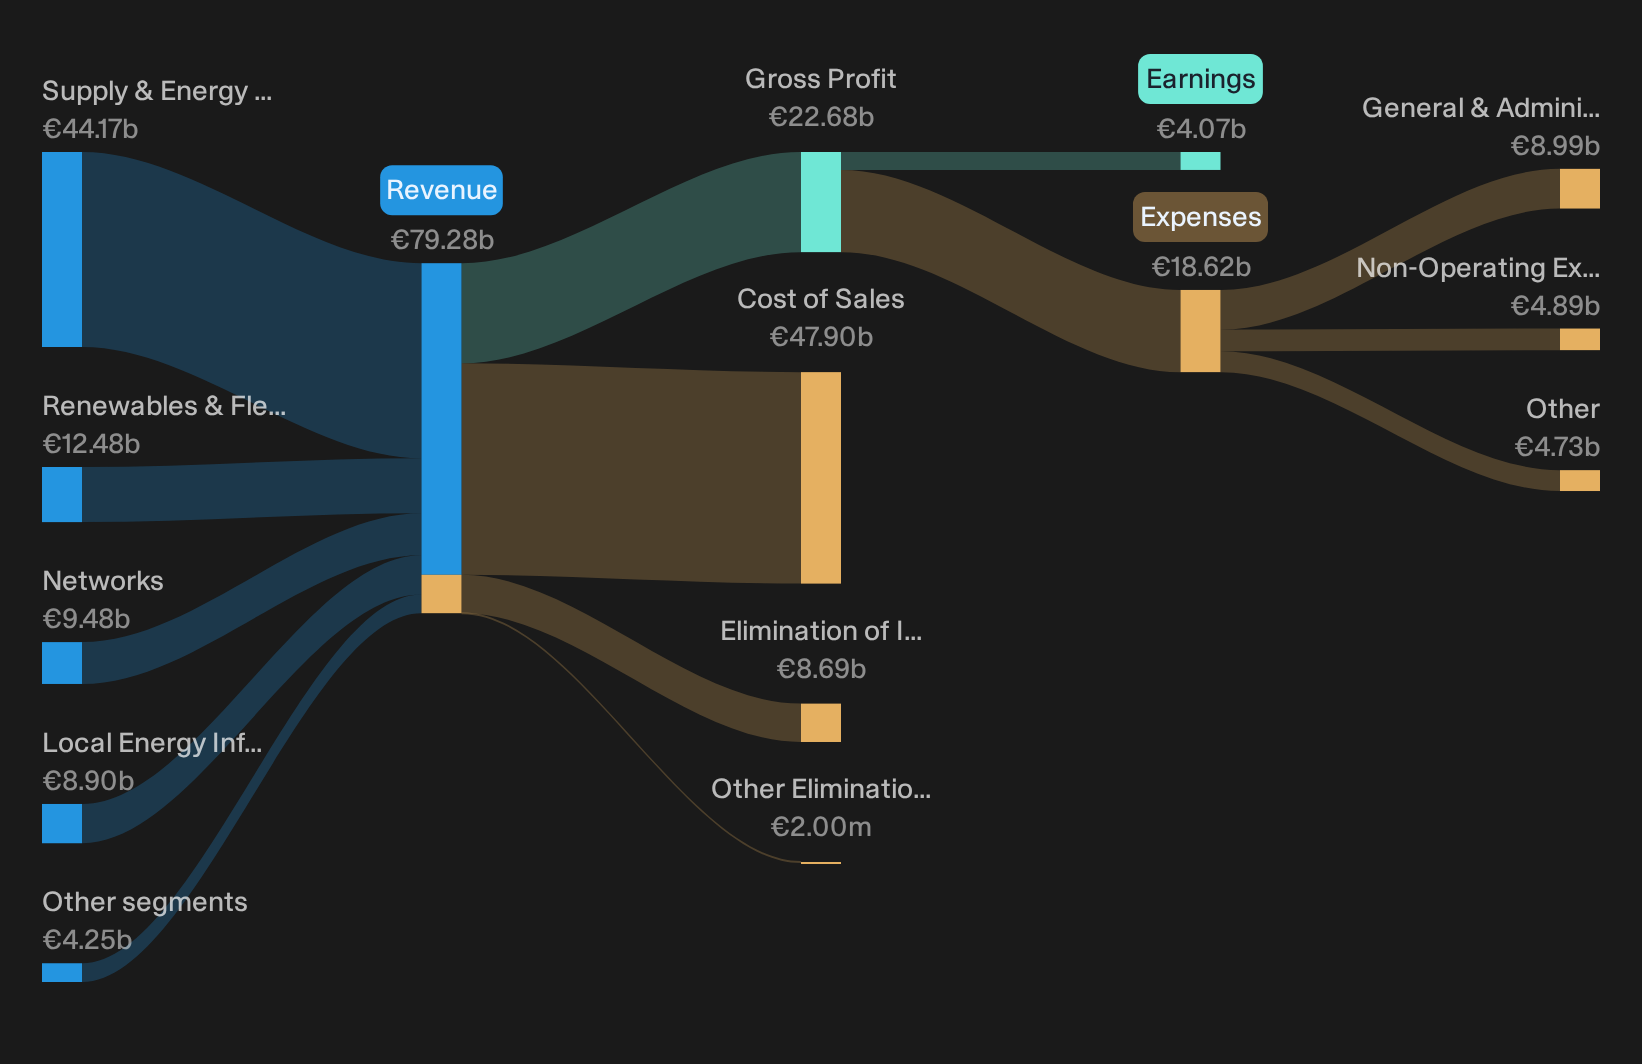
Engie is a €56.4b European utility that fits this screener by using cheaper imported solar and equipment to build and run renewables and local energy networks rather than competing with manufacturers. It generated €44.2b from Supply & Energy Management and €12.5b from Renewables & Flex Power.
Engie matters in this theme because it sits on the demand side of cheap Chinese hardware, using lower equipment costs to scale renewables, grids and local energy systems instead of trying to win a manufacturing price war.
"Surging global electricity demand, particularly from sectors like data centers and the electrification of transport and industry, is creating a long-term structural tailwind for Engie's renewables and network assets, providing strong visibility on future revenue and project pipeline growth."
What happens to Engie’s margins and cash returns if the current mix of cheap kit, policy support and project execution starts to shift?
If that shift is what you care about, read the full narrative for Engie to see how Engie’s growth plans could accelerate or stall from here.
Grenergy Renovables (BME:GRE)
Grenergy Renovables is a Madrid based renewables platform that develops, builds and runs solar, wind and battery projects, which can benefit directly when cheaper Chinese hardware improves project returns. Most of its roughly €1.29b revenue comes from Development & Construction, with additional contributions from Energy and Commercialization, and the stock is valued at about €2.1b.
Grenergy Renovables gives you pure exposure to the cheap hardware side of the story, since every lower priced panel or storage unit can improve the economics of the projects it develops, builds and then holds on its balance sheet or sells on to other owners.
"Rapid scale up of large hybrid PV plus storage platforms in Chile, including Oasis of Atacama and Central Oasis, is set to convert today’s heavy CapEx into recurring energy EBITDA as new gigawatt hours come online and operate increasingly on higher price night-time curves."
What really moves the dial for Grenergy now is how one evolving pressure on its funding model shapes the cash that ultimately drops through to shareholders.
That funding squeeze is the real swing factor, and the full narrative for Grenergy Renovables shows how Grenergy Renovables could turn today’s capital demands into accelerating long term cash generation.

Seeking Alternatives Before Everyone Else
Fresh opportunities do not stay quiet for long. Breakout themes gain momentum, prices start flying, and late money gets caught chasing. Scan these under the radar ideas while it matters and get in early.
- Hunt for cash rich compounders by running the list of solid balance sheet and fundamentals (204 results), built to surface financially robust businesses before the crowd starts bidding up their quality story.
- Track where dependable income might be hiding using the 164 dividend fortresses, a curated set of high yielding payers investors often only notice after yields start dropping.
- Zero in on under loved quality by reviewing the 618 high quality undiscovered gems, a focused pool of overlooked companies that could rerate once their fundamentals stop flying under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com