
UL Solutions (ULS) Expands Retail Testing As Undervalued Narrative Faces A Fresh Test
UL Solutions (ULS) just expanded its Lowell, Arkansas, Retail Center of Excellence by adding apparel and textile testing to its existing work on furniture, toys and electronics for consumer product clients.
Against that expansion backdrop, UL Solutions’ share price has been under pressure, with the 30-day share price return down 12.94% and the 90-day move down 36.38%, while the 1-year total shareholder return has fallen 7.04%. This suggests recent sentiment has cooled, although the company’s longer term record for investors appears less weak than the short term pattern implies.
Scan beyond UL Solutions and compare this testing and certification story with curated peers by reviewing the list of solid balance sheet and fundamentals (25 results), which may be better positioned for the next leg of market attention.
UL Solutions looks like a solid testing and certification platform, backed by fresh investment in its retail lab network, yet the share price has slid hard in recent months. Is that strength already fully priced in or not?
Most Popular Narrative: 34% Undervalued
On the numbers, the most followed narrative puts UL Solutions’ fair value at $98.23 using a 7.34% discount rate, compared with a last close of $64.80. That gap frames a story where the testing and certification group is treated as a quality franchise whose current share price does not fully reflect its earnings profile.
UL Solutions' robust revenue growth, strong profitability, strategic investments, and stable income streams position the company for sustained success and future expansion. Strong cash flow generation and a robust balance sheet, with substantial free cash flow and investment-grade credit ratings, provide flexibility for strategic initiatives and potential acquisitions, which could enhance future earnings growth.
See why 5 investors see UL Solutions as 34% undervalued.
Result: Fair Value of $98.23 (UNDERVALUED)
Still, the narrative can break if higher capital spending on new labs weighs on free cash flow, or if a higher effective tax rate reduces earnings power.
Find out about the key risks to this UL Solutions narrative.
Another View: UL Solutions On Earnings Multiples
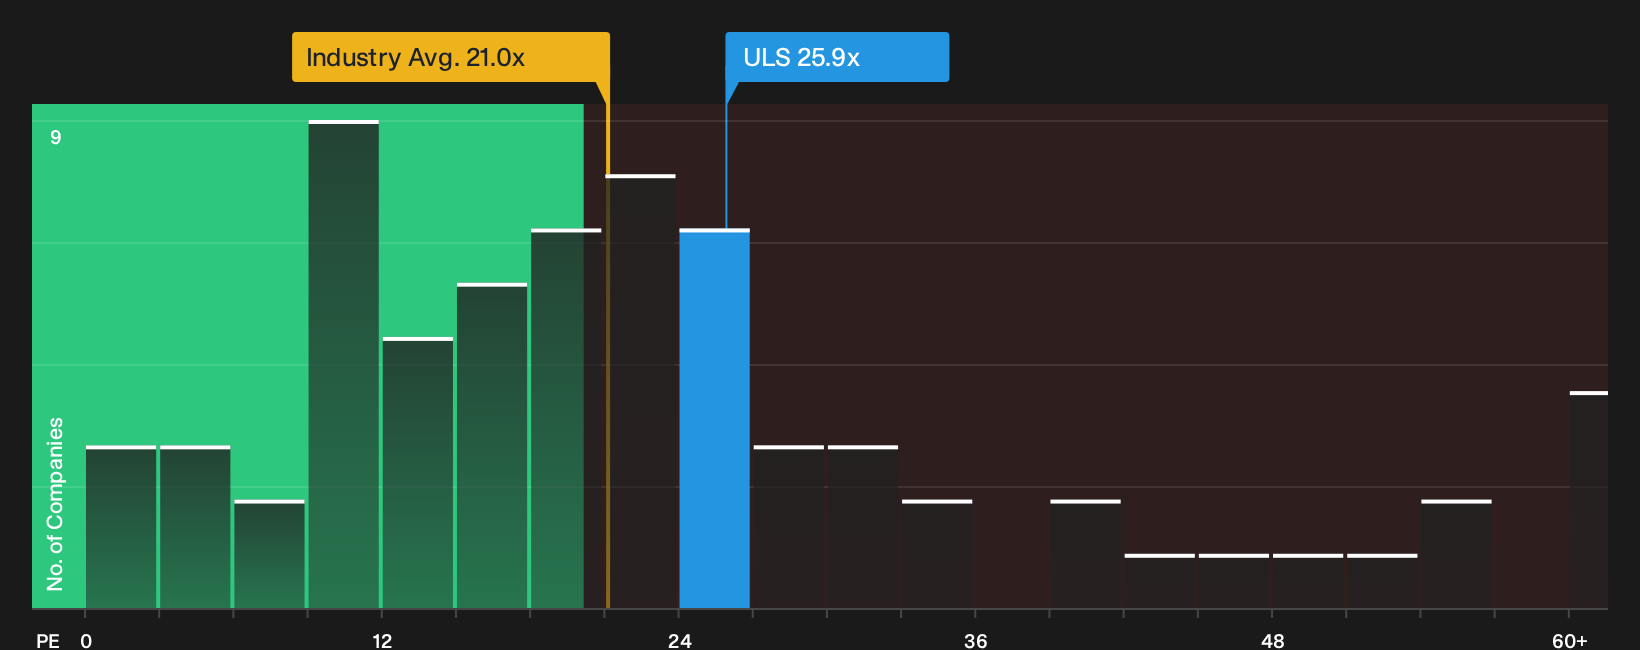
On a simpler yardstick, UL Solutions trades on a P/E of 25.9x, which screens as expensive versus both its own fair ratio of 17.6x and the US Professional Services average on 20.9x. That gap points to richer pricing on this measure. The key question is whether you think the premium is earned or at risk of compressing.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on UL Solutions so far, right? Use the numbers, cross-check the risk flags, and weigh the upside by digging into the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond UL Solutions?
If UL Solutions has caught your attention, do not stop there. Use the Simply Wall Street Screener to surface fresh opportunities that match your style and risk comfort.
- Target resilient balance sheets and steady fundamentals by checking the list of solid balance sheet and fundamentals (25 results).
- Hunt for potential mispriced opportunities by scanning the 32 high quality undervalued stocks.
- Prioritize stability and quality by reviewing the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com