
How Investors May Respond To Bechtle (XTRA:BC8) Index Removal
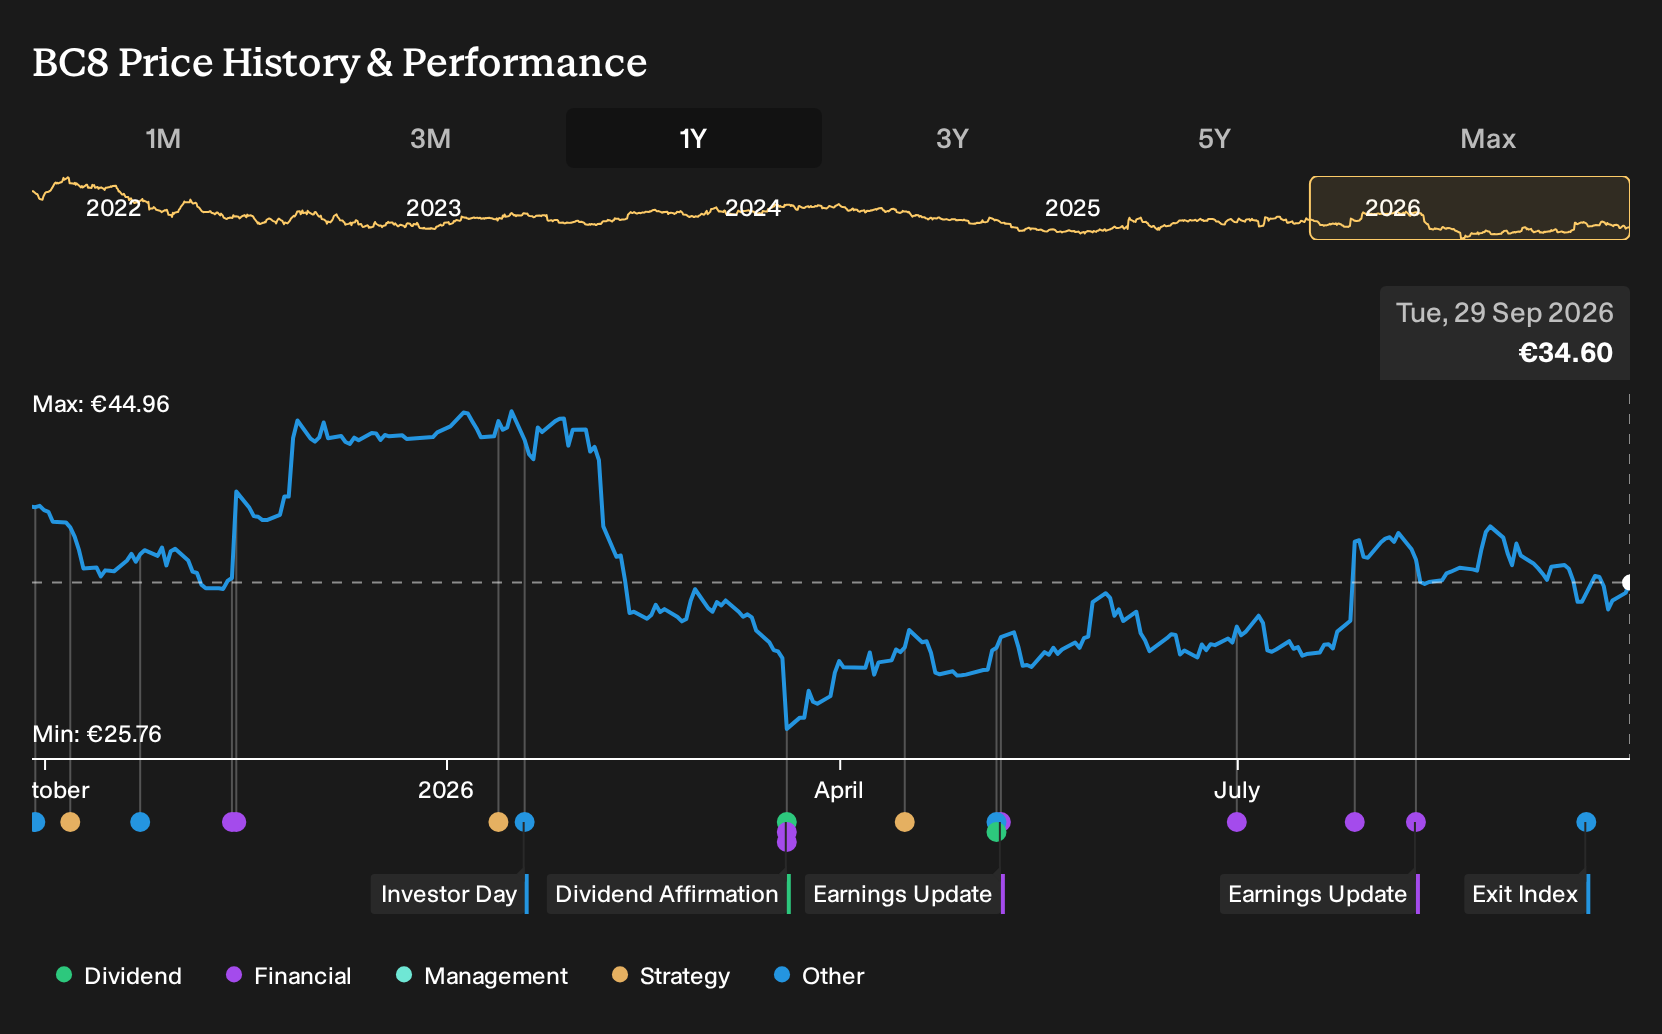
- Bechtle AG was removed from the FTSE All-World Index (USD) in September 2026, following a constituent change that affects index trackers and benchmarked portfolios.
- The index removal sharpens attention on Bechtle’s core IT services operations in Europe. Execution, cost control and demand trends now matter even more to long term investors than benchmark inclusion.
- This article examines how Bechtle’s investment narrative around international expansion and efficiency is affected by its recent removal from the FTSE All-World Index.
Compare Bechtle’s index exit with peers facing similar benchmark pressure, and scan for potential beneficiaries in our curated list of 202 high quality undervalued stocks.
Bechtle Investment Narrative Recap
To own Bechtle today, you need to be comfortable with a European IT services group that is still leaning on international expansion, multichannel offerings and M&A to offset softer demand from SME clients in Germany and France. The FTSE All World exit mainly affects how some funds track the stock. It does not change how many IT projects Bechtle wins or how efficiently those are delivered.
The near term swing factor remains execution on cost control and pricing in a market where personnel expenses and other costs previously ran ahead of revenue. That same cost base is also the biggest risk, especially if SME spending stays muted or vendor incentive changes from partners like Microsoft and Cisco weigh on earnings before efficiency projects gain traction.
Recent commentary around Bechtle has focused on earnings quality, free cash flow and how prepared the group is for vendor model changes, particularly the shift toward cloud services from Microsoft. Those operational topics are directly relevant to an index removal because they influence how resilient revenue and margins might be if passive flows become less supportive and active investors lean harder on fundamentals.
Analysts currently expect earnings to grow around 8% per year, with net profit projected at €303.0 million by about August 2029, and see the stock below both their price target and a DCF based estimate of future cash flow value. For investors, the practical question is whether Bechtle can keep adapting to new partner incentives and cloud heavy contracts fast enough to protect margins while squeezing more productivity from its AI tools, multicloud offerings and international footprint.
Bechtle’s current analyst storyline points to forecast revenue of €8.0b and earnings of €303.0 million by 2029. That outlook assumes yearly revenue growth of 5.9% and an earnings increase of about €57.5 million from earnings today of €245.5 million.
Uncover why Bechtle's fair value indicates a 24% potential upside to its current price, which could narrow quickly if sentiment turns.
Exploring Other Perspectives
One alternate view on Bechtle focuses on vendor disintermediation risk. If Microsoft and others keep pushing direct cloud and SaaS, the most cautious analysts see weaker long run revenue, with only 4.8% annual growth to about €7.8b and earnings of €297.4 million by 2029. Those projections were set before the index removal, so you should expect opinions to shift and explore several angles yourself.
Explore 3 other Bechtle fair value estimates, including one that suggests there could be as much as 34% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bechtle research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bechtle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bechtle's overall financial health at a glance.
Looking for more Bechtle style investment ideas?
If Bechtle’s story has you thinking about portfolio balance, it can help to line it up against a wider set of opportunities that target different risks, income profiles and balance sheet strengths.
- For investors hunting for mispriced opportunities with solid fundamentals, start with a curated 202 high quality undervalued stocks that filters for quality alongside value.
- If capital preservation and a smoother ride matter most to you, consider scanning a 225 resilient stocks with low risk scores that screens for businesses with more resilient profiles.
- To focus on financial resilience and cleaner balance sheets, work through a list of solid balance sheet and fundamentals (204 results) that highlights companies with stronger financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com